
Compliance Carbon Credit Market Overview
Carbon markets are generally divided into two main categories: voluntary carbon markets and compliance carbon markets.
Compliance carbon markets operate under laws or regulations that require certain companies or sectors to limit, reduce, or pay for their greenhouse gas emissions. Governments can use several approaches to put a price on carbon, including emissions trading systems (ETSs) and carbon taxes.
In an ETS, a government or regulator sets rules for covered emissions and creates a limited supply of allowances. Each allowance typically represents the right to emit one metric ton of carbon dioxide equivalent (tCO₂e). Companies that emit less than their available allowances may be able to sell surplus units, while companies that exceed their limits may need to buy additional allowances or other eligible units to meet their compliance obligations.
Unlike the voluntary carbon market, demand in compliance markets is created primarily by legal and regulatory requirements. This makes government policy one of the most important factors affecting allowance supply, demand, and prices.
Compliance carbon pricing has expanded significantly over the past decade. The World Bank reported that, as of April 1, 2026, 87 direct carbon-pricing instruments were in operation worldwide, including 40 emissions trading systems and 47 carbon taxes. Together, these systems covered just over 29% of global greenhouse gas emissions.
The growth of these systems has also increased the economic importance of carbon pricing. Direct carbon-pricing instruments generated more than $107 billion in public revenue in 2025, according to the World Bank.
Executive Summary
This guide explains how compliance carbon markets work and examines the major systems shaping global carbon pricing.
It covers:
- 1. Compliance Carbon Market Landscape
- 2. The European Union ETS
- 3. California Cap-and-Trade Program
- 4. China National Emissions Trading System
- 5. Other Major Compliance Carbon Markets
- 6. Compliance Markets vs. Carbon Credits
- 7. Risks and Challenges in Compliance Carbon Markets
- 8. Investing in the Compliance Carbon Credit Markets
Compliance carbon markets have expanded far beyond the handful of major systems that dominated the market when this guide was first published. Today, carbon pricing is used across national, regional, and subnational jurisdictions, with each system operating under its own rules, emissions coverage, and pricing mechanisms.
As a result, there is no single global compliance carbon credit price or one uniform model for carbon trading. The value of allowances and other eligible compliance units depends on government policy, emissions caps, economic activity, energy demand, market design, and the availability of supply.
Understanding these differences is essential for anyone seeking to understand how compliance carbon markets work and how they are evolving.
Compliance Carbon Market Landscape
The global compliance carbon market has expanded well beyond the small group of emissions trading systems that dominated the market a few years ago.
In 2026, 41 emissions trading systems (ETSs) are in force worldwide, covering about 26% of global greenhouse gas emissions, according to the International Carbon Action Partnership (ICAP). Three national ETSs — in Japan, India, and Vietnam — launched in 2026, while additional systems remain under development or consideration.
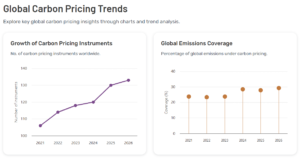
When carbon taxes are included, the global carbon pricing landscape is even larger. The World Bank counts 87 implemented direct carbon pricing instruments in 2026, comprising 40 ETSs and 47 carbon taxes. Together, these instruments cover nearly 30% of global GHG emissions.
Major Compliance Carbon Markets
Several large systems continue to shape global carbon pricing:
- European Union: The EU Emissions Trading System (EU ETS) remains one of the world’s largest and most established carbon markets.
- China: China’s national ETS is the world’s largest emissions trading system by covered emissions and continues to expand its sectoral coverage.
- California: California’s cap-and-trade program is a major North American carbon market and operates as part of the broader Western Climate Initiative.
- United Kingdom: The UK operates its own ETS following its departure from the EU ETS.
- South Korea: The Korea ETS remains one of Asia’s largest carbon markets.
- New Zealand: The New Zealand ETS covers major parts of the country’s economy, including forestry.
- Australia: The Safeguard Mechanism uses a baseline-and-credit approach to regulate emissions from large industrial facilities.
- Japan, India and Vietnam: All three launched national ETSs in 2026, adding significant new sources of regulated carbon market demand.
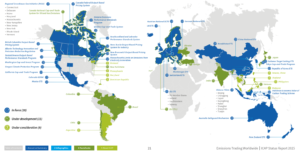
Other compliance systems operate at the national, regional, or subnational level. The World Bank’s carbon pricing database tracks systems across North America, Europe, Asia, Latin America, Africa, and other regions.
Carbon Market Revenues Are Growing
The expansion of compliance markets has also increased their financial importance.
ETSs generated a record nearly $80 billion in revenue in 2025, according to ICAP. Across carbon taxes and ETSs, the World Bank estimates that direct carbon pricing generated more than $107 billion for public budgets in 2025.
These revenues can support climate programs, clean energy investment, infrastructure, and other government priorities. The exact use of the funds varies by jurisdiction.
A More Fragmented Global Market
The growth of compliance carbon markets creates a larger global market but also increases fragmentation.
Each system has its own rules for emissions coverage, allowance allocation, caps, auctions, offsets, banking, borrowing, and compliance. Prices can therefore differ significantly between jurisdictions.
This fragmentation is also important for companies operating across multiple countries. A business may face different carbon costs depending on where its facilities operate and which emissions are covered by local regulations.
For investors and market participants, understanding the design of each individual system is therefore more important than treating compliance carbon markets as one global market.
- The global compliance carbon market is no longer defined by three major ETSs. It is now a growing network of national, regional, and subnational systems, with governments increasingly using carbon pricing as a tool to reduce emissions and support the transition to lower-carbon economies.
So, let’s break down each major compliance credit market…
The European Union ETS
The European Union Emissions Trading System (EU ETS) is the world’s first major emissions trading system and remains the largest ETS by trading volume and value. It began in 2005 and covers the EU Member States plus Iceland, Liechtenstein, and Norway. Its main sectors include power, industry, aviation, and maritime transport. EU ETS-covered emissions account for about 40% of the EU’s total greenhouse gas emissions.
The system uses a cap-and-trade model. Companies must surrender one EU Allowance (EUA) for each tonne of CO₂ equivalent they emit. Allowances are allocated through auctions and, for some industries, free allocation.
EU ETS Emissions and Targets
The EU has steadily tightened the emissions cap. The current system is designed to reduce covered emissions by 62% by 2030 from 2005 levels. Since the ETS launched, emissions in its covered sectors have already fallen by about 50%. Verified emissions declined another 1.3% in 2025.
Maritime transport entered the EU ETS in 2024. A separate ETS2 covering buildings, road transport, and additional sectors is scheduled to begin auctioning allowances in 2027.
EU Carbon Allowance Prices
The 2026 EU ETS cap is approximately 1.185 billion tCO₂e for electricity, heat, industry, and maritime transport, plus 26.2 million tCO₂e for aviation.
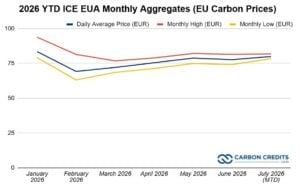
The average 2026 auction price is about €73.43 ($82.97) per tonne, while the average secondary-market price is €74.35 ($84.01). Prices fluctuate with energy demand, economic conditions, fuel prices, allowance supply, and expectations about future climate policy.
The EU’s Market Stability Reserve (MSR) also adjusts allowance supply to address major imbalances in the market.
EU ETS Revenue
The EU ETS has become a major source of climate-related funding. Auctions generated more than €43 billion in 2025, while total auction revenue since 2013 exceeded €258 billion by the end of 2025.
EU Member States and EU funds use this revenue to support clean energy investment, industrial decarbonization, and the broader energy transition.
The EU ETS remains a central part of Europe’s climate policy and is expected to become increasingly important as the bloc works toward climate neutrality by 2050.
California Cap-and-Trade Program
California’s Cap-and-Trade Program, now part of the state’s broader Cap-and-Invest Program, began in 2012 and is one of North America’s longest-running compliance carbon markets. It operates jointly with Québec’s carbon market through the Western Climate Initiative.
The program requires covered entities to surrender allowances equal to their greenhouse gas emissions. It covers large industrial facilities, electricity generators and importers, fuel suppliers, and other regulated entities. California’s program is designed to help achieve the state’s economy-wide target of reducing emissions 40% below 1990 levels by 2030 and reaching carbon neutrality by 2045.
California Carbon Allowance Prices
California allowances are sold through quarterly auctions and traded in the secondary market.
For 2026, California’s annual auction reserve price is $27.94 per allowance. In the August 2025 joint auction with Québec, California allowances cleared at $28.76 in the current auction and $28.50 in the advance auction.
The program also has a price-ceiling mechanism to limit extreme compliance costs. The 2026 price-ceiling sale price is $102.52 per allowance or price-ceiling unit.
California Cap-and-Trade Revenue
California generates significant public revenue from allowance auctions. The funds are deposited into the state’s Greenhouse Gas Reduction Fund and support programs intended to reduce emissions, improve air quality, expand clean transportation, and advance climate-related investments.
California’s carbon market is therefore both a regulatory mechanism and an important source of funding for the state’s climate policies.
The program continues to evolve as California prepares for its 2030 emissions target and 2045 carbon neutrality goal, with future changes expected to influence allowance supply, demand, and prices.
China National Emissions Trading System
China launched its national Emissions Trading System (ETS) in 2021, creating the world’s largest emissions trading system by covered emissions. The market initially focused on the power sector but has since expanded significantly.
In 2025, China officially added the steel, cement, and aluminum smelting sectors to the national ETS. The expansion brought about 1,500 additional facilities into the system and increased coverage to roughly 60% of China’s total greenhouse gas emissions.
The new sectors entered the first compliance cycle covering 2024–2025 emissions, with detailed allowance-allocation rules released in late 2025. The system is expected to tighten over time as China moves toward more stringent emissions benchmarks.
China Carbon Allowance Prices
China’s national carbon market trades China Emission Allowances (CEAs). Unlike the EU ETS, China’s system has historically relied heavily on free allocation and carbon-intensity benchmarks rather than a fixed absolute emissions cap.
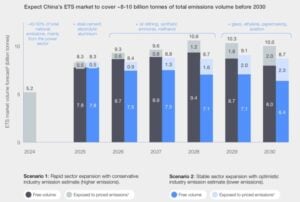
Carbon prices remain significantly below those in the EU ETS. Market prices are influenced by allowance allocation, industrial output, energy demand, regulatory changes, and expectations about future tightening.
China’s Climate Targets
China has pledged to peak carbon dioxide emissions before 2030 and achieve carbon neutrality before 2060. The national ETS is one of the policy tools being used to support these goals.
The expansion into heavy industry marks an important change for China’s carbon market. As the system covers more sectors and allowance allocation becomes more stringent, its influence on industrial emissions and China’s broader carbon-pricing strategy is expected to increase.
Other Major Compliance Carbon Markets
The global compliance carbon market now extends well beyond the EU, California, and China. In 2026, 41 emissions trading systems (ETSs) are in force worldwide, covering about 26% of global greenhouse gas emissions. Another 16 systems are under development or consideration, according to the International Carbon Action Partnership.
Several established markets are important parts of this expanding network:
- United Kingdom: The UK ETS began in 2021 after the country left the EU ETS. It covers energy-intensive industries, power generation, and aviation.
- South Korea: The Korea ETS (K-ETS) launched in 2015 and covers about 78% of the country’s GHG emissions, making it one of Asia’s largest compliance markets.
- New Zealand: The New Zealand ETS covers major sectors including forestry, industrial processes, and waste. The government has set unit-supply limits through 2030.
- Australia: Australia’s Safeguard Mechanism regulates emissions from large industrial facilities using declining baselines and tradable Safeguard Mechanism Credits. The policy is being reviewed during 2026–2027.
- Japan: Japan’s national ETS launched in 2026 as part of its GX policy framework.
- India: India’s national Carbon Credit Trading Scheme began its transition toward an emissions-trading framework in 2026.
- Vietnam: Vietnam launched its national ETS in 2026, initially focusing on major emitting sectors.
These newer systems reflect a broader shift toward emissions trading in emerging and developed economies. ICAP reports that ETSs are now operating in 14 G20 nations, while the World Bank finds that all large middle-income economies have either implemented or are planning direct carbon pricing instruments.
The result is a more diverse global compliance market. Each system has different rules for emissions coverage, allowance allocation, caps, offsets, banking, and trading. These differences mean that allowance prices and market risks can vary significantly between jurisdictions.
Compliance Markets vs. Carbon Credits
Compliance carbon markets and carbon credit markets are related, but they are not the same thing.
Most emissions trading systems primarily trade emissions allowances. An allowance gives a regulated company the right to emit a specified amount of greenhouse gases under that system. For example, one EU Allowance (EUA) represents the right to emit one tonne of CO₂ equivalent under the EU ETS.
Carbon credits are different. A carbon credit generally represents one tonne of greenhouse gas emissions reduced or removed by a project or program. Credits can come from activities such as methane capture, reforestation, renewable energy, or carbon removal.
Allowances vs. Carbon Credits
The key difference is how the units are created and used:
- Compliance allowances: Created by a government or regulatory authority as part of an emissions trading system. Covered companies use them to meet legal emissions obligations.
- Carbon credits: Generated by emissions-reduction or carbon-removal projects and typically represent one tonne of CO₂e reduced or removed.
- Compliance markets: Operate under mandatory government rules, with demand driven by regulated entities.
- Voluntary carbon markets: Allow companies and other buyers to purchase and retire credits voluntarily.
Some compliance systems allow certain carbon credits or other external units to be used for compliance, subject to specific rules. However, this does not make all carbon credits equivalent to compliance allowances. Eligibility depends on the jurisdiction and its regulations.
The World Bank tracks ETSs, carbon taxes, and carbon crediting mechanisms as separate categories within its global carbon pricing data.
This distinction is important when comparing prices. A compliance allowance and a voluntary carbon credit can both be quoted in dollars or euros per tonne, but their prices reflect different market structures, regulations, supply constraints, and compliance requirements. The World Bank also cautions that carbon prices across jurisdictions are not directly comparable because coverage and compliance arrangements differ.
Understanding this difference is essential when evaluating compliance carbon markets, carbon-credit markets, or investment products linked to either market.
Risks and Challenges in Compliance Carbon Markets
Compliance carbon markets can help reduce emissions, but they also face several risks that can affect companies, governments, and investors.
Policy and Regulatory Risk
Compliance markets depend heavily on government policy. Changes to emissions caps, allowance allocation, eligible sectors, compliance rules, or climate targets can affect both supply and demand.
As more jurisdictions introduce or expand carbon pricing, companies must also monitor changes across multiple regulatory systems. The World Bank counted 87 implemented carbon-pricing instruments in 2026, including 40 ETSs and 47 carbon taxes. This growing number of systems also increases regulatory complexity.
Carbon Price Volatility
Allowance prices can rise or fall as economic conditions, energy prices, industrial output, weather, emissions levels, and policy expectations change.
Some markets use mechanisms to manage excessive price movements or supply imbalances. For example, the EU ETS uses a Market Stability Reserve (MSR) to adjust allowance supply. In 2026, about 190.5 million EU allowances are scheduled to be placed into the reserve between September 2026 and August 2027.
Oversupply and Allowance Scarcity
An ETS can become less effective if too many allowances remain available. Oversupply can weaken the carbon-price signal and reduce incentives to cut emissions.
The opposite problem can also create challenges. A shortage of allowances can push prices sharply higher and increase compliance costs for businesses. Well-designed market-stability mechanisms aim to balance these risks.
Carbon Leakage and Competitiveness
Companies operating in carbon-priced jurisdictions may face higher costs than competitors in regions with weaker or no carbon pricing. This can create concerns about carbon leakage, where production or investment shifts to jurisdictions with less stringent climate policies.
Governments use measures such as free allowance allocation and border carbon measures to address these risks. The EU, for example, continues to provide some free allowances to sectors considered vulnerable to carbon leakage.
Fragmented Global Markets
There is no single global compliance carbon market. Each jurisdiction can use different rules, allowance designs, emissions caps, and compliance requirements.
As a result, carbon prices are not directly comparable across markets. The World Bank specifically notes that differences in coverage, compliance requirements, and compensation arrangements make cross-market price comparisons difficult.
These challenges mean that compliance carbon markets require ongoing policy oversight and careful market design. For businesses and investors, understanding the specific rules of each market is essential before assessing its carbon price, compliance costs, or investment potential.
Investing in the Compliance Carbon Credit Markets
Compliance carbon markets can provide investment exposure to carbon prices, but they differ significantly from traditional commodity and financial markets. Their performance is closely linked to government policy, emissions caps, energy markets, and economic activity.
Direct participation is also not the same in every jurisdiction. Some markets restrict who can hold or surrender compliance allowances, while financial exchanges offer derivatives that provide price exposure without requiring investors to directly manage allowances.
How Investors Can Gain Exposure
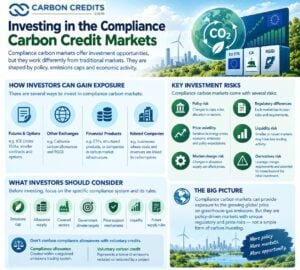
One of the main routes is through futures and options linked to carbon allowances. For example, ICE Endex lists futures and options based on EU Allowances (EUAs). A standard EUA futures contract represents 1,000 EUAs, with each EUA representing one tonne of CO₂ equivalent. ICE also offers smaller EUA contracts and EUA options.
Other exchanges offer derivatives linked to regional compliance markets, including California carbon allowances and the Regional Greenhouse Gas Initiative (RGGI).
Investors may also gain indirect exposure through financial products, companies involved in carbon market infrastructure, or businesses whose costs and revenues are affected by compliance carbon prices. The availability of these products varies by market and jurisdiction.
Key Investment Risks
Compliance carbon markets carry several important risks:
- Policy risk: Governments can change emissions caps, allocation rules, eligible sectors, or other market regulations.
- Price volatility: Allowance prices can respond sharply to energy prices, economic conditions, emissions levels, and policy expectations.
- Market-design risk: Changes in allowance supply can significantly affect prices.
- Regulatory differences: Each compliance market has its own rules, making global exposure more complex.
- Liquidity risk: Smaller or newer markets may have less trading activity than established systems such as the EU ETS.
- Derivatives risk: Futures and options can involve leverage, margin requirements, and the potential for losses beyond an initial investment.
The expansion of compliance carbon markets does not remove these risks. Instead, it creates more markets with different regulatory and economic drivers.
What Investors Should Consider
Before investing, investors should understand the specific compliance system behind the product. Key factors include the market’s emissions cap, allowance supply, covered sectors, government climate targets, price-support mechanisms, trading liquidity, and rules governing future supply.
Compliance carbon allowances should also not be confused with voluntary carbon credits. An allowance is created within a regulated emissions trading system, while a carbon credit generally represents a tonne of emissions reduced or removed by a project.
Compliance carbon markets can therefore offer exposure to the growing global price on greenhouse gas emissions, but they should be evaluated as policy-driven markets with significant regulatory and price risks, rather than as a simple form of carbon investing.
The Bottom Line
Compliance carbon markets have grown from a small number of regional systems into a global network of 41 emissions trading systems and 47 carbon taxes.
These markets now cover more than 29% of global greenhouse gas emissions, while direct carbon pricing generated more than $107 billion in public revenue in 2025. New national ETSs in Japan, India, and Vietnam are further expanding the global carbon pricing landscape.
The EU ETS, California’s cap-and-trade program, and China’s national ETS remain important markets, but they now operate alongside dozens of other systems with different rules and price structures.
For companies, understanding these markets is increasingly important as governments tighten emissions policies and carbon costs become a larger part of business decisions. For investors, compliance carbon markets can provide exposure to carbon prices, but they also carry significant policy, regulatory, market, and price risks.
The key point is that there is no single global carbon price or compliance market. Each system has its own rules, emissions coverage, allowance supply, and compliance requirements.
As carbon pricing expands, these differences will remain central to how compliance carbon markets develop and how businesses and investors participate in them.