
Disseminated on behalf of Sierra Madre Gold & Silver Ltd.
Mexico remains the world’s largest silver-producing country, but its output declined in 2025. As global silver supply struggles to expand, the country’s mature mining districts, existing infrastructure, and pipeline of established assets could become increasingly important to the next supply cycle. Sierra Madre Gold & Silver is developing two such assets through La Guitarra and Del Toro.
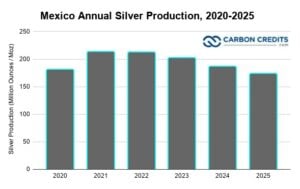
Mexico occupies a unique position in the global silver market. The country produced 172.9 million ounces of silver in 2025, according to the World Silver Survey 2026, accounting for roughly one-fifth of global mine production.
However, Mexico’s dominance does not mean its silver output is continually increasing. Production fell 5% from 181.1 million ounces in 2024, even as global silver mine production increased 3% to 846.6 million ounces.
That contrast matters.
Mexico is the largest source of mined silver in the world. Yet, it’s getting harder to keep or boost production as mature mines decline and the global market faces deficits.
For the silver market, the question is therefore not simply how much silver Mexico produces today. It is whether the country can continue supplying significant volumes as existing operations mature.
Sierra Madre Gold & Silver offers a case study in one potential response. The company operates the La Guitarra complex in Temascaltepec, State of Mexico, and is advancing the restart of the Del Toro complex in Zacatecas.
Both are established mining assets with existing infrastructure and production histories.
Mexico Remains the World’s Silver Leader
Mexico has held the top position in global silver production for years. Its 2025 output of 172.9 million ounces represented approximately 20% of global mine production.
Peru ranked second, followed by China, Poland, and Bolivia, according to the Silver Institute and Metals Focus.
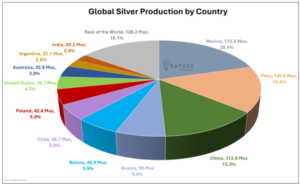
The scale is significant. In 2025, Mexico made more silver than many countries did in their whole mining sectors. This makes its output a key factor in the global supply.
Yet, the 5% year-over-year decline also illustrates the challenge facing mature silver jurisdictions.
Being the largest producer does not guarantee production growth.
Mining assets age. Ore grades can change. Underground development becomes more complex. Processing plants require investment. Permits and infrastructure must be maintained.
At the same time, new deposits take years to move from discovery to production. This creates a potential role for established mining districts and brownfield assets.
The Next Supply Cycle May Depend on Existing Districts
A large part of Mexico’s silver production comes from mining districts with decades or even centuries of operating history.
That creates an unusual advantage. Established districts can have roads, power systems, water infrastructure, processing facilities, underground workings, and experienced mining workforces already in place.
Those assets do not eliminate development costs or operating risks. But they can change the starting point for companies seeking to restart or expand production.
This is particularly relevant in a market where global mine supply is not responding quickly enough to close persistent deficits.
The World Silver Survey 2026 recorded a 40.3-million-ounce deficit in 2025, the fifth consecutive annual deficit. Metals Focus expects another 46.3-million-ounce deficit in 2026.
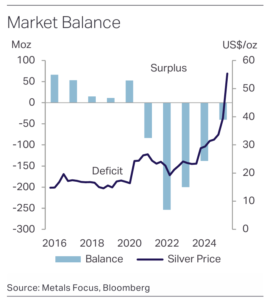
If global supply needs additional ounces, bringing established assets back online could form part of the response.
Mexico has a large inventory of those assets.
La Guitarra Sits Inside Mexico’s Historic Silver Belt
Sierra Madre’s La Guitarra complex provides one example. Located near Temascaltepec in the State of Mexico, La Guitarra is part of a historic silver-producing district.
Sierra Madre acquired the operation from First Majestic Silver and restarted commercial production on January 1, 2025. The operation already had a processing plant and established underground workings, allowing Sierra Madre to restart production without developing an entirely new mine and mill.
The company has since been expanding the operation.
The original processing configuration was approximately 500 tonnes per day. Sierra Madre is now targeting 750–800 tpd in its first expansion phase and 1,200–1,500 tpd by Q3 2027 in the second phase.
In September 2026, the company reported steady throughput of up to 720 tpd as development advanced at the Guitarra and Nazareno mines. This progression shows how an established Mexican asset can become a source of incremental supply.
Instead of starting with a discovery and building an entirely new mine, Sierra Madre started with a past-producing operation and is investing to increase its capacity.
Del Toro Adds a Second Mexican District
Sierra Madre’s Mexican strategy extends beyond La Guitarra. In June 2026, the company completed the acquisition of the Del Toro Silver Mine in Zacatecas from First Majestic.
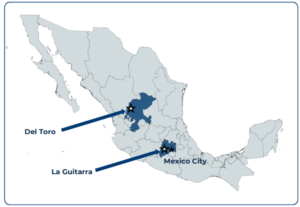
Zacatecas is one of Mexico’s most important historic silver-producing regions and has been a major contributor to the country’s position in global silver mining.
Del Toro itself operated from 2013 through 2019 under First Majestic. The property includes three underground mines, San Juan, Perseverancia and Dolores, together with more than 62.5 kilometers of existing underground development.
The complex also contains a 3,000-tonnes-per-day flotation facility, as well as other processing and infrastructure assets. This infrastructure provides Sierra Madre with a solid base to assess future production.
The company plans to restart Del Toro at approximately 800 tpd, with potential to increase throughput to 1,600 tpd.
Sierra Madre currently targets the restart process for mid-2027 and first production for mid-2028. These are company targets and depend on the completion of technical, development and operational work.
Zacatecas Shows Why Existing Infrastructure Matters
Del Toro’s history also demonstrates the depth of Mexico’s established mining infrastructure.
First Majestic invested approximately US$175 million to develop the operation, according to Sierra Madre’s acquisition materials. The mine subsequently produced an average of approximately 2.54 million silver-equivalent ounces per year between 2015 and 2018.
Sierra Madre is not simply attempting to restart historical production at the same scale.
The company is doing more exploration and resource work. They are also looking at the best way to restart operations.
The property has a large exploration database and Sierra Madre found several mineralized zones for further study. That gives the asset two potential roles.
- First, it can provide a platform for restarting production.
- Second, exploration could potentially extend the mine’s future resource base.
Any future resource estimate, however, will need to be established through updated technical work. Historical estimates and past production figures should not be treated as current mineral resources or guarantees of future production.
Mexico’s Importance Goes Beyond Two Mines
Sierra Madre’s assets are only two examples within a much larger Mexican mining industry.
The country has extensive experience in underground mining, processing and silver production. It also has established mining districts, transportation networks, power infrastructure, and skilled labor.
That ecosystem matters when the global silver market needs additional production.
New greenfield mines will remain necessary over the long term, but the timeline from discovery to commercial production can be lengthy.
Brownfield expansions and restarts can potentially provide another route. The distinction is becoming more important because silver supply remains structurally constrained.
About three-quarters of silver produced worldwide comes from other metals. This means that higher silver prices can’t quickly boost primary silver production.
Mexico’s established silver assets therefore represent more than historical production. They form part of the existing physical infrastructure that can potentially be expanded, modernized or restarted.
A Mature Producer Still Has Room to Grow
Mexico’s 5% production decline in 2025 is a reminder that being the world’s largest silver producer does not make supply growth automatic. The country needs continued investment to maintain production from existing mines while developing the next generation of deposits.
That creates a balancing act.
Existing operations need additional exploration and capital to replace depleted reserves and maintain output. At the same time, past-producing assets can offer opportunities to add production without starting from an undeveloped site.
Sierra Madre’s strategy reflects both sides.
- At La Guitarra, the company is expanding a restarted operation and increasing processing capacity.
- Del Toro is considering restarting a former production site. They are also doing more exploration and technical work.
The two assets are at different stages. However, both show how established Mexican mining infrastructure is being revived or expanded.
The Next Mexican Silver Ounces May Already Have Infrastructure Behind Them
Mexico’s position in the silver market is unlikely to depend on a single new discovery. The country’s importance comes from the depth of its mining industry and the scale of its existing production base.
Its 172.9 million ounces of silver production in 2025 demonstrate the country’s enormous contribution to global supply. But the 5% decline from 2024 also shows why maintaining that position will require continued investment.
That is where established assets can become relevant.
La Guitarra is already producing and being expanded. Del Toro has a production history, extensive underground development, and a substantial processing facility.
Neither project guarantees future production, and both require continued capital and execution. But they illustrate a broader point about the next silver supply cycle.
When global mine production is struggling to grow, the industry’s response may not come only from newly discovered deposits.
Some of the next ounces could come from old mining districts, existing mills, past-producing mines, and brownfield expansions.
Mexico has more of that infrastructure than almost any other silver-producing country. And as the global silver market searches for additional supply, that existing foundation could make the country an important part of the next production cycle.
DISCLAIMER
New Era Publishing Inc. and/or CarbonCredits.com (“We” or “Us”) are not securities dealers or brokers, investment advisers, or financial advisers, and you should not rely on the information herein as investment advice. Sierra Madre Gold and Silver Ltd. (“Company”) made a one-time payment of $25,000 to provide marketing services for a term of one month. None of the owners, members, directors, or employees of New Era Publishing Inc. and/or CarbonCredits.com currently hold, or have any beneficial ownership in, any shares, stocks, or options of the companies mentioned.
This article is informational only and is solely for use by prospective investors in determining whether to seek additional information. It does not constitute an offer to sell or a solicitation of an offer to buy any securities. Examples that we provide of share price increases pertaining to a particular issuer from one referenced date to another represent arbitrarily chosen time periods and are no indication whatsoever of future stock prices for that issuer and are of no predictive value.
Our stock profiles are intended to highlight certain companies for your further investigation; they are not stock recommendations or an offer or sale of the referenced securities. The securities issued by the companies we profile should be considered high-risk; if you do invest despite these warnings, you may lose your entire investment. Please do your own research before investing, including reviewing the companies’ SEDAR+ and SEC filings, press releases, and risk disclosures.
It is our policy that information contained in this profile was provided by the company, extracted from SEDAR+ and SEC filings, company websites, and other publicly available sources. We believe the sources and information are accurate and reliable, but we cannot guarantee them.
CAUTIONARY STATEMENT AND FORWARD-LOOKING INFORMATION
Certain statements contained in this news release may constitute “forward-looking information” within the meaning of applicable securities laws. Forward-looking information generally can be identified by words such as “anticipate,” “expect,” “estimate,” “forecast,” “plan,” and similar expressions suggesting future outcomes or events. Forward-looking information is based on current expectations of management; however, it is subject to known and unknown risks, uncertainties, and other factors that may cause actual results to differ materially from those anticipated.
These factors include, without limitation, statements relating to the Company’s exploration and development plans, the potential of its mineral projects, financing activities, regulatory approvals, market conditions, and future objectives. Forward-looking information involves numerous risks and uncertainties and actual results might differ materially from results suggested in any forward-looking information. These risks and uncertainties include, among other things, market volatility, the state of financial markets for the Company’s securities, fluctuations in commodity prices, operational challenges, and changes in business plans.
Forward-looking information is based on several key expectations and assumptions, including, without limitation, that the Company will continue with its stated business objectives and will be able to raise additional capital as required. Although management of the Company has attempted to identify important factors that could cause actual results to differ materially, there may be other factors that cause results not to be as anticipated, estimated, or intended.
There can be no assurance that such forward-looking information will prove to be accurate, as actual results and future events could differ materially. Accordingly, readers should not place undue reliance on forward-looking information. Additional information about risks and uncertainties is contained in the Company’s management’s discussion and analysis and annual information form for the year ended December 31, 2025, copies of which are available on SEDAR+ at www.sedarplus.ca.
The forward-looking information contained herein is expressly qualified in its entirety by this cautionary statement. Forward-looking information reflects management’s current beliefs and is based on information currently available to the Company. The forward-looking information is made as of the date of this news release, and the Company assumes no obligation to update or revise such information to reflect new events or circumstances except as may be required by applicable law.
For more information on the Company, investors should review the Company’s continuous disclosure filings available on SEDAR+ at www.sedarplus.ca.
Disclosure: Owners, members, directors, and employees of carboncredits.com have/may have stock or option positions in any of the companies mentioned: None.
Carboncredits.com receives compensation for this publication and has a business relationship with any company whose stock(s) is/are mentioned in this article.
Additional disclosure: This communication serves the sole purpose of adding value to the research process and is for information only. Please do your own due diligence. Every investment in securities mentioned in publications of carboncredits.com involves risks that could lead to a total loss of the invested capital.