
Silver’s supply outlook is changing quickly.
After a physical shortage and a dramatic price rally in 2026, the silver market could enter surplus as early as 2027, Deutsche Bank says. Rising inventories, weaker industrial consumption and falling silver use in solar manufacturing are reducing pressure on the market.
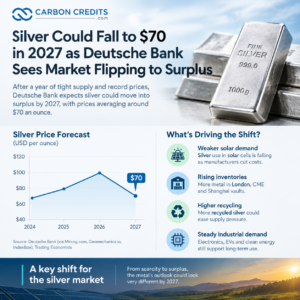
The bank’s outlook, reported by Mining.com, points to a very different silver market from the one investors saw at the start of this year. Deutsche Bank metals analyst Daniel Ghali expects silver prices to average around $70 an ounce in the second quarter of 2027.
The forecast comes as silver prices retreat from their 2026 highs.
Silver Price Pulls Back From Record High
Silver has experienced an unusually volatile year.
Trading Economics data show silver trading around $60.72 an ounce on October 7, down about 7.7% over the past month. However, the metal remains about 24% higher than a year ago. Silver reached an all-time high of $121.64 an ounce in January 2026.
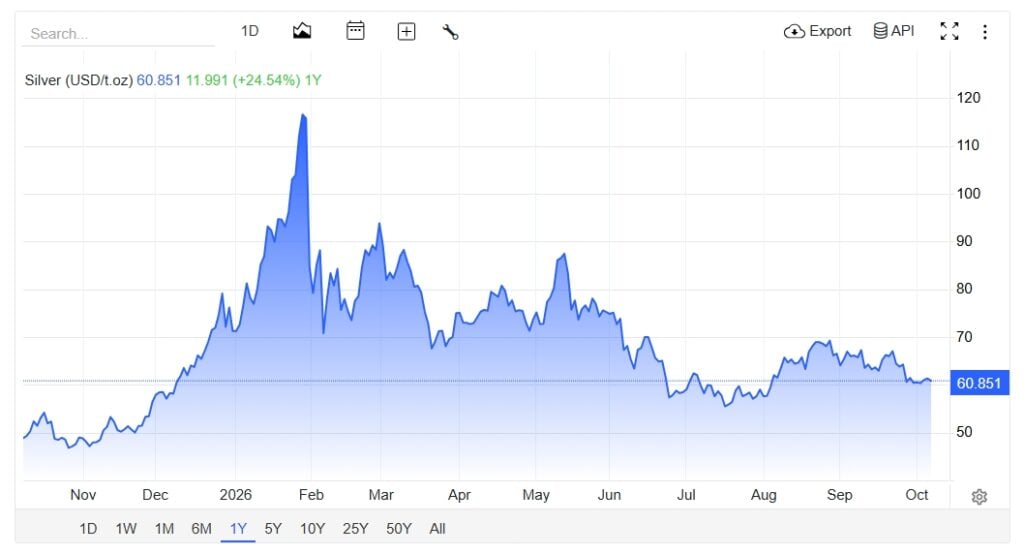
The decline reflects more than normal market volatility. Higher Treasury yields, a stronger U.S. dollar, and changing expectations for Federal Reserve policy have pressured precious metals.
But Deutsche Bank sees a more fundamental reason for potential weakness ahead: the silver market is becoming less physically constrained.
London commercial vaults held more than 914 million ounces of silver at the end of August, including more than 300 million ounces considered readily available. Deutsche Bank said readily available London stocks have increased about 70% since October 2025.
Inventories have also increased in CME warehouses and Shanghai. The bank attributes the buildup to higher recycling, the release of privately held metal, and weaker fabrication demand.
That growing inventory cushion could make another severe physical shortage less likely.
- ALSO READ: Silver in 2026 and Beyond: Rising Prices, Solar Substitution, and a Market Still in Deficit
Solar Industry Becomes the Biggest Demand Risk
The biggest change could come from the solar industry.
Silver plays an important role in solar cells because of its high electrical conductivity. But manufacturers are under growing pressure to reduce the amount of silver used in each cell as prices rise.
Deutsche Bank expects global silver consumption in solar applications to fall by more than 20% this year. Chinese solar demand could decline by about 33%.
Manufacturers are using thinner electrical contacts, copper-plated silver pastes and new cell designs that require less silver. The bank estimates silver use per solar cell will fall 17% in 2026.
High prices have strengthened that incentive.
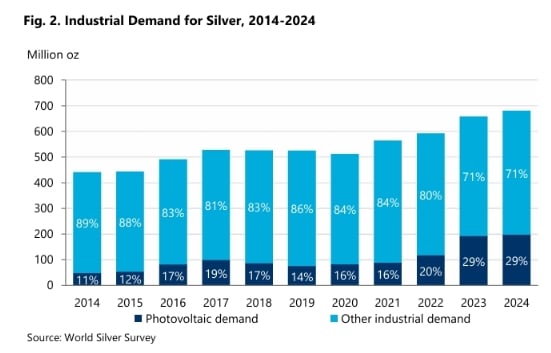
At one point in 2026, silver accounted for more than 30% of solar-module production costs, compared with less than 10% at the beginning of 2025. That share has since fallen to roughly 14%, but the cost remains high enough to encourage further material savings and substitution.
This creates an important paradox for the energy transition. Solar deployment can keep growing rapidly while the amount of silver required per panel falls.
Silver Demand Is Not Disappearing
A weaker solar market for silver does not mean industrial demand will collapse.
Silver remains widely used in electronics, electrical equipment, medical technologies and other industrial applications. Electrification, data infrastructure and renewable energy continue to support demand for the metal.
Recycling could also become a more important source of supply.
A recent Reuters analysis highlighted improvements in solar-panel recycling, including technologies capable of recovering silver at very high rates. Rystad Energy estimates that recycled panels could supply as much as 21% of the silver needed for solar-panel production by 2035.
That could further reduce the solar sector’s dependence on newly mined silver over time.
Investment Demand Could Decide Silver’s Next Move
With physical scarcity easing, investment demand may become even more important for prices.
Deutsche Bank estimates silver-backed investment funds could potentially release around 40 million ounces by the end of 2027 if investors respond to interest-rate conditions in a way similar to previous Federal Reserve tightening cycles.
India also presents a weaker demand signal. The bank estimates the country’s silver imports are about 25% below last year’s levels following higher import duties and purchasing restrictions. Chinese demand remains a wild card, however, because silver continues to trade at a premium in China despite rising inventories.
- Trading Economics currently expects silver to average around $63.60 by the end of the quarter and reach about $74.56 over the next 12 months, showing that the broader market does not necessarily expect prices to collapse even as physical tightness eases.
The key difference is that silver may no longer need extreme scarcity to support its price.
What a Silver Surplus Means for the Energy Transition
A move from shortage to surplus would give manufacturers more breathing room, but it could also change the economics for silver miners.
If solar companies continue reducing silver intensity while recycling expands, future demand growth may not translate directly into higher primary silver consumption.
For investors, the story is therefore shifting from simply finding more silver to understanding where demand will come from.
Deutsche Bank’s forecast does not guarantee a surplus. Stronger Chinese demand, renewed investment buying, supply disruptions or another wave of precious-metals demand could quickly tighten the market again.
For now, however, the silver story is changing. A metal that started 2026 at the center of a supply squeeze could enter 2027 with rising inventories, more recycling and a solar industry determined to use less of it.
The next phase of the silver market may be less about scarcity and more about how quickly manufacturers can adapt.