CORSIA Could Face a 125 Million Carbon Credit Gap Before 2028, Says Sylvera

The global aviation industry’s main carbon offset program is at a key point. With less than two years until airlines meet their first CORSIA obligations, a new report from Sylvera warns of a potential supply shortage. This could lead to higher carbon prices and increased compliance risks.

CORSIA, launched by the International Civil Aviation Organization (ICAO), is the first global market-based plan for aviation emissions. Airlines must offset emissions from international flights that exceed 85% of 2019 levels. The first phase, from 2024 to 2026, addresses current emissions. However, airlines won’t need to retire eligible carbon credits until January 31, 2028.

Sylvera thinks airlines may be underestimating the challenges ahead, even if the deadline feels distant

CORSIA Demand Is Rising, But Eligible Supply Remains Scarce

By 2026, 130 countries will join CORSIA, one of the world’s largest carbon compliance systems.

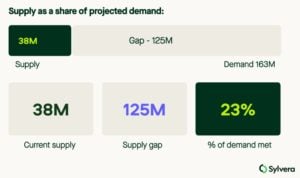
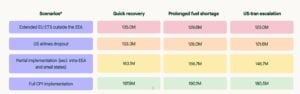
Sylvera estimates that CORSIA’s first compliance phase could create demand for about 163 million eligible emissions units (EEUs). This excludes intra-European Economic Area flights already covered by the EU Emissions Trading System and smaller aviation markets. Demand could rise to 198 million credits under full implementation.

The challenge is that eligible supply is well below these numbers.

Currently, only 38 million carbon credits qualify as EEUs, covering just 23% of expected demand. Around 300 million credits have been issued, but many are stuck due to extra authorization requirements.

  • This situation leaves a supply gap of about 125 million credits.
CORSIA carbon credit
Source: Sylvera

The shortage comes from two main hurdles in Article 6 of the Paris Agreement: Host-country Letters of Authorization (LoAs) and Corresponding Adjustments (CAs) or approved insurance mechanisms. Without these approvals, carbon credits can’t be used for CORSIA compliance, even if issued.

The Article 6 Bottleneck Is Slowing the Market

Article 6 rules have changed how carbon credits are used in international markets.

Host countries must formally authorize credits for international use and adjust their emissions accounting to avoid double counting. While this strengthens environmental integrity, it creates a significant administrative bottleneck.

Sylvera reports that only 24 countries have issued LoAs, and just five have reported corresponding adjustments. The company estimates that only 21% of assessed countries are likely to meet both requirements.

Even with optimistic views, the outlook remains tight.

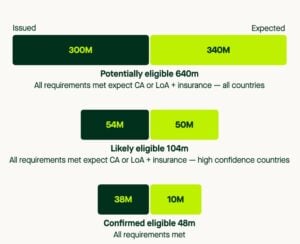
By January 2028, potentially eligible credit volumes could reach 640 million. But considering authorization risks, likely eligible supply drops to around 104 million credits. Fully confirmed eligible supply is only about 48 million credits.

This gap makes many analysts view authorization risk as a key factor in carbon markets today.

Airlines Are Waiting—But Waiting May Become Expensive

One striking finding is the low level of buying activity. Despite airlines facing compliance obligations for 2024-2026, only around 400,000 tonnes of CORSIA credits have been retired—about 0.2% of expected demand.

Many airlines are waiting for clearer signals from regulators before spending money.

However, Sylvera warns that delaying credit purchases could lead to a supply squeeze. If airlines wait until 2027 or early 2028, liquidity might dry up just as demand peaks.
This situation echoes concerns from market intelligence firm Abatable, which has warned that CORSIA demand could exceed available supply in its second phase if new projects don’t enter the market.

Several Factors Could Reduce Demand

While supply issues dominate discussions, demand is also uncertain. Sylvera identifies three key factors that could lower total compliance needs.

1. Geopolitical Tensions

The report notes that ongoing disruptions from the US-Iran conflict could cut international aviation activity. This may reduce CORSIA demand by 4% to 9%. Depending on how long these disruptions last, demand could fall to between 149 million and 157 million credits.

2. Europe’s CORSIA Review

The European Commission is reviewing how CORSIA interacts with the EU ETS.

If flights from the European Economic Area shift entirely to the EU ETS, CORSIA demand could drop by about 24%, lowering it to around 123 million credits.

This review is crucial because Europe is a major source of compliance demand. Market players worry that new EU eligibility rules could shrink the pool of acceptable credits.

3. US Airline Participation

While the US is part of CORSIA, domestic enforcement remains unclear.

Sylvera estimates that if major US airlines opt out of full participation, demand could fall by roughly 18%.

Still, some airlines in Asia may continue to buy credits voluntarily. Japan Airlines, All Nippon Airways, Singapore Airlines, and Scoot have already retired credits for future compliance.
corsia
Source: Sylvera

Carbon Credit Prices Could More Than Triple

The uncertainty around supply and demand complicates price forecasting.

Currently, CORSIA markets are thinly traded with limited transaction data. However, Sylvera’s models across 50 scenarios suggest significant upside risk.

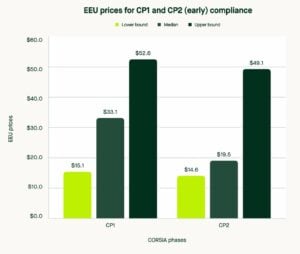
The firm projects three possible outcomes for first-phase compliance credits:

  • Low case: about $15 per credit
  • Base case: about $33 per credit
  • High case: approximately $53 per credit by January 2028

The highest-price scenario assumes ongoing authorization bottlenecks, limited supply growth, and a late rush in airline buying. If this occurs, compliance costs could rise sharply for the aviation sector.
corsia prices
Source: Sylvera

Billions of Dollars Are at Stake

The financial stakes are certainly high. Sylvera estimates total airline exposure at around $2.4 billion under a $15-per-credit scenario. If credits hit $53, costs could soar. The top ten airlines alone might face about $3.8 billion in procurement costs.

Since compliance obligations are based on past flight activity, airlines have few options to lower their exposure. Their main strategy is timing—when and how they secure credits.

The Road to 2028

Despite uncertainties, most market observers expect CORSIA to succeed.

Countries continue to develop Article 6 frameworks. Authorization systems are improving, and governments increasingly see the economic value of joining international carbon markets.

However, the next 18 months may determine if CORSIA becomes a smooth compliance market or faces a supply crunch that drives prices higher.

For airlines, project developers, and investors, Sylvera’s message is clear: the compliance deadline may be in 2028, but today’s market is already taking shape.

Xpansiv and BEClimate Launch Platform to Turn Building Upgrades Into Carbon Credits

Buildings are one of the world’s biggest sources of greenhouse gas emissions. But many projects that could cut those emissions never get built because they lack funding. A new partnership hopes to change that. BEClimate has launched the BEVerify registry with Xpansiv and Quidos to connect building decarbonization projects with carbon markets.

The platform uses digital monitoring to turn verified emissions cuts into carbon assets. This can help schools, hospitals, offices, homes, and public buildings attract new investment. The launch also signals a bigger shift. Carbon markets are expanding beyond forests and renewable energy into the buildings where people live and work.

Buildings Produce More Than One-Third of Energy-Related Emissions

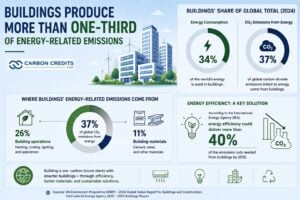
Buildings play a major role in global emissions. In 2024, buildings consumed about 34% of the world’s energy. They also produced 37% of global carbon dioxide emissions linked to energy, according to the UN Environment Programme (UNEP) and the Global Alliance for Buildings and Construction.

Building operations, such as heating, cooling, lighting, and appliances, accounted for about 26% of those emissions. Building materials like cement and steel added another 11%.

buildings ghg emissions 2024

The sector is still moving too slowly. UNEP says emissions from buildings remain above pre-pandemic levels and the industry is not on track to meet global climate goals.

The challenge is clear. The World Green Building Council estimates that 80% of the buildings that will exist in 2050 have already been built. This means countries must upgrade existing buildings, not just build new green ones. 

The Missing Piece Is Financing

The good news is that the technology already exists. Heat pumps, better insulation, rooftop solar, efficient lighting, and smart energy controls can greatly reduce energy use.

According to the International Energy Agency (IEA), energy efficiency could deliver more than 40% of the emissions cuts needed from buildings by 2030.

The biggest barrier is funding.

Many retrofit projects need large upfront investments. The savings from lower energy bills often take years to recover those costs. Because of this, many schools, hospitals, offices, and public buildings delay or cancel energy upgrades.

BEClimate believes carbon finance can help fill this gap. Its new BEVerify registry turns verified emissions reductions into carbon assets. This gives building owners another way to earn revenue, making more projects financially viable.

Digital Monitoring Could Transform Carbon Verification

BEVerify also aims to solve another long-standing problem: slow verification.

Many carbon projects take months before credits can be verified and issued. BEVerify uses digital Measurement, Reporting, and Verification (dMRV) to monitor building performance in real time.

The company says it has already reduced the process from months to just minutes. Every emissions reduction is supported by a full digital audit trail, making the system faster and easier to verify.

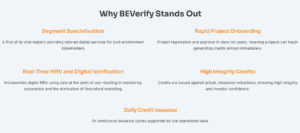
BEVerify benefits
Source: BEVErify

The registry runs on Xpansiv’s cloud-based market platform. It is designed to support future compliance programs, including Article 6, CORSIA, and carbon tax systems. This gives project developers a clearer path into both voluntary and compliance carbon markets.

If the model succeeds, it could unlock new investment for millions of buildings that have long been left out of carbon markets. That would help speed up emissions cuts while making building upgrades easier to finance.

Carbon Markets Move Into the Built Environment

For years, most carbon credits came from projects such as forest conservation, reforestation, renewable energy, and methane capture. Now the market is starting to expand into new sectors, including buildings.

This shift comes as buyers look for more ways to support verified emissions reductions. At the same time, governments are strengthening climate policies and raising expectations for corporate climate action.

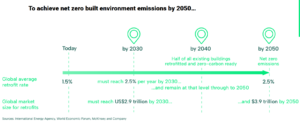
The opportunity is significant. The World Green Building Council says buildings must reduce operational emissions by 50% by 2030. They also need to achieve net zero by 2050 to meet global climate goals. Reaching those targets will require trillions of dollars in investment, $2.9 trillion in 2030 and $3.9 trillion in 2050, and much of it for upgrading existing buildings.

built environment net zero 2050
Source: World Green Building Council

Carbon finance could help close part of that funding gap. A new revenue source can make retrofit projects more appealing for private and public building owners.

Digital Registries Are Reshaping Carbon Markets

The launch of BEVerify also reflects a broader shift toward digital carbon markets.

Project developers are shifting from manual reporting to digital systems. These systems offer near real-time data. This improves transparency and lowers the cost of verification.

Digital monitoring is becoming more important as carbon markets grow. New compliance systems under Article 6 of the Paris Agreement, the aviation sector’s CORSIA program, and national carbon pricing policies all require accurate and traceable emissions data.

This is where platforms like Xpansiv can play a bigger role. The company runs one of the largest environmental trading platforms worldwide. It supports transactions for carbon credits, renewable energy certificates, and other eco-friendly commodities.

  • Connecting digital monitoring with digital registries can make carbon markets faster, more transparent, and easier to scale.

Buildings Could Become the Next Big Source of Carbon Credits

Buildings remain one of the world’s largest untapped sources of carbon reductions. Many schools, hospitals, offices, apartment buildings, and public facilities can cut emissions by:

  • improving insulation,
  • using cleaner heating systems,
  • installing efficient lighting,
  • adding rooftop solar, and
  • implementing smart energy controls.

Many of these projects already make technical sense but struggle to secure funding.

BEVerify offers a different approach. Instead of relying only on lower energy bills, building owners may also be able to generate value from verified emissions reductions. That extra income could help more projects move from planning to construction.

For buyers, the platform provides access to carbon reductions backed by measured building performance rather than estimates. This can increase confidence as demand grows for high-integrity carbon assets.

A New Financing Model for Greener Buildings

The launch of BEVerify is about more than a new carbon registry. Carbon finance is starting to help sectors that receive less focus than forestry or renewable energy.

As countries work toward net-zero emissions, upgrading existing buildings will become one of the biggest climate challenges. Meeting that challenge will require new sources of capital alongside better technology.

By combining digital monitoring, faster verification, and carbon market infrastructure, BEClimate and Xpansiv are testing a model that could unlock investment on a much larger scale.

If it succeeds, carbon markets may no longer be limited to forests and industrial projects. They could also help finance cleaner schools, hospitals, offices, and homes—bringing building decarbonization into the next phase of climate action.

Google and McKinsey Secure Future Carbon Credits From Indonesia Through the Symbiosis Coalition

Global companies are changing how they buy carbon credits. Instead of waiting for credits to become available, they are investing years in advance to help new projects get started. The latest example comes from Indonesia, where Google, McKinsey & Company, and Tencent have agreed to buy a combined 635,000 tonnes of nature-based carbon removal from Thryve.Earth over the next 10 years.

The deal will help restore forests in Sulawesi while giving the project the funding it needs to grow. It also shows how demand is shifting toward high-quality carbon removal projects that deliver real climate and community benefits.

Advance Carbon Deals Are Funding Tomorrow’s Climate Projects

The agreements are supported by the Symbiosis Coalition, a group formed by Google, Meta, Microsoft, and Salesforce in 2024. The coalition plans to buy up to 20 million tonnes of high-quality nature-based carbon removal by 2030. It is one of the largest buying efforts of its kind. 

Under the new agreements, Google and McKinsey will buy more than 335,000 tonnes of carbon removal over 10 years, 260,000 of which is from Google. Tencent will buy another 300,000 tonnes during the same period. The deal is Tencent’s first carbon removal purchase outside of China.

The tech giant noted:

“Together with Symbiosis, we’re continuing to catalyze the highest-scale opportunities to restore natural ecosystems worldwide. It’s one element of our broader climate solutions portfolio, which also includes other breakthrough carbon removal projects and efforts to eliminate superpollutants.”

Randy Spock, Head of Carbon Removal at Google, stated in a post that it is the company’s largest carbon removal purchase so far. He further said that the project stands out for three main reasons:

  • It restores degraded land,
  • It supports local communities, and
  • It is designed to last.

These are forward-offtake agreements. That means the companies are buying future carbon removals instead of credits that already exist. Their long-term commitments give Thryve.Earth the confidence to raise funding and begin restoring land today.

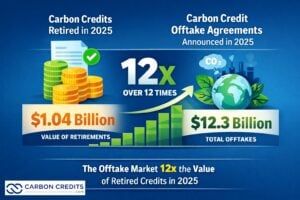
Carbon credit offtake infographic

This model is becoming more common across the carbon market. Companies aim to ensure future supplies of high-quality carbon removals. They also want to help developers scale up projects.

Restoring Forests and Farms in Sulawesi

The project will restore about 6,000 hectares of degraded land in Sulawesi, one of Indonesia’s most important forest regions.

Instead of planting only one type of tree, Thryve.Earth will create an agroforestry system with several layers of crops and trees. Sugar palm and timber trees will form the upper canopy. Crops such as coffee, avocado, bananas, papaya, chili, and corn will grow underneath.

This approach removes carbon from the air while improving soil health, lowering wildfire risk, and increasing biodiversity. It also gives farmers several sources of income throughout the year instead of relying on a single crop.

thryve.earth sulawesi indonesia carbon project
Source: Thryve.earth

Indonesia is well-suited for projects like this. The Food and Agriculture Organization (FAO) states that the country has around 92 million hectares of forest. This makes it one of the largest tropical forest nations in the world.

Ron Steinherz, Co-Founder and COO of Thryve.Earth, said:

“Turning degraded grassland back into productive forest is, above all, an operational challenge. By pairing high-quality saplings and rigorous field protocols with verifiable monitoring of every hectare, we give our partners confidence that the carbon removals and community benefits are real, measurable, and built to last.”

Thryve says the agroforestry model could grow to cover 250,000 hectares of degraded land in Indonesia and other Southeast Asian areas. That would greatly increase the region’s carbon removal potential.

Demand for Trusted Carbon Removals Is Outpacing Supply

The Sulawesi project also reflects a bigger trend in the carbon market. More companies are looking for carbon removal credits instead of traditional avoidance credits.

Carbon removal projects take carbon dioxide out of the atmosphere, making them an important tool for reaching net-zero goals.

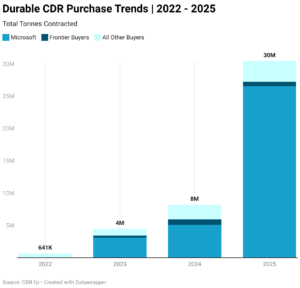
According to CDR.fyi, companies contracted more than 8 million tonnes of carbon dioxide removal in 2025, another record for the market. Nature-based projects still dominate purchases. They can be deployed on a larger scale and at a lower cost than engineered carbon removal.

durable cdr contracted 2025

Demand is also growing faster than supply. During its first global project search, the Symbiosis Coalition received 185 proposals from 40 countries. Those projects covered around 6.6 million hectares. They could remove over 180 million tonnes of carbon dioxide in the next ten years. However, only a small share met the coalition’s strict quality standards.

That gap shows why advance purchase agreements are becoming more important. They help finance the projects that buyers want, while increasing the future supply of trusted carbon removal credits.

Indonesia Is Emerging as a Carbon Removal Leader

Indonesia is becoming one of the world’s top markets for nature-based carbon removal.

The country has the third-largest area of tropical rainforest and about 14 million hectares of degraded land that could be restored, according to the World Bank. Restoring these landscapes can remove carbon, improve biodiversity, and strengthen rural livelihoods.

Nature-based solutions are also central to Indonesia’s climate strategy. Under its updated Nationally Determined Contribution (NDC), the country aims to cut greenhouse gas emissions by 31.89% on its own by 2030, or by 43.2% with international support. Forest protection and land restoration are expected to deliver much of these emissions cuts.

Projects like Thryve.Earth can help achieve these goals by bringing private investment into large-scale restoration while creating jobs and supporting local farmers.

Buyers Want Better Carbon Credits

The voluntary carbon market is also changing. Companies are getting more selective. They want carbon credits supported by solid science, dependable monitoring, and clear environmental and social benefits. This follows new guidance from various bodies:

  • The Integrity Council for the Voluntary Carbon Market (ICVCM),
  • The Voluntary Carbon Markets Integrity Initiative (VCMI), and
  • The Science-Based Targets initiative (SBTi).

Demand for nature-based projects remains strong. According to MSCI, they accounted for about 37% of all voluntary carbon credit retirements in 2024, making them the market’s largest project type.

carbon credit retirements msci
Source: MSCI

Long-Term Offtakes Could Shape the Next Carbon Market

Forward purchase agreements are becoming an important way to finance carbon removal.

Companies commit to buying future carbon removals instead of buying credits after projects are done. These long-term agreements give developers the confidence to restore land, attract investors, and expand projects.

Companies are signing record numbers of forward carbon removal agreements, CDR.fyi says. This is happening as competition increases for a limited supply of high-quality credits.

For communities, the benefits go beyond carbon. The Sulawesi project will create jobs and improve soil health. It will also reduce wildfire risk, boost biodiversity, and give farmers income from fruit, timber, and food crops. These added benefits help ensure the restored landscapes remain productive over the long term.

A New Model for Scaling Carbon Removal

The Thryve.Earth agreements represent more than 635,000 tonnes of future carbon removal. They show how the carbon market is evolving.

Large companies are moving beyond one-time carbon credit purchases and helping finance projects before they begin. This gives developers the certainty needed to scale restoration while securing future carbon removals for buyers.

Companies aiming for net-zero goals will likely see more investment in projects that merge carbon removal, protect biodiversity, and benefit communities. The latest commitments from Google, McKinsey, Tencent, and the Symbiosis Coalition suggest this shift is already underway.

Canada and Saudi Arabia Sign $1 Billion in Deals to Boost Clean Energy, Mining, and AI Partnership

Canada and Saudi Arabia have entered a new phase in their bilateral relationship, signing more than C$1 billion (US$730 million) worth of commercial agreements and launching new partnerships in clean energy, mining, artificial intelligence (AI), infrastructure, and investment.

The announcements came during Prime Minister Mark Carney’s official visit to Saudi Arabia—the first by a Canadian prime minister in 26 years—as both countries seek to diversify their economies and strengthen cooperation in industries driving the global energy transition.

The visit produced new government agreements on energy and AI, alongside 13 commercial deals involving Canadian and Saudi companies. Together, these initiatives could create fresh opportunities for Canadian firms while supporting Saudi Arabia’s ambitious Vision 2030 economic transformation.

Mark Carney noted:

“Canada and Saudi Arabia have both embarked on ambitious new missions to transform their economies. To that end, we are harnessing each other’s strengths across minerals and mining, technology, energy, and commerce. Canada has what the world wants. We are cultivating a dense web of new connections to diversify our trade, create new opportunities for our workers and businesses, and deliver greater security and prosperity for all Canadians.”

A New Chapter in Canada-Saudi Relations

Meeting in Jeddah, Prime Minister Carney and Crown Prince Mohammed bin Salman agreed to deepen cooperation across trade, investment, defence, education, science, and technology.

One of the key outcomes was the signing of a memorandum of understanding (MOU) establishing the Canada–Saudi Arabia Coordination Council, a new platform that will oversee bilateral cooperation across strategic sectors.

The visit also reflected Canada’s broader effort to diversify exports beyond the United States while attracting new foreign investment. Carney has repeatedly emphasized the need to build stronger partnerships with fast-growing economies as global trade patterns shift.

Energy Cooperation Expands Beyond Oil

Clean energy emerged as one of the biggest winners from the visit. Canada and Saudi Arabia signed a new energy MOU aimed at attracting investment and expanding cooperation in:

  • Liquefied natural gas (LNG)
  • Renewable energy
  • Hydrogen
  • Carbon capture and storage (CCS)

The agreement seeks to combine Canada’s expertise in clean technologies and energy infrastructure with Saudi Arabia’s massive investments in low-carbon energy.

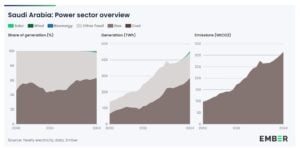
Saudi Arabia remains one of the world’s largest oil producers, but the kingdom is investing heavily to diversify its energy mix. According to Ember data, it generates 2% of its electricity from low-carbon sources.

Saudi Arabia energy

  • However, under Vision 2030, it aims for 50% of electricity generation to come from renewable energy by 2030, with the remaining half supplied by natural gas.
  • The government is targeting around 130 gigawatts (GW) of renewable energy capacity by the end of the decade through large-scale solar and wind projects.

The kingdom is also positioning itself as a future exporter of clean hydrogen while expanding carbon capture capacity to reduce industrial emissions.

These goals require significant international investment, engineering expertise, and technology—areas where Canadian companies have decades of experience.

Rising Electricity Demand Drives Investment

Saudi Arabia’s clean energy push is also being driven by rapidly rising electricity demand.

Population growth, industrial expansion, desalination plants, new manufacturing facilities, and mega-projects such as NEOM, The Line, and other Vision 2030 developments are increasing pressure on the country’s power system.

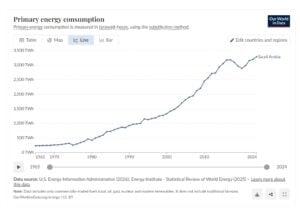
  • Peak electricity demand has already surpassed 90 GW, and energy consumption is expected to continue rising throughout the next decade.

energy cpnsumption saudi arabia

To meet this demand while reducing emissions, Saudi Arabia is rapidly expanding utility-scale solar and wind generation, battery storage, smart grids, and energy efficiency programs.

The country has already awarded dozens of renewable energy projects through its National Renewable Energy Program, making it one of the fastest-growing clean energy markets in the Middle East.

For Canadian developers, equipment suppliers, engineering firms, and clean technology companies, this represents a significant long-term opportunity.

AI Partnership Strengthens

Artificial intelligence was another major focus of the visit. The two governments signed an MOU to increase collaboration on AI development, deployment, commercialization, and innovation.

The announcement was accompanied by a landmark private-sector agreement between Canadian AI company Cohere and Saudi Arabia’s HUMAIN.

  • Under the partnership, HUMAIN will dedicate at least 50 megawatts of AI computing capacity to support Cohere’s next generation of foundation models.

The collaboration aims to develop sovereign AI capabilities while strengthening advanced computing infrastructure in Saudi Arabia.

Meanwhile, Canadian cybersecurity company BlackBerry and Aramco Digital also announced discussions to explore secure communications technologies and industrial digital solutions.

These partnerships align with Saudi Arabia’s broader ambition to become a regional leader in AI and digital infrastructure while creating new export opportunities for Canadian technology firms.

Mining Becomes a Strategic Priority

Mining also featured prominently during the visit. Among the 13 commercial agreements are partnerships that will enable Canadian companies to support Saudi Arabia’s growing mining and critical-minerals sector.

Saudi Arabia has identified mining as the third pillar of its economy, after oil and petrochemicals. The kingdom estimates its untapped mineral resources—including gold, phosphate, copper, lithium, rare earth elements, zinc, and other critical minerals—are worth approximately US$2.5 trillion.

Developing these resources is considered essential for both economic diversification and the global clean energy transition.

Canada brings significant expertise to that effort.

According to Natural Resources Canada, the country’s mining and mineral processing industry contributed approximately C$117 billion to Canada’s GDP in 2024, representing nearly 5% of the national economy.

Canada is also among the world’s leading producers of:

  • Potash
  • Uranium
  • Nickel
  • Cobalt
  • Aluminum
  • Gold
  • Diamonds

Many of these minerals play a critical role in manufacturing batteries, electric vehicles, renewable energy equipment, and advanced electronics.

Canadian mining companies are internationally recognized for exploration, engineering, environmental management, financing, and mine development—expertise that Saudi Arabia is seeking as it expands its domestic mining industry.

canaada mining

More Than Commercial Deals

Beyond mining and energy, the agreements cover infrastructure, healthcare, education, and defence.

Canadian infrastructure companies are expected to participate in transportation projects supporting Vision 2030, including roads and railway developments.

Healthcare partnerships will introduce Canadian technologies ranging from patient monitoring systems to surgical intelligence platforms.

Educational institutions will also help train Saudi workers in skilled trades, engineering, healthcare, construction, and technology.

Together, these initiatives are designed to create long-term economic cooperation rather than increase exports.

Investment Ties Continue to Grow

The visit also laid the foundation for deeper investment flows.

Canada announced plans to lead a delegation of major pension funds to Saudi Arabia to explore investment opportunities, particularly in clean energy and AI. The two countries also agreed to conclude negotiations on a Foreign Investment Promotion and Protection Agreement (FIPA) by early 2027.

In addition, negotiations have begun on a new double taxation agreement that would simplify cross-border investment for businesses operating in both countries.

Canada also confirmed it will participate in Expo 2030 Riyadh, where Canadian companies will showcase technologies in clean energy, mining, advanced manufacturing, and digital innovation.

A Partnership Built Around the Energy Transition

Although Saudi Arabia remains one of the world’s largest oil exporters, its economic transformation is creating new opportunities in renewable energy, hydrogen, carbon capture, AI, and critical minerals.

Canada, meanwhile, possesses strengths in clean technology, sustainable mining, engineering, and advanced research.

By combining those capabilities, both countries hope to unlock new investment, diversify trade, and accelerate projects supporting the global transition to lower-carbon energy.

With more than C$1 billion in new commercial agreements already announced and broader investment negotiations underway, the partnership signals that clean energy, critical minerals, and advanced technologies are becoming central pillars of Canada–Saudi Arabia economic relations.

Microsoft’s Emissions Rise 25% in 2025 as AI Expansion Tests Its Net-Zero Goals

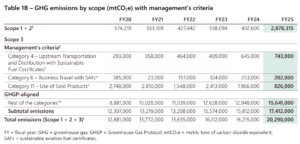
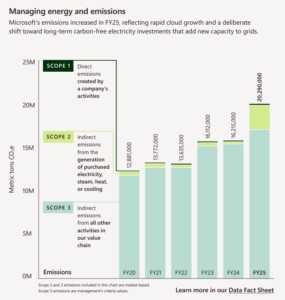
Artificial intelligence is fueling Microsoft’s next phase of growth, but it is also increasing the company’s carbon footprint. Microsoft’s 2026 Environmental Sustainability Report reveals that its total greenhouse gas (GHG) emissions hit almost 20.3 million metric tons of CO₂ equivalent (MtCO₂e) in fiscal year 2025. This is an increase from 16.2 MtCO₂e in 2024. That is a 25% increase in just one year.

The company says the increase shows how quickly AI and cloud infrastructure are growing. This is especially true with the building of new data centers. Microsoft still aims to be carbon negative by 2030. It also plans to remove all the carbon it has emitted since 1975 by 2050.

AI Infrastructure Is Driving Microsoft’s Emissions

Microsoft’s report shows that Scope 3 emissions remain its biggest climate challenge. These indirect emissions made up 85.82% of the company’s total carbon footprint in 2025.

The largest source was capital goods, which accounted for 44.57% of total emissions. This includes the steel, cement, servers, semiconductors, cooling systems, and other equipment needed to build AI data centers.

Purchased goods and services contributed 25.28%. Fuel and energy activities added 5.30%. Upstream transportation accounted for 3.66%.

Microsoft emissions by scope 2025
Source: Microsoft Report

The company says demand for AI services such as Azure and Copilot is driving a wave of global infrastructure investment. Building these facilities causes a lot of emissions even before they start. This is because making cement, steel, and computer chips uses a lot of carbon.

Another change came from Microsoft’s electricity strategy. Scope 2 emissions increased to about 13% of total emissions, compared with around 2% a year earlier.

The tech giant said this reflects a shift away from buying renewable energy certificates that do not add new clean power to the grid. Instead, Microsoft is investing in new carbon-free electricity projects that deliver a greater long-term climate benefit.

The Increase Is Part of a Long-Term Transition

Microsoft argues that today’s higher emissions are linked to building tomorrow’s lower-carbon economy. The company stated: 

“Our results reflect both progress and pressure. As we scale the physical infrastructure required to power the AI economy, our emissions are shaped by the impact of that growth and the actions we are taking to manage it.”

Microsoft ghg emissions 2025
Source: Microsoft

The company expects emissions from construction and supply chains to decrease over time. This will happen as suppliers use cleaner manufacturing, low-carbon materials become more available, and electricity grids add more renewable power.

The wider industry faces the same challenge. The International Energy Agency (IEA) says that electricity demand from data centers will more than double by 2030. This surge is due to the faster adoption of AI. Manufacturing steel, cement, and electronic equipment for these facilities also causes a lot of global industrial emissions.

Microsoft says it is working directly with suppliers to lower those emissions. The company is testing green steel, lower-carbon concrete, and hybrid mass timber. These materials can cut the embodied carbon in some data centers by up to 35%. It is also using new steel products that can cut emissions by as much as 95% compared with conventional steel production.

Microsoft Doubles Down on Climate Action

Even as its emissions rise, Microsoft continues to expand one of the world’s largest corporate climate programs.

The company remains committed to becoming carbon negative by 2030. In fiscal year 2025, it contracted projects to remove over 45 million metric tons of carbon. This includes 29 projects across five continents and 10 carbon removal pathways. These include:

  • direct air capture (DAC),
  • biochar,
  • enhanced rock weathering,
  • reforestation, and
  • bioenergy with carbon capture and storage (BECCS).

Microsoft also reported progress beyond carbon. It achieved a 92% reuse and recycling rate for cloud servers and components for the second year in a row, exceeding its 90% target. The company also became water positive during the year by replenishing more water than it consumed.

These results highlight the challenge many technology companies now face. AI is increasing emissions in the short term because of massive infrastructure investments. Companies are putting billions into clean energy, carbon removal, and lower-carbon supply chains. This investment helps them meet their long-term climate goals.

Renewables and Carbon Removal Expand at Record Pace

Microsoft is backing its climate goals with large investments.

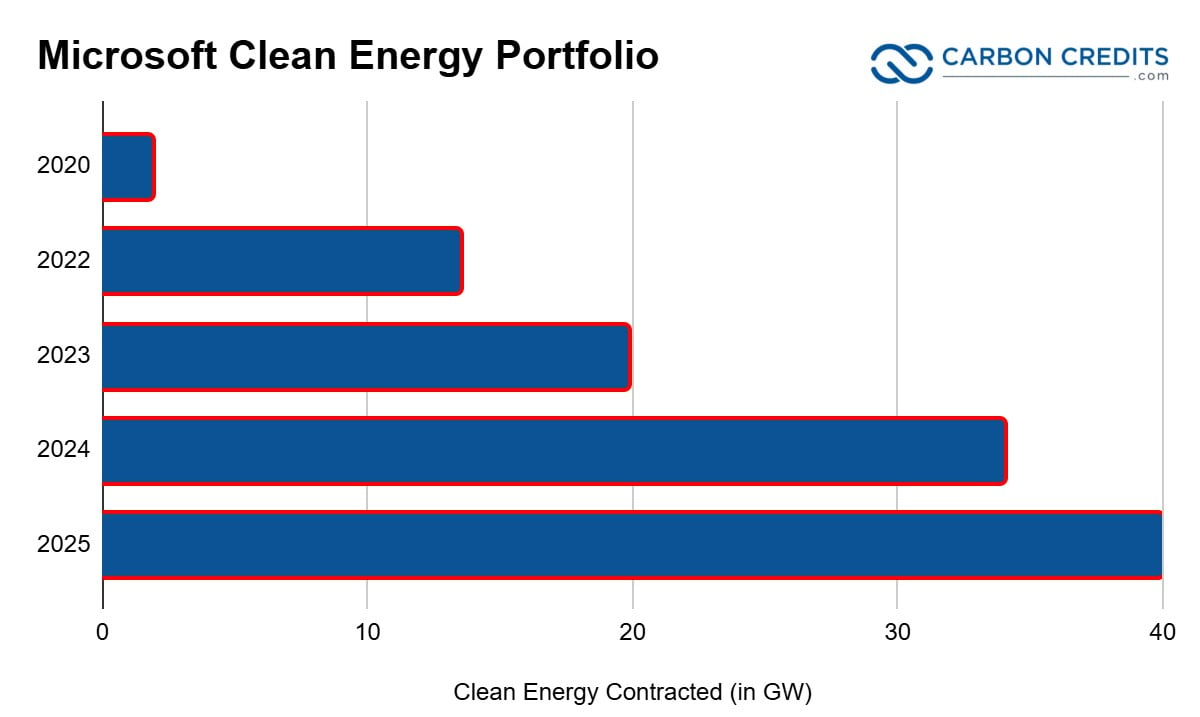
The company now has more than 40 gigawatts (GW) of contracted renewable energy across 26 countries. This portfolio includes solar, wind, and other clean power projects that help reduce emissions from its operations while supporting cleaner electricity grids.

Microsoft clean energy portfolio

Carbon removal is another key part of its strategy. According to CDR.fyi, Microsoft remains the world’s largest corporate buyer of carbon removal. Its growing portfolio features nature-based projects and engineered solutions. These include direct DAC and BECCS.

The company says it is also working with suppliers to cut emissions before products reach its data centers. Microsoft encourages manufacturers to use renewable electricity through its Supplier Code of Conduct and sustainability programs. They also promote better energy efficiency and lower-carbon materials.

Can AI Help Cut Future Emissions?

Although AI is increasing emissions today, Microsoft believes the technology can also help reduce emissions across the global economy.

The company is creating AI tools for various purposes. These tools will improve energy management, optimize power grids, and monitor forests. They will also reduce industrial waste and help businesses track their carbon footprints. These applications could lower emissions in sectors such as manufacturing, agriculture, transportation, and buildings.

The IEA shares a similar view. It says AI can improve the efficiency of electricity systems, speed up renewable energy integration, and support better energy planning. These benefits depend on how fast electricity grids clean up and how well future data centers run.

This means the climate impact of AI will depend not only on better software, but also on cleaner power, stronger supply chains, and continued investment in low-carbon infrastructure.

Investors Focus on Growth Amid Emissions Increase

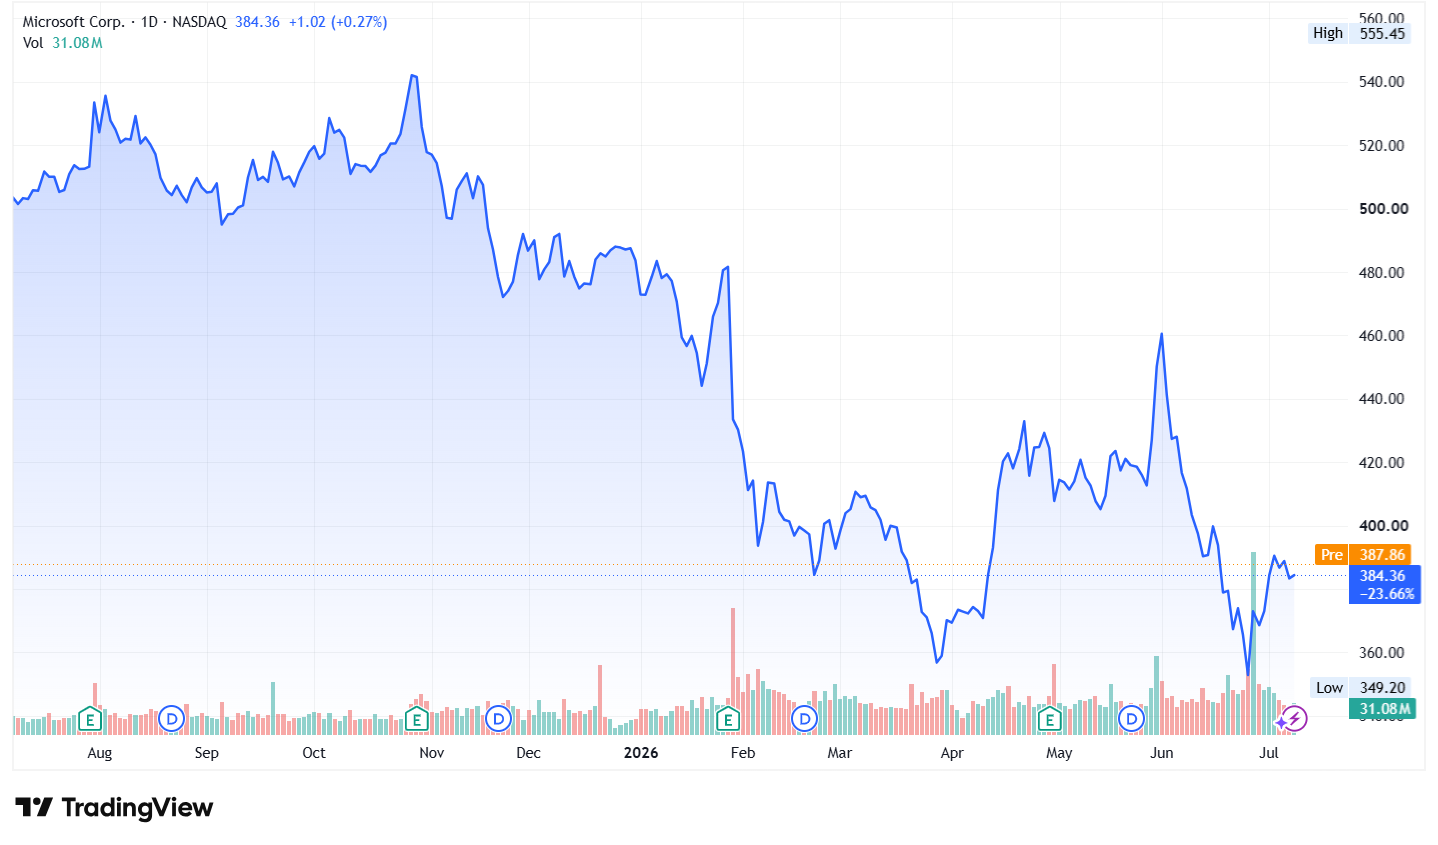
The sustainability report received attention, but it did not become the main driver of Microsoft’s (MSFT) share or stock price movement.

Microsoft MSFT stock price

Instead, investors remained focused on the company’s AI business. Microsoft continues to expand Azure, Copilot, and its broader AI ecosystem, which many analysts see as major sources of future revenue.

The report showed that the company is investing significantly to reduce its environmental impact. It is not backing away from its climate commitments. For many investors, the main question is whether Microsoft can keep growing AI and lower emissions over the next decade.

That balance will likely become an increasingly important measure of long-term corporate performance.

AI Is Reshaping the Net-Zero Journey

Microsoft’s latest report highlights a challenge facing the entire technology sector.

Building AI infrastructure creates emissions today because it requires large amounts of steel, cement, semiconductors, and electricity. Those emissions may continue to rise in the near term as companies expand their data center networks.

At the same time, technology companies are investing at record levels in renewable energy, cleaner supply chains, and carbon removal. The goal is to reduce the carbon intensity of future growth rather than slow innovation.

Microsoft’s results show that reaching net zero is unlikely to follow a straight path. Short-term emissions may increase as companies build the infrastructure needed for an AI-powered economy.

The long-term success of those climate strategies will depend on whether investments in clean electricity, low-carbon materials, and carbon removal can outpace that growth.

For now, Microsoft’s report offers one of the clearest examples yet of the trade-offs between rapid AI expansion and corporate climate goals. It also shows why transparency will be just as important as ambition as companies work toward a net-zero future.

From Oil to Renewables: How MENA Is Reshaping the Global Energy Future

The Middle East and North Africa (MENA) is rapidly transforming from a fossil fuel-dominated region into one of the world’s fastest-growing clean energy markets. Governments are investing heavily in solar, wind, and green hydrogen while setting ambitious climate targets that are reshaping their long-term energy strategies.

The region’s combination of abundant sunshine, strong wind resources, competitive project costs, and supportive government policies is attracting billions of dollars in investment. As renewable projects move from planning to construction, MENA is positioning itself as a global leader in the clean energy transition.

Renewable Targets Are Driving a Regional Energy Shift

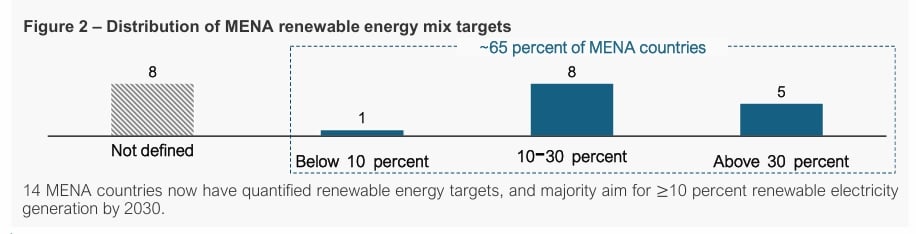
Climate ambition across MENA has accelerated significantly over the past few years. According to the International Energy Forum’s (IEF) Progress Report for MENA NDCs and Climate Action, most countries in the region have strengthened their renewable energy commitments under their Nationally Determined Contributions (NDCs).

As of 2024, 14 MENA countries had included explicit renewable energy targets in their climate plans. Twelve countries expressed these goals as a share of electricity generation, with many aiming for renewable electricity to account for at least 30% of their power mix by 2030. Four countries instead adopted capacity-based targets measured in gigawatts (GW).

Beyond their 2030 commitments, many governments have also introduced long-term strategies extending to 2050. These plans include net-zero emissions goals and higher renewable energy shares, signaling that clean electricity is becoming a central pillar of national economic development rather than simply a climate initiative.

Although each country follows its own pathway depending on its resources and existing energy system, the overall direction is consistent. Governments are working to diversify electricity generation, improve energy security, reduce emissions, and create new industries that support long-term economic growth.

Together, these commitments represent a structural shift in how the region plans its future energy system.

mena renewable outlook
Source: IEF

Solar Leads an Unprecedented Expansion

Solar power has become the engine behind MENA’s renewable energy growth.

  • The IEF estimates the region could install between 220 GW and 450 GW of solar photovoltaic (PV) capacity by 2035, allowing solar to provide roughly 25% of regional electricity generation.

This rapid expansion is supported by some of the world’s most competitive renewable energy markets. Public auctions held across the region have consistently produced record-low electricity prices.

In 2024, utility-scale solar projects achieved prices between $10 and $13 per megawatt-hour, while onshore wind projects secured bids ranging from $16 to $17 per megawatt-hour.

Several factors explain these exceptionally low costs:

  • Excellent solar irradiation across desert regions
  • Large-scale project development
  • Long-term power purchase agreements
  • Strong government support that lowers investment risk

The region is also home to several of the world’s largest renewable energy developments. Dubai’s Mohammed bin Rashid Al Maktoum Solar Park, for example, is expanding toward 5 GW of installed capacity, demonstrating how MENA countries are building renewable projects at a scale rarely seen elsewhere.

Solar MENA
Source: IEF

Project Pipeline Shows Strong Momentum

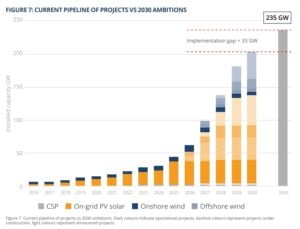
Recent data from Dii Desert Energy indicates that the region has entered what it describes as an “exponential growth phase.”

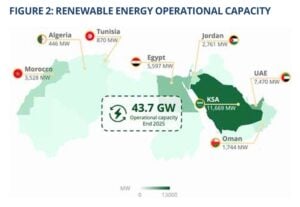
Operational renewable capacity reached 43.7 GW by the end of 2025, while the total development pipeline climbed to approximately 202 GW. This growing pipeline places the region much closer to achieving its renewable energy ambitions for 2030.

Renewable energy mena
Source: dii-desertenergy

Solar continues to dominate the expansion.

Installed solar PV capacity increased to 34.5 GW by the end of 2025, representing a sharp rise compared with previous years. Even more impressive is the development pipeline, where solar accounts for roughly 130 GW of future capacity.

Together, these figures suggest that renewable deployment across MENA is accelerating rather than slowing, with utility-scale projects driving most of the growth.

Saudi Arabia and the UAE Are Setting the Pace

Several countries are emerging as regional leaders, but Saudi Arabia has become the primary growth engine.

  • The kingdom nearly tripled its renewable capacity within a single year, increasing operational capacity to 11.7 GW.
  • Massive investments, supported by the country’s Vision 2030 strategy, continue to drive renewable deployment at an unprecedented pace.

Saudi Arabia also boasts some of the world’s lowest renewable electricity costs, helping attract both domestic and international investors.

The United Arab Emirates remains another major clean energy leader.

Construction is underway on a groundbreaking 5.2 GW solar project paired with 19 GWh of battery storage, designed to provide 1 GW of continuous baseload renewable electricity. The project demonstrates how large-scale battery storage is becoming an essential component of the region’s renewable energy strategy by improving grid reliability and reducing dependence on conventional power generation.

Wind Energy Continues to Gain Ground

Although solar dominates new installations, wind energy is steadily expanding across the region. Operational wind capacity reached 7.4 GW, while another 65 GW remains under development.

  • Egypt currently leads MENA with more than 3 GW of installed wind capacity, followed by Morocco with approximately 2.4 GW.

Much of the recent growth came from Egypt, where two major projects entered operation during 2025.

The Amunet Wind Farm added 505 MW, while the Red Sea Wind Energy Phase II project reached its full 650 MW capacity. Morocco also expanded its renewable portfolio by completing the 60 MW Dakhla Desalination Wind Farm.

  • Looking ahead, Saudi Arabia is expected to become one of the largest wind markets in the region. Several major projects have already secured financing, including the 2 GW Starah Wind Project and the 1 GW Shaqra Wind Project. Both developments are expected to begin operations between late 2027 and early 2028.

Although wind deployment is progressing more slowly than solar, the growing pipeline indicates that it will remain an important part of MENA’s diversified renewable energy mix.

solar and wind mena
Source: dii-desertenergy

Green Hydrogen Is Becoming the Next Growth Opportunity

Beyond electricity generation, MENA is increasingly positioning itself as a future global supplier of clean hydrogen.

The International Energy Forum notes that hydrogen has become a central feature of regional climate strategies since 2022. Governments increasingly view hydrogen as both a decarbonization tool and an opportunity to build entirely new export industries.

Hydrogen can help reduce emissions in sectors that are difficult to electrify, including steel production, chemicals, aviation, shipping, and heavy industry. It can also improve energy storage and strengthen long-term energy security.

Green hydrogen, produced using renewable electricity and electrolysis, dominates regional plans. According to the International Renewable Energy Agency (IRENA), more than 85% of announced hydrogen capacity across MENA involves green hydrogen projects.

However, several Gulf countries are also investing in blue hydrogen, which combines natural gas with carbon capture technologies. Policymakers see blue hydrogen as a practical transition pathway that can generate export revenues while renewable electricity capacity continues expanding.

Today, 17 MENA countries have launched hydrogen-related initiatives through national strategies, pilot projects, partnerships, or memoranda of understanding.

  • Many governments envision producing between 5 million and 10 million tonnes of clean hydrogen annually by 2040, aligning these plans with broader net-zero commitments extending to 2050.
Green hydrogen mena
Source: dii-desertenergy

Projects Are Advancing, but Challenges Remain

Despite ambitious announcements, commercial hydrogen deployment remains in its early stages. According to Dii Desert Energy, only two pilot projects are currently operational across the region. Both are located in the UAE.

DEWA Green Hydrogen Pilot Plant

The first is the DEWA Green Hydrogen Pilot Plant, which operates a 1.25 MW PEM electrolyzer. The second is the Masdar–Emirates Steel demonstration project, which uses green hydrogen to produce low-carbon steel.

By the end of 2025, only five hydrogen projects had reached financial close and moved into construction or early implementation.

NEOM Green Hydrogen Project

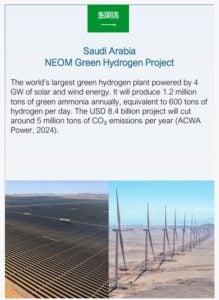
The flagship project remains Saudi Arabia’s NEOM Green Hydrogen Project, currently about 80% complete. Scheduled for commissioning during the first quarter of 2027, the facility will become the world’s largest green hydrogen project.

The project combines 4 GW of dedicated solar and wind power with 2.2 GW of electrolyzers to produce approximately 1.2 million tonnes of green ammonia annually, creating one of the largest renewable-powered industrial complexes ever developed.

saudi arabia neom
Source: IEF

Ambition Is High, but Execution Must Accelerate

While long-term goals remain impressive, implementation has not kept pace.

Current estimates place MENA’s planned electrolyzer capacity between 200 GW and 230 GW, although much of this is concentrated within a handful of mega-projects. The 17 largest projects alone account for approximately 118 GW of proposed capacity.

Developers are also scaling back some of the earliest announcements to improve project feasibility. Mauritania’s Project Megaton Moon, for instance, was originally proposed at 35 GW but has since been reduced to 6 GW, reflecting more realistic financing and construction timelines.

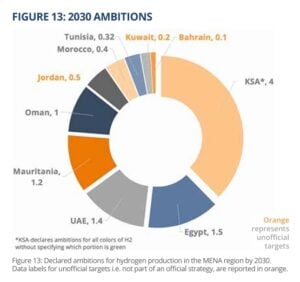
Regional hydrogen strategies still target around 10 million tonnes of annual clean hydrogen production by 2030, with green hydrogen expected to contribute the majority of output.

However, progress has been slower than expected. Limited final investment decisions, financing delays, regulatory uncertainty, and infrastructure challenges have pushed back several projects. As each year passes without significant construction activity, achieving the 2030 production target becomes increasingly difficult.

Even so, MENA’s overall clean energy trajectory remains firmly upward. Rapid solar deployment, expanding wind capacity, competitive renewable electricity costs, and growing hydrogen investments are steadily reshaping the region’s energy landscape.
$500M Wind-Powered Ships Could Transform Green Hydrogen Production

Green hydrogen could play a major role in cutting emissions from heavy industry, shipping, and aviation. However, producing it remains expensive because it requires large amounts of renewable electricity and costly infrastructure. A new project aims to change that.
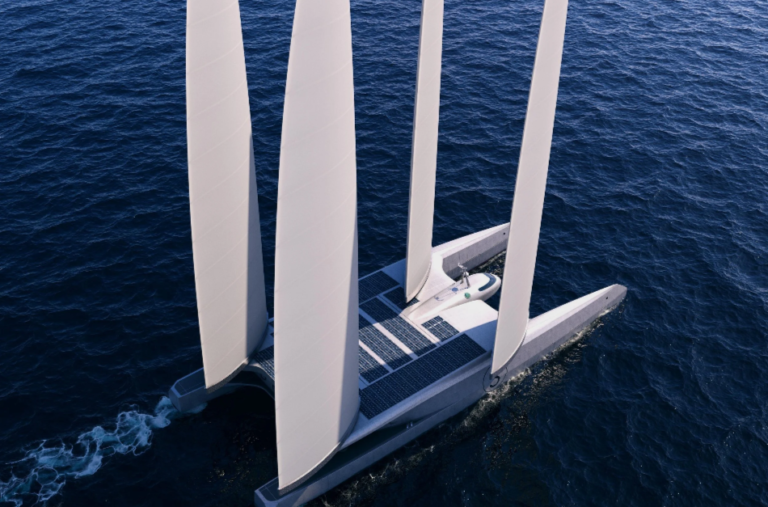
UK-based DRIFT Energy plans to deploy more than 50 wind-powered sailing vessels that will produce green hydrogen at sea instead of on land. With a $500 million investment from Commenda Capital Partners, this initiative could provide a new method for producing clean hydrogen and reduce costs.

Ben Medland, CEO of DRIFT Energy, remarked:

“Securing this financing framework with Commenda Capital is an important step in proving that DRIFT’s model is not only visionary, but bankable and scalable. It positions us to lead the deployment of the world’s first energy-harvesting vessels and to show how clean energy can be produced offshore and delivered directly to end users.”

Sailboats Could Become Floating Hydrogen Plants

DRIFT Energy is developing sailing vessels that use wind power to produce green hydrogen while at sea.

Each vessel will generate electricity using underwater turbines that spin as the boat moves through the water. That electricity powers an onboard electrolyzer, which splits desalinated seawater into hydrogen and oxygen. The hydrogen is compressed and stored onboard before being delivered to ports.

Unlike conventional offshore wind projects, the vessels do not need fixed foundations, undersea cables, or hydrogen pipelines. Instead, the boats sail to areas with strong winds, produce hydrogen, and transport it back to shore.

The company claims this method could lower capital costs and transmission losses. It also enables hydrogen production in remote areas where traditional offshore setups can’t reach.

To speed up deployment, DRIFT Energy has signed a $500 million framework agreement with Commenda Capital Partners. The financing will help build at least 50 vessels. This makes it one of the largest planned fleets for offshore hydrogen production.

Green Hydrogen Demand Is Rising, but Supply Still Lags

The project comes as demand for green hydrogen continues to increase. According to the International Energy Agency (IEA), global hydrogen demand reached almost 100 million tonnes (Mt) in 2024 and is expected to surpass that milestone in 2025.

low-emissions hydrogen production IEA
Source: IEA

However, only around 1 million tonnes came from low-emissions hydrogen, such as green and blue hydrogen. Most hydrogen is still produced from natural gas and coal, creating significant carbon emissions.

The IEA estimates that hydrogen production emits about 900 million tonnes of CO₂ each year. That’s roughly the same as the yearly emissions of a large industrialized country.

Governments want to change that. Over 60 countries have adopted hydrogen strategies, says the Hydrogen Council. The challenge is turning those plans into commercial projects that can produce hydrogen at competitive prices.

The Cost Barrier Holding Green Hydrogen Back

Green hydrogen is produced using renewable electricity, making it one of the cleanest fuels available. It can take the place of fossil fuels in hard-to-electrify areas. This includes steel, chemicals, shipping, aviation, and heavy transport.

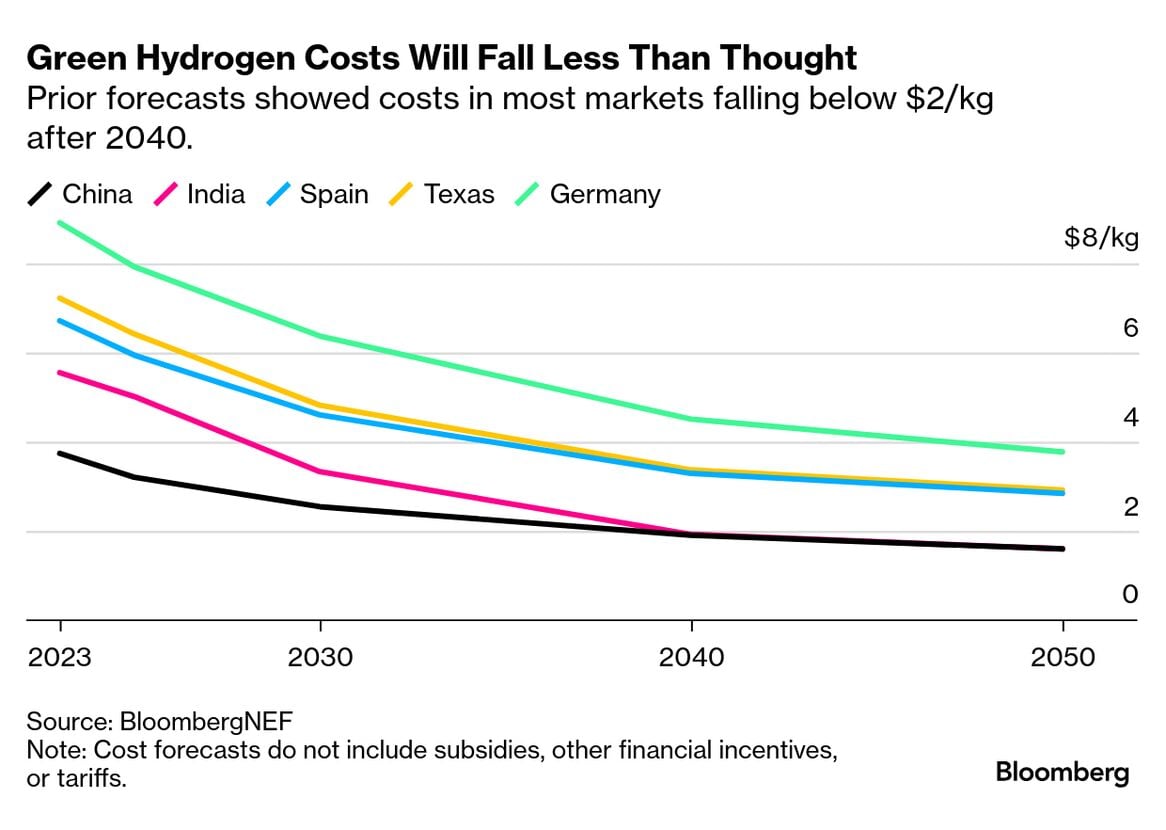
The problem is cost. BloombergNEF reports that the cost of producing green hydrogen will decrease less than what others initially estimated. 

green hydrogen cost

Moreover, the International Renewable Energy Agency (IRENA) estimates that renewable electricity makes up about 60% to 70% of the cost to produce green hydrogen. Developers must also invest in electrolyzers, transmission lines, pipelines, storage facilities, and export terminals.

These costs have slowed adoption, even as governments increase support.

DRIFT Energy believes producing hydrogen directly at sea could remove some of the most expensive parts of the supply chain. The company transports hydrogen from offshore wind farms to land. It uses the same vessels that produce the hydrogen.

If successful, the model could make green hydrogen more competitive while opening new renewable energy resources far from existing power grids.

Why Green Hydrogen Matters for Net-Zero Goals

Green hydrogen will be key in reducing emissions from industries that can’t easily switch to electricity.

The IEA says that by 2050, hydrogen could supply around 10% of global final energy use in a net-zero scenario. It can replace fossil fuels in steelmaking, fertilizer production, chemicals, shipping, and aviation. It also works for other heavy industries.

global hydrogen demand net zero
Source: IEA

Shipping alone shows why cleaner fuels are needed. The International Maritime Organization (IMO) estimates that shipping produces about 3% of global greenhouse gas emissions. As global trade grows, demand for low-carbon marine fuels is also expected to increase.

Green hydrogen can be made into fuels like green ammonia and green methanol. These are top choices for low-carbon shipping.

DRIFT Energy aims to produce hydrogen at sea to help supply growing markets and cut the need for expensive onshore infrastructure.

Billions Are Flowing Into the Hydrogen Economy

Despite high costs, investment in green hydrogen continues to grow.

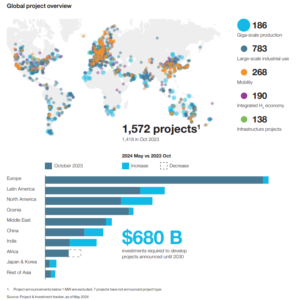
The Hydrogen Council reports that global hydrogen investments will exceed $680 billion by 2030. Only a small number of these projects have reached the final investment decision stage. This shows that financing and project economics are still major challenges.

global hydrogen in numbers
Source: Hydrogen Council and McKinsey Report

Governments are also stepping up support. The International Energy Agency reports that over 60 countries now have national hydrogen strategies. At the same time, the capacity for electrolyzer manufacturing is growing.

Technology is also improving. The IEA estimates that global electrolyzer manufacturing capacity now exceeds 25 gigawatts (GW) per year. As production scales up, equipment costs are expected to fall, making green hydrogen more affordable.

Projects that lower infrastructure costs could help speed up commercial deployment.

Floating Hydrogen Could Open New Renewable Resources

One of the biggest advantages of DRIFT Energy’s approach is flexibility.

Traditional offshore wind farms can only operate where transmission cables and grid connections are available. Floating hydrogen vessels are different. They can sail to areas with stronger and more consistent winds, produce hydrogen there, and return to port when their storage tanks are full.

This allows developers to capture renewable energy that would otherwise go unused.

The concept could also reduce the need for new pipelines, transmission lines, and export terminals. These facilities often account for a large share of project costs and can take years to build.

The technology is still new, but plans for over 50 vessels show rising confidence that offshore hydrogen production might soon be commercially viable.

A New Direction for the Hydrogen Industry

The DRIFT Energy project is more than an experiment with sailing vessels. It challenges how green hydrogen is produced and transported.

Instead of bringing electricity to hydrogen plants, the company brings hydrogen production to where renewable energy is strongest. If the model works at scale, it could lower costs, expand clean fuel production, and make better use of offshore wind resources.

The global hydrogen industry still faces major hurdles. Costs remain high, and most hydrogen today is still made from fossil fuels. But new ideas like floating hydrogen production show that the industry is looking beyond traditional solutions.

As countries work toward net-zero emissions, projects that combine renewable energy with lower-cost hydrogen production could play an important role in supplying clean fuel for heavy industry, shipping, and other hard-to-abate sectors.

Verra Looks Beyond Voluntary Markets with New Compliance Strategy and Article 6 Push

The carbon market is entering a new phase. Governments are building compliance carbon markets. Companies are demanding better carbon credits. At the same time, international carbon trading under Article 6 of the Paris Agreement is starting to expand.

Verra, the world’s largest carbon credit standard, is responding with a new strategy focused on stronger credit quality, government partnerships, and compliance markets. The organization recently announced three major initiatives that could shape its future role in global carbon markets.

Beyond Voluntary Carbon: Verra Broadens Its Role

First, Verra said it wants to play a bigger role in compliance carbon markets, where governments require companies to cut or offset emissions. Second, it introduced stricter rules for issuing soil carbon credits from sustainable grasslands. Then it signed a cooperation agreement with Misiones Province in Argentina. This will help develop projects that could create carbon credits for international trading under Article 6.

Together, these moves show that Verra is preparing for a carbon market that goes far beyond voluntary corporate purchases.

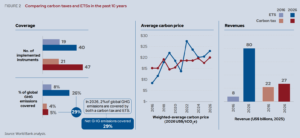
The shift reflects changes across the industry. The World Bank’s State and Trends of Carbon Pricing 2026 reports 87 carbon pricing tools in use globally. This includes 47 carbon taxes and 40 emissions trading systems.

Together, they cover about 29% of global greenhouse gas emissions and generated a record $107 billion in government revenue in 2024.

carbon tax and ets 2026
Source: World Bank report

As more countries introduce carbon pricing, demand for high-quality credits that meet government rules could grow.

Carbon Credit Quality Is Now the Top Priority

Verra’s strategy also follows a slower year for carbon credit issuances. The organization said credit issuance declined by around 30% year-on-year. The slowdown reflects a broader market shift rather than weaker climate ambition.

After years of rapid growth, buyers are paying much closer attention to project quality. They want stronger scientific evidence, better monitoring, and clear environmental benefits before purchasing credits.

This change follows increased scrutiny of carbon markets over the past two years. Organizations like the Integrity Council for the Voluntary Carbon Market (ICVCM), the Voluntary Carbon Markets Integrity Initiative (VCMI), and the Science Based Targets initiative (SBTi) have stepped up. They’ve introduced stricter guidelines to boost market integrity.

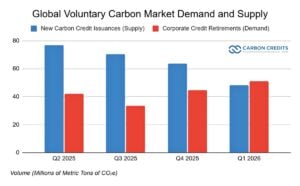
Even with slower issuance, short-term and even long-term demand remains strong, as shown in the chart below. 

voluntary carbon credit market demand and supply
Source: Sylvera Carbon Market Analytics Platforms, 2025–2026 data consolidation

While data reflects the total global market, the steep drop in Q4 2025 and Q1 2026 issuances is primarily driven by structural freezes, project audits, and methodology overhauls at Verra, which commands over 60% of total market activity.

Rather than issuing more credits, Verra says its priority is to improve quality and prepare for the next stage of market growth.

Verra Tightens Standards for Soil Carbon Credits

Verra is also tightening the rules for soil carbon projects. Its updated method includes sustainably managed grasslands. These grasslands take in carbon dioxide from the air and store it in the soil.

Healthy grasslands boost biodiversity, cut soil erosion, and help hold water in droughts.

However, measuring soil carbon is difficult. Carbon levels vary due to weather, soil conditions, and how land is managed. Verra’s new rules need better monitoring, improved data collection, and stricter verification. This will help boost confidence in the credits.

The move comes as nature-based carbon credits receive growing attention from buyers. MSCI reports that nature-based projects made up around 36% of voluntary carbon credit retirements in 2025. This makes them the biggest project category in the market.

Argentina Partnership Supports Article 6 Carbon Trading

Lastly, Verra’s latest agreement with Misiones Province in Argentina shows where the carbon market is heading.

Instead of working only with private project developers, Verra is now helping governments prepare for Article 6 carbon trading. The agreement will help Misiones build technical skills. It will also aid in developing carbon projects, measuring emissions reductions, and meeting international reporting standards.

These projects could eventually generate Internationally Transferred Mitigation Outcomes (ITMOs) under Article 6. ITMOs are verified emissions reductions that one country can transfer to another to help meet climate targets.

Pamela Kruszelnicki, director of financial management at the Ministry of Treasury, Finance, Public Works, and Public Services of Misiones, remarked:

“The recent certification of our Jurisdictional REDD+ Program under Verra’s JNR Framework—a first-of-its-kind milestone globally—demonstrates that it is possible to combine development, conservation, and climate finance under high standards of integrity and transparency.”

Interest in Article 6 is growing quickly. According to the UNFCCC, more than 100 countries have expressed interest in using Article 6 to help achieve their climate goals. Several bilateral agreements have already been signed, including deals involving Singapore, Japan, Switzerland, South Korea, and Sweden.

As countries implement these agreements, they are likely to increase the demand for trusted carbon accounting and independent verification. That creates new opportunities for standards organizations like Verra.

Trust Is Replacing Volume as the Market’s Currency

The carbon market is no longer focused on issuing as many credits as possible.

Instead, buyers are asking tougher questions. They want to know whether a project delivers real emissions reductions, protects biodiversity, and benefits local communities. They also expect stronger monitoring and independent verification.

These changes are reshaping the market. Higher-quality credits may take longer to develop, but they are expected to attract stronger long-term credit demand and higher buyer confidence.

projected global carbon credit market 2050
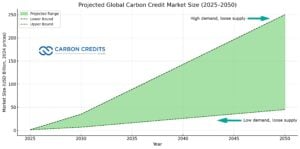
This chart shows the projected global carbon credit market size from 2025 to 2050. The green range shows lower and upper bounds, reaching $50–250 billion by 2050 (2024 prices). Growth depends on demand: high demand with loose supply drives the market to the upper bound, while low demand with loose supply results in the lower bound.

Verra Is Positioning for a New Era of Carbon Trading

Verra’s recent announcements are part of a broader strategy, not a series of separate updates.

The organization is strengthening project methodologies, expanding its work with governments, and preparing for the growth of compliance carbon markets under Article 6. These efforts reflect how the carbon market is evolving from a voluntary system into a more connected global framework.

Analysts expect this trend to continue. McKinsey & Company estimates that demand for carbon credits could reach 1.5 billion to 2 billion metric tons per year by 2030. At the same time, the World Bank expects more countries to introduce carbon pricing as they work toward their net-zero goals.

For Verra, success will depend less on the number of credits it issues and more on the trust those credits earn. As governments tighten climate policies and buyers demand greater integrity, organizations that can deliver transparent, science-based carbon credits are likely to play a larger role in the next generation of global carbon markets.

US Uranium Production Triples as Nuclear Energy Revival Fuels Mining Boom

America’s uranium industry is reviving after more than a decade of decline. Rising nuclear power demand, government support, and energy security concerns are boosting investment in the domestic fuel supply. Once thought to be fading due to low prices and heavy imports, U.S. uranium mining is now gaining strength.

The recovery aims to lessen reliance on foreign uranium and nuclear fuel services. This comes as the country faces increased electricity demand from artificial intelligence (AI), data centers, electrification, and advanced manufacturing. The growth of nuclear power and small modular reactors (SMRs) also enhances uranium’s long-term prospects.

However, domestic uranium production has recently risen, supported by billions in federal funding to rebuild mining, conversion, enrichment, and fuel manufacturing.

US Uranium Output Climbs to Its Highest Level in Years

After years of modest production, U.S. mines are ramping up.

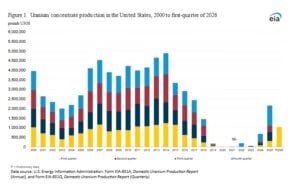
According to the EIA, domestic uranium concentrate production surged in 2025. In-situ recovery (ISR) operations restarted, and previously idle mines resumed production. This output roughly tripled from the previous year.

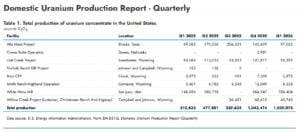
The momentum continued into 2026. In the first quarter, U.S. producers generated over 1 million pounds of uranium concentrate (U3O8) from six facilities.

uranium production
Source; EIA

They are mainly in Wyoming, Texas, and Utah. Wyoming led production, followed by Texas, where the Alta Mesa project resumed. Utah’s White Mesa Mill remained the only operational conventional uranium mill, processing ore from various states.

Despite this recovery, domestic production still covers only a small fraction of the uranium needed for America’s 94 operating nuclear reactors. The U.S. consumes over 50 million pounds of uranium annually, so imports are still vital.

Utilities have long relied on supplies from Canada, Kazakhstan, Australia, and Russia. Geopolitical tensions and supply chain security concerns have prompted Washington to rebuild domestic production.

DOE Federal Funding Sparks a Nuclear Fuel Renaissance

Government support drives the uranium industry’s recovery.

Over the past two years, the U.S. Department of Energy (DOE) has started initiatives to rebuild every stage of the nuclear fuel cycle—from mining to enrichment and advanced reactor fuel production.

A major investment occurred in early 2026 when the DOE awarded up to $2.7 billion in contracts to expand domestic uranium enrichment capacity. This funding aims to reduce reliance on Russian enrichment services while ensuring adequate fuel supplies for existing reactors and next-generation technologies.

The government is also investing heavily in High-Assay Low-Enriched Uranium (HALEU) production, which is needed by many advanced reactor designs.

In another significant step, the DOE awarded General Matter a contract worth up to $900 million to establish HALEU production at the Paducah facility in Kentucky. This project aims to boost America’s nuclear fuel independence while supporting advanced reactor deployment over the next decade.

Federal support also extends to mining and mineral processing. Energy Fuels, a major uranium producer, secured a conditional $725 million federal loan to expand domestic rare earth processing. This financing supports the company’s broader uranium operations and strengthens America’s strategic mineral supply chain.

These investments mark a policy shift. The U.S. is moving away from reliance on imported uranium and enrichment services to build a fully integrated domestic nuclear fuel industry.

Higher Uranium Prices Encourage Mine Restarts

The improving policy environment aligns with rising uranium prices.

After years of low investment post-Fukushima, uranium markets tightened as global demand grew and mine supply lagged.

Utilities are choosing long-term supply contracts more often than the spot market. This change leads to higher contract prices. It also gives mining companies the confidence to restart halted operations and invest in new projects.

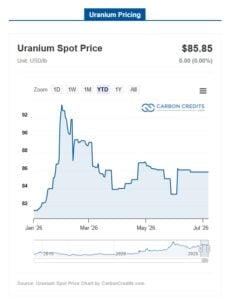
Although uranium prices saw volatility in 2025, analysts expect the market to remain strong long-term due to limited new mine development and growing nuclear capacity worldwide.

uranium prices
Source: CarbonCredits

Several investment firms forecast supply deficits later this decade as reactor demand outpaces global mine production.

Leading Companies Drive Domestic Production

A few established producers are leading the U.S. uranium revival.

  • Energy Fuels operates the White Mesa Mill in Utah, the only licensed conventional uranium mill. The facility processes uranium ore, produces vanadium, and is expanding into rare earth element processing.
  • Uranium Energy Corp. (UEC) has quickly increased production through its Wyoming ISR operations and South Texas facilities, restarting several idle projects.
  • Meanwhile, enCore Energy has resumed commercial production at its Alta Mesa ISR project in Texas, boosting domestic output.
  • Global producer Cameco also maintains U.S. assets while supplying utilities worldwide through its Canadian operations.

Together, these companies are rebuilding an industry that nearly vanished after years of weak uranium prices.

us uranium production
Source: EIA

AI and Nuclear Power Create New Demand

More than just government policy fuels the uranium recovery.

Electricity demand is rising as AI applications, cloud computing, and hyperscale data centers require reliable power. Unlike solar and wind, nuclear plants provide continuous carbon-free electricity, making them attractive to utilities and tech companies.

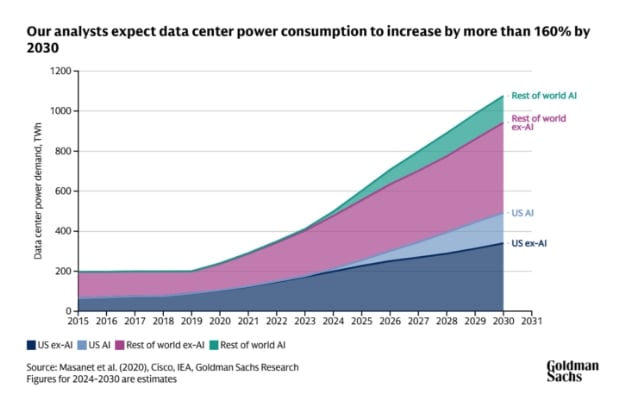
AI currently accounts for about 20% of total data center energy use, but this could rise to 40% by 2030 as AI applications expand. Goldman Sachs predicts that data center power use will climb by over 160% by the same period.

ai data center demand

Several major tech firms have made deals to support nuclear energy, ensuring reliable electricity for future data centers. Countries worldwide are extending the lives of current reactors and planning new nuclear projects. Small modular reactors are attracting significant investment for their flexibility and lower costs.

These trends are expected to boost uranium demand in the coming decades.

A Long Road Still Lies Ahead

Despite the rapid recovery, significant challenges remain.

Domestic uranium production still meets only a small share of U.S. reactor needs, meaning imports will stay essential for years. Developing new mines requires substantial capital, environmental permits, and long timelines.

However, analysts believe the fundamentals are shifting. Stronger government support, rising uranium prices, expanding nuclear generation, and growing electricity demand are creating conditions not seen since the mid-2000s uranium boom.

As the U.S. aims to boost energy security and clean energy goals, uranium is gaining importance. Production is rising, federal funding is increasing, and new reactors are on the way. America’s uranium industry seems poised for steady growth in the next decade.

US Natural Gas in 2026: Rising Demand, Record Supply, and the Emissions Challenge

The U.S. natural gas industry is entering another year of strong growth. Domestic production is reaching record highs, liquefied natural gas (LNG) exports continue to expand, and electricity demand is climbing as artificial intelligence (AI), data centers, and electrification reshape the country’s energy needs.

Natural gas remains the largest source of U.S. electricity generation, helping balance renewable energy while replacing coal in many regions. At the same time, the fuel remains under increasing scrutiny because of its carbon dioxide (CO₂) emissions and methane leaks, which are major contributors to climate change.

With prices stabilizing after years of volatility, the market is entering a new phase where demand growth and export opportunities are likely to keep natural gas at the center of the U.S. energy mix.

US Natural Gas Production Hits New Highs

The United States remains the world’s largest producer of natural gas.

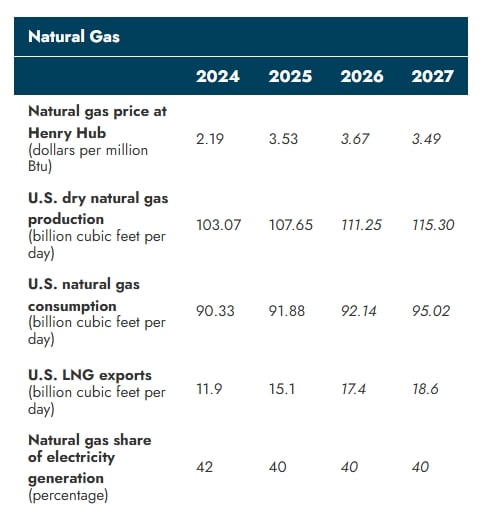
According to the latest U.S. Energy Information Administration (EIA) Short-Term Energy Outlook, U.S. dry natural gas production is expected to average 111 billion cubic feet per day (Bcf/d) in 2026, up from 107.65 Bcf/d in 2025. Production is forecast to increase further to 113.6 Bcf/d in 2027.

The growth is largely driven by:

  • Higher associated gas production from the Permian Basin
  • Increased drilling in the Haynesville shale
  • Expanding LNG export capacity along the Gulf Coast
  • Rising electricity demand

The EIA also reported that U.S. marketed natural gas production averaged 120.2 Bcf/d during the first quarter of 2026, about 4% higher than the same period last year.

Strong production has kept storage levels healthy and prevented significant price spikes despite increasing consumption.

US natural gas prices
Source: EIA

Demand Continues to Grow

Natural gas consumption remains robust across several sectors.

The EIA forecasts U.S. natural gas consumption to average 92.14 Bcf/d in 2026, increasing to nearly 95 Bcf/d in 2027.

Power generation remains the biggest source of demand.

Growing electricity use from AI data centers, cryptocurrency facilities, manufacturing, and electrification is increasing the need for reliable baseload and flexible generation.

For the Electric Power Sector

Natural gas consumption by the electric power sector is expected to reach a record 38.1 Bcf/d in 2026, with monthly demand potentially exceeding 50 Bcf/d during peak summer periods.

Electricity demand itself is also setting new records.

natural gas prices
Source: EIA

The EIA projects total U.S. electricity consumption will rise to 4,269 billion kilowatt-hours (kWh) in 2026 and 4,399 billion kWh in 2027, driven largely by commercial customers and energy-intensive AI infrastructure.

LNG Exports Are Supporting the Market

The United States has become one of the world’s largest LNG exporters, and overseas demand continues to strengthen domestic natural gas markets.

  • LNG exports to increase from 15.1 Bcf/d in 2025 to 17.2 Bcf/d in 2026, reaching 18.6 Bcf/d in 2027.

New export terminals along the Gulf Coast are creating additional demand for U.S. shale gas while helping supply Europe and Asia as many countries diversify away from Russian gas.

Higher exports also provide producers with more stable long-term markets, even when domestic demand fluctuates.

Natural Gas Prices Have Stabilized

After several years of sharp swings caused by weather, geopolitical tensions, and storage changes, natural gas prices have become relatively stable.

  • Henry Hub natural gas prices are expected to average around $3.60 per million British thermal units (MMBtu) in 2026, slightly above 2025 levels, according to the EIA.
  • In recent trading, NYMEX natural gas futures have remained close to $3.25 per MMBtu, supported by strong summer electricity demand while abundant production continues to limit major price increases.

Analysts say prices are likely to remain moderate unless extreme weather significantly reduces storage or major supply disruptions occur.

Natural Gas Still Dominates US Power Generation

Despite rapid renewable energy growth, natural gas continues to be the backbone of the U.S. electricity system. This sector can potentially generate approximately 40% of U.S. electricity through 2027, while coal’s share continues to decline.

natural gas electricity US

Renewables are projected to supply 27% of electricity generation, with nuclear contributing about 18%.

Natural gas plants remain valuable because they can quickly adjust output when wind and solar generation changes, supporting grid reliability during periods of high demand.

What About US Emissions?

Natural gas emits less carbon dioxide than coal when burned, which has helped reduce emissions from the U.S. power sector over the past two decades.

However, it remains a fossil fuel.

The EIA said U.S. energy-related CO₂ emissions are projected to decline by 1.7% in 2026 compared with 2025 before edging up by 0.5% in 2027.

  • In the near term, they are expected to remain around 4.8 billion metric tons annually. However, emissions intensity continues to decline as renewable energy expands and coal generation falls.

us emissions

Methane emissions present another challenge.

Methane is the primary component of natural gas and has a much stronger warming effect than carbon dioxide over the short term. Leaks during production, processing, and transportation significantly increase the climate impact of natural gas.

Reducing methane emissions through improved monitoring, leak detection, and tighter regulations remains one of the fastest ways to lower greenhouse gas emissions from the industry.

AI Is Creating a New Source of Gas Demand

One of the biggest changes in the U.S. energy market is the rapid growth of AI infrastructure.

Large data centers require enormous amounts of electricity, and utilities are increasingly relying on natural gas plants to provide reliable power while renewable generation and transmission projects are built.

The EIA expects commercial electricity demand to exceed residential demand for the first time in U.S. history, reflecting rapid expansion of AI and digital infrastructure.

However, environmental groups warn that relying heavily on gas-fired generation for AI could increase greenhouse gas emissions if renewable deployment does not keep pace. Recent research suggests dozens of proposed gas plants dedicated to data centers could substantially increase emissions over the coming decades.

Can Natural Gas Support the Energy Transition?

Supporters argue that it provides reliable, affordable electricity while enabling higher levels of wind and solar generation. It also strengthens energy security and supports economic growth through exports and manufacturing.

Critics point to continued carbon emissions, methane leakage, and the risk of locking in long-term fossil fuel infrastructure that could delay deeper decarbonization.

The future role of natural gas will likely depend on several factors:

  • Growth of renewable energy and battery storage
  • Carbon capture and storage deployment
  • Methane emission reductions
  • LNG export demand
  • AI-driven electricity consumption
  • Federal and state climate policies

Outlook

The U.S. natural gas market remains fundamentally strong.

Production continues to reach new records, LNG exports are expanding, and electricity demand from AI, industry, and electrification is creating new growth opportunities. At the same time, abundant supply is keeping prices relatively stable for consumers and businesses.

Yet natural gas also sits at the center of America’s climate challenge. While it has helped replace coal and lower emissions in the power sector, meeting long-term climate goals will require substantial reductions in methane leaks and carbon emissions.

For now, natural gas is expected to remain the dominant fuel in the U.S. energy system—supporting grid reliability, economic growth, and global energy exports while the country continues its transition toward a lower-carbon future.