
Biochar is quickly becoming one of the most important technologies in the carbon removal market. But as corporate demand grows, buyers are running into a new problem: there may not be enough high-quality biochar to go around.
A new report from carbon removal marketplace Supercritical shows that 81% of high-quality biochar supply for 2026 had already been committed by July. In 2025, the same threshold was not reached until October.
The shift highlights how quickly the biochar market is moving from an emerging carbon removal technology toward a more established market where buyers are competing for proven supply.
At the same time, the market is becoming more selective. Hundreds of projects are developing biochar capacity, but Supercritical found that only a small share meets its quality standards.
Biochar Demand Is Growing Rapidly
The numbers show just how quickly demand is changing.
- Biochar sales nearly doubled in the first half of 2026, rising from 1.59 million tonnes in H1 2025 to 2.99 million tonnes across 280 deals. However, the headline growth hides an important shift in how buyers are purchasing credits.
- Spot-market sales actually fell 54%, from 174,000 tonnes to 81,000 tonnes.
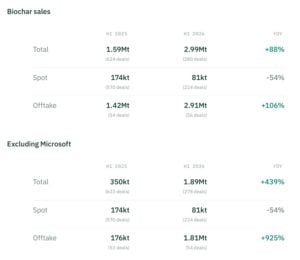
Instead, corporate buyers are increasingly signing longer-term offtake agreements. Offtake volumes jumped from 1.42 million tonnes in H1 2025 to 2.91 million tonnes in H1 2026.
- Notably, excluding Microsoft, offtake purchases increased more than tenfold, from 176,000 tonnes to 1.81 million tonnes.
In other words, buyers are not simply buying more biochar. They are locking it up earlier.
That matters because biochar has traditionally had a two-speed market. Large buyers secure future supply through offtakes in the first half of the year, while smaller buyers typically turn to the spot market later in the year.
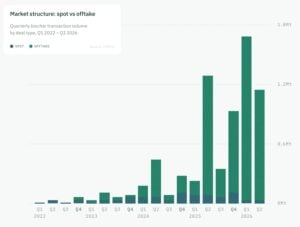
But in 2026, that pattern has become much more pronounced.
- MUST READ: The Ultimate Guide to Biochar: The “Black Gold” Fueling Durable Carbon Removal Market
- ALSO: Live Carbon Prices Today
Why High-Quality Biochar Is Harder to Find
The biochar market can look well supplied at first glance.
There are hundreds of projects across different stages of development, ranging from large industrial pyrolysis facilities to smaller distributed systems and artisanal production.
However, total capacity does not necessarily equal usable carbon removal supply.
Supercritical evaluated more than 400 biochar projects through its climate science process and found only 13 that passed its full assessment. Its 2026 report evaluates 119 projects using a 118-point vetting framework covering feedstock, production conditions, carbon stability, permanence, additionality, monitoring and verification.
This distinction matters for companies purchasing carbon removals.
For example, a project may be registered or rated but still have problems with additionality, methane emissions, delivery reliability or site-level safety.
One project Supercritical reviewed failed because it produced biochar at multiple open-pit sites without methane monitoring. Another failed an additionality assessment because the facility existed before the changes being credited. A smaller operation was also rejected because it lacked a meaningful delivery history.
So, while biochar production is expanding, high-integrity supply is a much smaller market.
The Market Is Moving Toward Long-Term Contracts
The growing preference for offtakes could reshape the biochar market.
Non-Microsoft buyers purchased more biochar in the first half of 2026 than they purchased during all of 2025. Most of that increase came from multi-year offtake agreements.
Part of the reason is that companies are beginning to plan carbon removal as a long-term component of their net-zero strategies rather than as an annual purchase.
Supercritical points to the Science Based Targets initiative’s Corporate Net-Zero Standard v2, which makes permanent carbon removal mandatory from 2035, eventually requiring removals for residual emissions. The EU’s Carbon Removal Certification Framework also certified biochar as a permanent removal pathway in February 2026.
As these frameworks develop, companies have more reason to secure future supply before they actually need it.
That creates a difficult position for buyers that rely on the spot market.
- By July, 81% of high-quality 2026 supply had already been committed through offtakes and exclusive agreements. Supercritical estimates that active corporate RFPs could potentially claim another 70% of what remains.
Why Biochar Prices Could Rise Later in the Year
Timing is becoming increasingly important.
Historically, the fourth quarter has been the busiest period for biochar spot purchases. In Q4 2025, 994 spot transactions moved about 125,000 tonnes, with an average deal size of roughly 125 tonnes.
Thus, the three factors driving the late-year rush are:
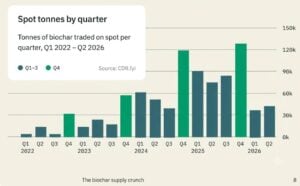
The result is a market where fresh supply and peak demand can collide toward the end of the year.
And prices already show the effect.
Supercritical reported that a biochar credit from the same project sold for $155 per tonne in July 2025 but reached $185 per tonne by November.
The report says high-quality biochar prices have remained broadly stable since 2024, but seasonal demand can push spot prices higher during the second half of the year.
That suggests the issue is not simply whether biochar is becoming more expensive. It is whether buyers are willing to wait until the market is most competitive.
India Is Becoming an Important Biochar Market
The supply story also highlights India’s growing role in biochar carbon removal.
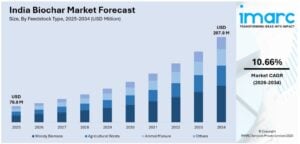
Supercritical’s 2026 portfolio includes several Indian projects, including Varaha’s distributed biochar operation and Ground Up’s project using sugarcane residues.
Varaha’s model uses cotton stalks that might otherwise be burned, as well as the invasive Prosopis juliflora shrub. Its biochar is verified through Isometric, with batches tracked from production to soil.
Ground Up is already issuing credits through Isometric. According to Supercritical, field trials have shown potential yield increases of up to 38% for local sugarcane and 59% for wheat.
This points to one of biochar’s biggest advantages: the technology can connect carbon removal with agricultural waste management and soil applications.
India’s large agricultural residue base could therefore become an important source of future biochar supply, provided projects can meet the required standards for emissions monitoring, permanence, additionality, and verification.
The Bigger Problem Is Scaling High-Quality Supply
Biochar has already delivered more than twice the volume of all other permanent carbon removal pathways combined, according to Supercritical. It is also currently the only permanent removal method with a liquid spot market.
But its next challenge is not simply building more projects.
It is building projects that can reliably deliver high-quality removals at scale.
Supercritical says 73% of biochar projects revised their capacity downward in 2025. That highlights another risk for buyers: announced capacity can look very different from actual deliveries.
For corporate buyers, this makes due diligence increasingly important. Registry certification and third-party ratings can provide a starting point, but they may not answer every question about a project’s operations or ability to deliver.
As the market matures, buyers are likely to place greater value on projects with proven production records, robust monitoring and reliable feedstock.