Verra’s CEO Mandy Rambharos made an intensely grim announcement on October 21st about company restructuring. Coming to the point directly, she said,
“Today, I informed our team of a difficult but necessary decision to reduce our workforce by roughly 25 percent. This step, though not made lightly, is critical to aligning our resources with our core priorities and ensuring that Verra remains agile and capable of leading in a rapidly changing environment. This realignment will allow us to focus more intently on maintaining the rigor and integrity of our standards programs, providing stronger support for our stakeholders, and continuing to work collaboratively across the ecosystem to bolster environmental and social markets.”
In her press statement, she stressed the importance of sharing Verra’s vision and reinforcing its commitment to make climate action more impactful. Additionally, she highlighted the need for sustainable development in voluntary carbon markets (VCM). This involves constant evaluation of how to serve stakeholders in a better way in an evolving market environment.
Rambharos also highlighted the insights from the 2024 Stakeholder Survey. She noted that Verra had recognized the recent challenges in project review times, stakeholder engagement, clarity in processes, and technical solutions. This prompted the decision to restructure and streamline operations to address these challenges, even with a reduced workforce.
The CEO reaffirmed Verra’s mission and expressed confidence that these changes will strengthen the organization, making it more resilient and capable of leading the future of VCM.
In 2023, Verra laid new foundations and enhanced ongoing initiatives aimed at advancing climate action and sustainability. The company expects these standards programs to be highly successful in the future.
A major achievement in the Verified Carbon Standard (VCS) Program was the launch of a new REDD methodology (VM0048) and a module (VMD055) that focused on preventing unplanned deforestation. These tools are meant to channel funding to forest conservation. The program also updated several existing methods and progressed with developing the next version of the VCS.
To expand its reach, the program worked with the Integrity Council for the Voluntary Carbon Market (ICVCM) and teamed up with governments and financial institutions. Additionally, Verra initiated work on a Scope 3 Standard Program to help companies lower the carbon emissions in their supply to achieve their climate goals.
However, last year the carbon credit certifier made headlines for approving “worthless” offsets which would dampen its integrity. In January 2023, The Guardian performed a high-profile investigation and claimed that over 90% of its rainforest offset credits are likely “phantom credits”. It means they may not reflect “real” carbon reductions. Having received serious criticism over the quality of its products, David Antonioli, the former CEO of Verra, had to step down in May 2023.
But that’s not the end of the story, Verra’s VCM and GHG crediting program is still touted to be one of the most trustworthy and globally acclaimed.
Nevertheless, downsizing the workforce by 25% is a tough decision regardless of the reasons behind it. We hope CEO Mandy Rambharos succeeds in her efforts and upholds Verra’s goodwill as outlined in this announcement.
As governments across the world push for cleaner energy, the competition between India and China for cleantech dominance intensifies. China’s early investment in clean energy technology and manufacturing has given it a significant lead. However, India is rapidly building its capacity, aiming to grab the spotlight in the global market.
This analysis explores the current landscape, identifying strengths, weaknesses, and what lies ahead for both nations in the cleantech race.
China’s Technological Edge and Cost Advantage
China remains a global leader in clean energy manufacturing. The country’s investments in solar PV, battery technology, and wind energy have solidified its dominance. China’s advantage stems from its ability to manufacture at a lower cost while maintaining high technological sophistication.
For instance, in solar PV manufacturing, China controls key parts of the supply chain, including wafers and polysilicon, both essential for solar panel production.
Credible media sources reveal that countries like India are taking big steps, and China’s manufacturing output and efficiency continue to overshadow most nations. Its cleantech products are not only produced at a lower cost but have also overcome previous concerns about quality.This quality and competitive pricing have allowed Chinese manufacturers to grow their market share, even in sectors like wind energy, where they face strong competition.
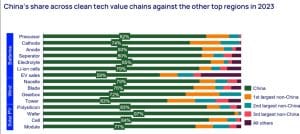
According to a Wood Mackenzie report, China now commands the manufacturing landscape across major clean technologies.
It holds 60% of the wind foundation market and an impressive 97% share of solar PV wafer production.
China’s dominance extends beyond manufacturing, with booming electric vehicle (EV) sales further highlighting its leadership in the sector.
India’s Growing Investment in Cleantech Market
India is starting to invest more in its global cleantech market. This is getting a push with its low-cost manufacturing base and government support.
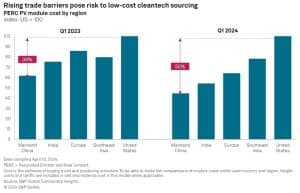
For example, the Production-Linked Incentive (PLI) scheme, has helped reduce solar PV manufacturing costs by up to 24%, making India competitive in the global market. This program aims to establish domestic manufacturing for critical clean energy components like solar modules and batteries.
Additionally, India’s energy efficiency program has been in place for years, and the country recently introduced a hydrogen policy focused on producing low-carbon hydrogen through domestic electrolyzer manufacturing.
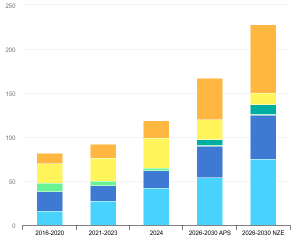
India’s clean energy sector has seen a massive uptick in investment. In 2023, the country invested $68 billion in clean energy projects, a 40% increase compared to the 2016-2020 average. Almost 50% of this spending was directed toward low-emissions power generation, particularly solar PV.
Conversely, India’s fossil fuel investments also grew by 6% to $33 billion in 2023, as the country continued to grapple with rising fuel demand.
Image: Past and future energy investment in India in the Announced Pledges Scenario and the Net Zero Emissions by 2050 Scenario, 2016-2030
Source: IEA
After evaluating the current scenario, we can say that India is on the brink of a clean energy revolution. Prime Minister Narendra Modi’s commitment to add 500 gigawatts (GW) of clean energy by 2030 will certainly help India to be a global leader in renewable energy. But the question remains how is the country planning to meet this ambitious target?
2024 Looks Rosy for India…
After years of slow progress, 2024 has marked a turning point for India’s renewable energy sector. Solar panels and wind turbines are being installed at a commendable pace. Media reports reveal that 18.8 GW of new renewable energy capacity was addedtill August this year. This way more than the total capacity of last year.
According to the International Energy Agency (IEA), India is on track to add 34 GW by the end of the year, with projections showing growth will nearly double to 62 GW annually by 2030.
On October 14, India’s power ministry announced a plan to upgrade its power grid to support renewable energy expansion through 2032. The project involves a $109 billion investment andaims to bolster Prime Minister Narendra Modi’s vision for a clean India.
India is also benefiting from Western countries’ efforts to diversify supply chains and reduce reliance on China. The US and the EU have enacted tariffs and trade restrictions on Chinese products, giving Indian manufacturers an opening to supply premium-priced markets, particularly in solar PV. However, market analysts also predict that India could become the second-largest solar PV manufacturing region after China in 3-5 years down the line.
Industry experts predict that this rapid expansion might outpace China’s growth rate in the second half of the decade, positioning India as the world’s fastest-growing clean energy market.
But is it as rosy as it seems to be? The answer is probably no. We unlock the challenges below.
A Lingering Challenge for India’s Clean Tech Future
However, India still faces several challenges. Despite the progress and one of the fastest-growing economies, Indian manufacturers remain dependent on China for inputs like wafers and polysilicon. Thus, India is not yet 100% self-sufficient in these areas.
Furthermore, as the country is growing, so is its energy demand. By 2050, energy demand in India is expected to outpace every other region in the world. This growing demand could put enormous pressure on its energy system, which still heavily relies on imported fossil fuels like crude oil and natural gas.
And with this rising demand comes the risk of increased carbon emissions, particularly if fossil fuel consumption continues to grow for transportation, power generation, and industrial use.
S&P Global’s research shows that India is also moving more slowly than China in wind energy and battery manufacturing. While the country is scaling up battery production, it’s unclear whether it can meet its goal of self-sufficiency by 2030. In wind energy, India’s infrastructure is better suited for onshore projects, and it may struggle to compete with China in the growing offshore wind market.
Risks of Trade Barriers and Global Oversupply
One of the major risks facing India’s cleantech expansion is potential trade barriers. As the US and EU focus on domestic reindustrialization, Indian cleantech exports could become targets for new tariffs, especially in sectors like solar PV and batteries. There’s a delicate balance between encouraging global supply chain diversification and protecting domestic industries.
Additionally, in some cleantech sectors like electrolyzers, global oversupply could make it difficult for Indian manufacturers to remain competitive. Although India is expected to produce more electrolyzers than it needs by 2030, stiff competition from established players could drive prices down, potentially limiting India’s growth in this space.
Can India Compete Without China?
China dominates global supply chains, making it unrealistic for India to fully take over its manufacturing space, according to the Economic Survey 2023-24. The survey, presented by Finance Minister Nirmala Sitharaman, emphasized that India may need Chinese investment and technology to boost its manufacturing sector. Instead of distancing from China, partnering with its expertise could be key to driving India’s cleantech growth.
The Survey pointed out that,
“It may not be the most prudent approach to think that India can take up the slack from China vacating certain spaces in manufacturing. Indeed, recent data cast doubt on whether China is even vacating light manufacturing.”
This is self-explanatory.
China’s dominance in the cleantech sector is undeniable, but India is making strides to close the gap. With strategic government support and lower production costs, India has the potential to become a key supplier of cleantech products to the US and Europe.
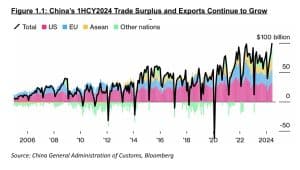
According to the Australian research group Climate Energy Finance (CEF), Chinese companies have invested over $100 billion in overseas clean energy projects since early 2023 to avoid U.S. and other tariffs.
Source: Climate Energy Finance
This shows that China’s lead in technology and cost efficiency will secure its position as a global leader for the foreseeable future. On the contrary, India’s future success will depend on overcoming its reliance on Chinese inputs. Some viable options are accelerating technological advancements and avoiding trade barriers that could hinder its growth.
From reliable economic surveys and reports, we can conclude that while India may not surpass China anytime soon, its role in the global cleantech supply chain is expanding, and the competition has just begun…
Good news for the electric vehicle (EV) industry- General Motors (GM) and Lithium Americas have inked a $625 million joint venture to develop the Thacker Pass lithium project in Nevada. This partnership is another power play to boost the U.S. domestic supply chain for EV batteries and reduce reliance on lithium imports, particularly from China.
The Background: Lithium Americas Secured $2.3B DOE Loan to Drive Thacker Pass Development
In March 2024, Lithium Americas secured a $2.3 billion loan from the U.S. DOE through its Advanced Technology Vehicles Manufacturing (ATVM) Loan Program. This funding will support the development of the Thacker Pass lithium project in Nevada.
However, before Lithium Americas can access the loan, they must contribute $195 million, which will be used to cover expenses for construction and ramping up production. Additionally, General Motors (GM) will also provide a line of credit to help fund these requirements.
General Motor’s Key Investment in 2023
Back in January 2023, General Motors made a substantial investment in Lithium Americas, agreeing to provide $650 million. This was divided into two parts: the first $320 million was delivered immediately and used to advance the first phase of Thacker Pass.
But the second part of the investment, or Tranche 2, encountered some changes. Both companies decided to revise the terms due to a company reorganization. Tranche 2 was supposed to be completed by the end of 2023.
On August 30, 2024, Lithium Americas and GM extended the deadline for Tranche 2 of their investment agreement to explore better options for GM’s additional investment. They ended the original agreement when they signed a new joint venture deal. This new deal was announced on October 16.
Unlocking the Latest JV
The latest press release mentions that General Motors has agreed to invest $625 million in cash and letters of credit for a 38% stake in the Thacker Pass project. Lithium Americas, which will manage the project, retains a 62% interest and will contribute $387 million to the joint venture. The funds will be used to develop the first stage of the project, which might cost around $2.9 billion.
Jonathan Evans, President and CEO of Lithium Americas
“Our relationship with GM has been significantly strengthened with this joint venture as we continue to pursue a mutual goal to develop a robust domestic lithium supply chain by advancing the development of Thacker Pass. Today’s joint venture announcement is a win-win for GM and Lithium Americas. GM’s JV Investment demonstrates their continued support and helps us to unlock the previously announced $2.3 billion DOE Loan. We will be working closely with GM to advance towards the final investment decision, which we are targeting by the end of the year.”
Domestic Lithium Supply to Support GM’s EV Ambitions
One of the highlights of the joint venture is GM’s expanded offtake agreement. It extends for up to 100% of lithium production from Thacker Pass’ first stage for 20 years. This agreement will help GM ensure a steady supply of lithium for its future EV batteries.
GM also secured the right to acquire up to 38% of production from the project’s second stage, with the ability to negotiate first offers for any remaining volumes.
The company’s investment in Thacker Pass is driven by the need to secure a long-term supply of lithium as the company continues to scale up its EV production.
According to Jeff Morrison, SVP, of Global Purchasing and Supply Chain of General Motors remarked,
“We’re pleased with the significant progress Lithium Americas is making to help GM achieve our goal to develop a resilient EV material supply chain. Sourcing critical EV raw materials, like lithium, from suppliers in the U.S., is expected to help us manage battery cell costs, deliver value to our customers and investors, and create jobs.”
GM’s Net Zero Pathway
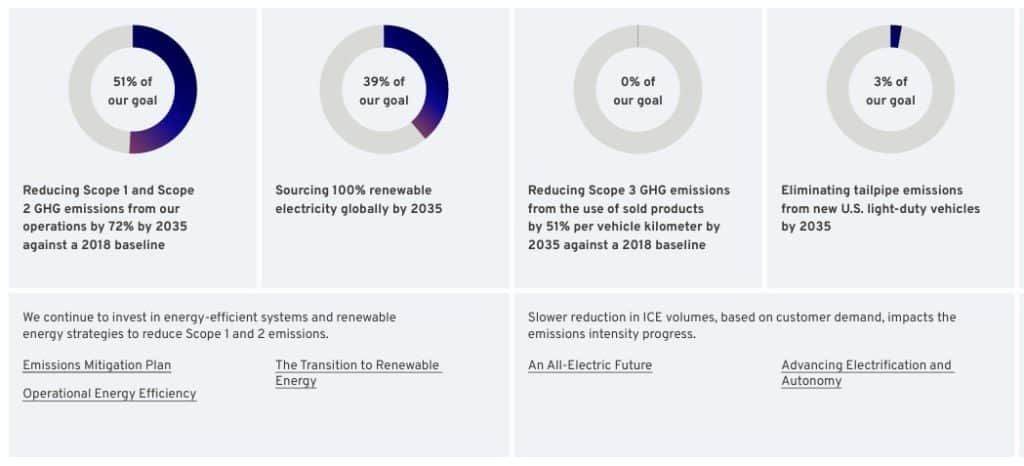
The Michigian-based EV maker aims to achieve carbon neutrality in their global products and operations by 2040.
Source: GM
As described in GM’s sustainability report, significant progress made to reduce Scope 3 emissions include:
Battery production and expansion through Ultium Cells LLC- JV with LG Energy Solution, which is manufacturing cells for its Ultium Platform.
Collaborating with Tesla to integrate the North American Charging Standard (NACS) for their EVs. It will start in 2025.
Investing in home, workplace, and public charging infrastructure in the U.S. and Canada.
Investing in hydrogen fuel cell technology to reduce the carbon emissions of medium- and heavy-duty vehicles.
Addressing the barriers to EV ownership in the United States through dealership education and engagement.
Lithium Prices and Market Challenges
While the deal is progressing the lithium market is also fluctuating simultaneously.
MINING.COM reported that prices of battery-grade lithium hydroxide have experienced a sharp decline, falling to $9,800 per ton in October 2024 from $22,275 a year earlier. This marked a significant drop from the peak prices which were around $85,000 per ton in late 2022.
Despite these market challenges, Lithium Americas continues to advance the project, positioning itself to benefit from a projected long-term demand increase for lithium as the EV market expands. The company’s shares saw a 20.2% rise after the JV announcement. This showed investor confidence in the project’s potential.
Thacker Pass: The Gateway to North American Lithium Battery Supply Chain for EVs
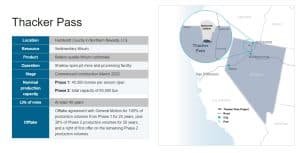
The Thacker Pass project is well underway, with approximately 40% of the engineering design already completed. Major site preparations are progressing, with earthworks for the process plant excavation nearing completion and preparations for concrete placement underway.
Located in northern Nevada’s Humboldt County, Thacker Pass is home to the largest known lithium deposit in North America. 385 million tonnes of measured and indicated resources, equivalent to six million tonnes of lithium carbonate. The mine is expected to produce enough lithium to power one million electric vehicles annually, a critical contribution to the growing U.S. EV market.
Source: Lithium Americas
Lithium Americas is focused on getting the project ready for final investment decisions by the end of the year.
The project’s first phase targets a production capacity of 40,000 tonnes of lithium carbonate per year, with significant progress anticipated in the next few years.
What’s Next for Thacker Pass?
The next steps for the joint venture include finalizing engineering designs and procurement contracts as well as securing the final investment decision by the end of 2024. GM’s involvement in the project will help Lithium Americas unlock the DOE’s loan. Subsequently, this will provide the necessary financial support to fully develop the project.
As part of the agreement, GM and Lithium Americas are working closely with Bechtel, the project’s engineering, procurement, and construction management contractor. It can create around 1,800 direct jobs during its three-year construction period.
In the coming months, the Thacker Pass project will focus on de-risking and advancing construction to ensure it meets its targets for lithium production. Once operational, the mine will significant role in securing a domestic supply of lithium. Consequently, supporting the growing demand for EVs and pushing the U.S. clean energy transition.
Key Implications in the future:
Thacker Pass could provide lithium for up to 800,000 EVs annually, reducing U.S. reliance on foreign suppliers.
It supports the U.S. goal of net-zero greenhouse gas emissions by 2050, aligned with President Biden’s climate goals.
A domestic lithium supply chain would lower carbon emissions, transport costs, and supply chain risks for U.S. car manufacturers.
Sustainably sourced battery materials would help produce electric vehicles with a smaller carbon footprint.
Notably, Lithium Americas is also in a strong position to meet the growing demand for EV batteries. It will continue to secure additional funding to fuel its motive. However, at this moment, partnering with GM will significantly impact the domestic lithium market and in a good way.
Disseminated on behalf of Alaska Energy Metals Corporation
As the world accelerates its shift towards renewable energy, the role of electric vehicles (EVs) in reducing carbon emissions has become more critical. This transition depends heavily on advancements in battery technology, which is pivotal for mass EV adoption.
A key player in this evolution is nickel, an essential material in battery production that has gained increasing attention due to its impact on EV performance and range. This article delves into the demand-supply dynamics of nickel in the EV battery sector and its role in the broader energy transition as reported by the International Renewable Energy Agency (IRENA).
Nickel’s Essential Role in EV Batteries
EV batteries consist of several critical components, with nickel playing a significant role in cathode chemistry. Nickel-rich batteries, such as Nickel Manganese Cobalt (NMC) and Nickel Cobalt Aluminum (NCA) chemistries, have become prevalent. These chemistries are favored due to their high energy density, which translates to longer driving ranges—a critical factor for widespread EV adoption.
As a result, nickel-rich batteries accounted for over half of the EV battery market in 2023, even as newer alternatives like Lithium Iron Phosphate (LFP) gained traction. Class I nickel, essential for EV batteries, accounts for only about 30% of total nickel production.
Nickel helps improve the energy density of batteries, allowing vehicles to travel further on a single charge. This advantage makes nickel-rich chemistries particularly valuable for larger vehicles like trucks and long-haul freight, where range and efficiency are crucial. As EV adoption spreads to these heavier vehicle segments, the demand for nickel-based batteries is expected to remain robust.
The rapid increase in EV adoption is directly linked to the rising demand for battery materials, including nickel. In 2023, global EV sales reached about 14 million units, representing 18% of total automobile sales.
By 2030, adhering to a 1.5°C scenario for climate goals would require sales reaching around 60 million units annually. This growth is expected to drive the demand for EV batteries to over 4,300 GWh per year, a significant increase from 2023 levels.
Nickel demand is closely tied to this trend, given the material’s crucial role in enhancing battery capacity.
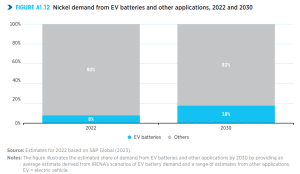
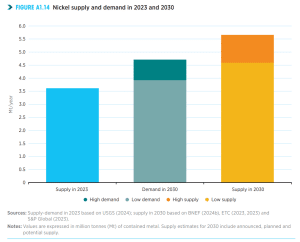
As of 2023, global nickel production reached 3.6 million tonnes, with Indonesia and the Philippines supplying nearly 60% of the world’s nickel. By 2030, demand for nickel in EV batteries is projected to rise to 18%, up from 8% in 2022, potentially reaching between 0.53 million and 1.09 million tonnes, depending on battery technology scenarios.
The overall global nickel demand is expected to range from 3.9 to 4.7 million tonnes annually by 2030.
Source: IRENA report
This expansion would see global nickel supply grow from 3.6 million metric tons (Mt) in 2023 to potentially 5.6 Mt per year by 2030. The ability of nickel production to keep pace with EV battery demand will be critical to avoiding supply bottlenecks that could hinder EV growth.
Beyond EVs, nickel’s importance extends to other applications like battery energy storage systems (BESS). As countries integrate more renewable energy sources into their grids, BESS becomes crucial for managing energy fluctuations and ensuring a stable supply.
The demand for BESS is expected to grow 6-fold between 2023 and 2030, complementing the growth in EV battery needs. While lithium remains the cornerstone of most battery chemistries, nickel’s contribution to BESS underscores its broadening role in energy storage solutions.
From Mine to Market: Navigating the Nickel Supply Chain
IRENA’s outlook for nickel supply is positive. However, challenges remain in ensuring that this supply materializes.
Despite this growing demand, the analysis indicates a lower risk of supply shortages compared to other critical materials, with a projected supply of 4.6 to 5.6 million tonnes by 2030.
Source: IRENA report
However, while general nickel supplies seem adequate, concerns over high-purity Class I nickel for EV batteries persist.
Current projections suggest sufficient Class I nickel supply until 2028, but without expansion of production, shortages could arise by the end of the decade. Innovations in battery technology could significantly reduce reliance on nickel, potentially halving demand for EV batteries if alternatives gain traction.
Current projections show a potential increase in production, but this hinges on new mining projects and expansions coming online. The Asia-Pacific region, which currently dominates global battery production, is expected to see its share decrease slightly as Europe and North America ramp up capacity.
However, ensuring sufficient nickel supply will require substantial investment in mining operations and refining capacity across multiple regions.
The potential for supply-demand imbalances remains, as the range of estimates for nickel production varies significantly. For example, the difference between the highest and lowest projections represents about 60% of the current supply, highlighting the uncertainty in meeting future demand.
Market conditions, regulatory frameworks, and technological advancements will all play a role in determining how much of this projected supply will be realized by 2030.
The transition to electric vehicles is reshaping the global demand for battery materials, with nickel emerging as a critical component. Its role in enhancing battery energy density makes it indispensable for long-range EVs and larger vehicles like trucks. As global EV adoption surges, the demand for nickel is set to increase, requiring a corresponding expansion in supply to prevent shortages that could slow down the energy transition.
Uranium prices may have dropped recently, but the long-term outlook for this critical energy resource is glowing. With game-changing technologies on the horizon and new uranium projects underway, the market is on for an exciting comeback.
The uranium market has seen recent short-term pressure, with spot prices falling below $80 per pound after peaking at $107 in February. Despite this decline, uranium prices remain 30% higher than last year, providing significant returns for producers, according to new analysis from BMO Capital Markets.
The World Nuclear Association Symposium in London has highlighted mixed market signals, particularly supply chain issues and delays. These are currently affecting the overall sentiment, noted BMO analyst Alexander Pearce in a market commentary.
Uranium Spot Prices Dip, Long-Term Demand Surges
Although spot prices have softened, BMO Capital Markets projects a strong outlook for uranium demand. The investment banking subsidiary of BMO projected it to grow at an annual rate of 2.9% through 2035. This increase is largely driven by China’s aggressive push to build new nuclear reactors and the potential for reactor restarts in North America.
China, which is investing heavily in nuclear energy as a cleaner alternative to coal, is expected to be a major player in the global uranium market.
Pearce emphasized the long-term demand outlook noting that they foresee a potentially higher uranium demand over the medium to long term. This optimism is fueled by several factors, including:
geopolitical shifts,
growing global demand for clean energy, and
new nuclear technologies such as small modular reactors (SMRs).
Supply Chain Challenges and Growth Projections
On the supply side, BMO anticipates 2024 will see the first significant increase in uranium supply in years. This growth is expected to come from older uranium projects catching up with rising demand.
While uranium prices remain below the peak seen earlier in 2024, the general trend suggests a robust market with significant upside potential, particularly as nuclear energy plays an increasingly vital role in global energy strategies.
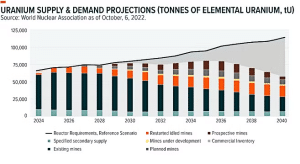
The World Nuclear Association estimated that demand will continue to increase by 2040 while supply will be limited. Thus, there would be a big gap between the metal’s supply and demand requirements by that year.
The Role of Advanced Nuclear Technologies
Oklo, a Sam Altman’s nuclear power startup, is spearheading the development of SMRs. The California-based nuclear company highlighted the growing importance of advanced nuclear technologies in meeting rising energy needs.
In an interview, Brian Gitt, Oklo’s head of business development emphasized the urgent need for reliable, clean energy sources, particularly for energy-intensive industries like data centers and manufacturing. Gitt specifically stated that:
“We’re seeing two big trends: rising power demand and the need for clean energy.”
SMRs are emerging as a flexible and efficient solution for power generation, particularly in areas with high energy demand. By placing SMRs close to energy-hungry facilities, companies can avoid the long waits associated with grid expansion, providing faster and more localized energy solutions.
While still in the development phase, SMRs hold promise for revolutionizing how nuclear energy is deployed, offering a cleaner and more sustainable option compared to traditional power plants. However, the widespread commercial adoption of SMRs is still a few years away.
Gitt acknowledged this, stating that while the technology shows great promise, its impact remains largely theoretical at this stage. Yet, the continued development of SMRs is seen as crucial to addressing future energy needs. This is particularly true as traditional energy sources like natural gas and coal face increasing regulatory challenges and environmental concerns.
The U.S. Revives Its Nuclear Future with Oak Ridge Mega Project
While the debate over energy policy continues, it is clear that nuclear power—both in its traditional form and through new technologies like SMRs—has a crucial role to play in the future of global energy.
Just recently, in a significant development for the energy sector, French company Orano USA announced plans to build a multibillion-dollar uranium enrichment facility in Oak Ridge, Tennessee. This investment marks the largest single capital infusion in Tennessee’s history that can revitalize the region’s role as a leader in nuclear innovation. Commentators considered this as reminiscent of the Manhattan Project during World War II.
Orano USA specializes in the uranium supply chain and nuclear fuel cycle services. This new Oak Ridge facility will focus on producing low-enriched uranium for commercial nuclear reactors, unlike the highly enriched uranium once used for weapons. The 920-acre site will house a 750,000-square-foot multi-structure plant.
Congress recently allocated $2.8 billion to support domestic uranium enrichment, and Orano USA will tap into these funds. The company’s investment symbolizes the beginning of what many are calling the “second Manhattan Project,” as Oak Ridge once again takes center stage in the race to advance nuclear technology.
Oak Ridge, often referred to as the “Secret City,” is now a hub for more than 150 nuclear companies. These include NANO Nuclear Energy and Kairos Power, both of which are building advanced reactors in the area.
Uranium and Nuclear at the Forefront of Clean Energy
The announcement comes amid growing concerns over the U.S.’s ability to compete with China and Russia in both nuclear power and weapons technology. While China continues to expand its nuclear capabilities and Russia remains a dominant player in uranium enrichment, the U.S. has seen a resurgence in nuclear research and development.
As countries look for ways to meet their growing energy needs while reducing carbon emissions, uranium and nuclear technology are likely to remain at the forefront of this conversation.
BMO Capital Markets’ analysis shows that the demand for uranium will continue to rise. While supply-side challenges remain, the potential for significant uranium production growth offers hope for balancing demand. With recent market development, the future of uranium looks bright, offering solutions to the world’s energy challenges.
ADNOC, the UAE’s leading energy company, has completed its acquisition of OCI Global’s majority stake in Fertiglobe. Now ADNOC has 86.2% ownership of Fertiglobe, with 13.8% remaining publicly traded on the Abu Dhabi Securities Exchange (ADX). The acquisition marks a critical step in ADNOC’s strategy to dominate the global low-carbon ammonia market and further its ambitions in chemicals.
Dr. Sultan Ahmed Al Jaber, ADNOC’s Managing Director and Group CEO, highlighted the importance of this acquisition, stating,
“ADNOC’s majority shareholding in Fertiglobe marks another milestone in the delivery of our ambitious international chemicals growth strategy and goal to become a top five chemicals player. Fertiglobe will be the vehicle through which ADNOC advances its low-carbon ammonia business, supporting our efforts to enable a just, orderly, and equitable global energy transition.”
Fertiglobe: A Rising Power in Low-Carbon Ammonia
Ammonia is a key solution for decarbonizing industries like marine fuel, power, and agriculture, which account for 80% of global emissions.
Fertiglobe, the world’s largest seaborne exporter of urea and ammonia, is a strategic asset in ADNOC’s chemical growth. It exports nitrogen products to 53 countries and holds a 10% share of global ammonia and urea trade. Last year, the company shipped its first batch of ISCC PLUS-certified renewable ammonia from Egypt. This clean product will help produce near-zero emissions soda ash for Unilever in India.
Additionally, the company has delivered several low-carbon ammonia shipments from the UAE, using hydrogen and carbon capture technology. Its renewable ammonia cuts emissions by 73%, accelerating the shift to cleaner energy.
Fertiglobe recently achieved a major milestone by securing a €397 million renewable ammonia offtake contract through the H2Global initiative. This contract is valid till 2033.
Talking about the acquisition, ADNOC plans to integrate its stakes in existing and upcoming low-carbon ammonia projects into Fertiglobe.
Significantly, this includes two major projects in Abu Dhabi, which will add 2 million tons per annum (mtpa) to Fertiglobe’s ammonia capacity. The company’s total capacity will increase from 1.6 mtpa to 8.6 mtpa, with more projects in the pipeline.
Thus, with ADNOC’s backing, Fertiglobe can become one of the top five global leaders in chemicals markets and low-carbon ammonia production, which is a key fuel in the energy transition.
Fertiglobe will continue its expansion under the leadership of CEO Ahmed El-Hoshy, who has been instrumental in building OCI’s ammonia and methanol business in the U.S. and Europe. He will lead the next expansion phase of Fertiglobe. The company’s current management team will remain intact as ADNOC rolls out the new strategy.
Moving on, Ahmed El-Hoshy, also highlighted the strategic importance of this move. He said,
“This transaction reinforces our long-term outlook and ambition to meet global demand for low-carbon solutions. As part of ADNOC’s ecosystem, we are excited to unlock the full potential of our portfolio.”
Low-Carbon Fuels and Renewable Ammonia Expansion
Industry experts predict demand for low-carbon ammonia will grow to 24 million tons by 2032 and Fertiglobe is just capitalizing on this demand. It will further help ADNOC reach its target of capturing 5% of the global low-carbon hydrogen market by 2030.
This aligns with the UAE’s National Hydrogen Strategy. The company plans to unveil a detailed growth strategy during its Capital Markets Day in Q1 2025, outlining its roadmap for further expansion and innovation.
ADNOC’s Sustainability Milestones
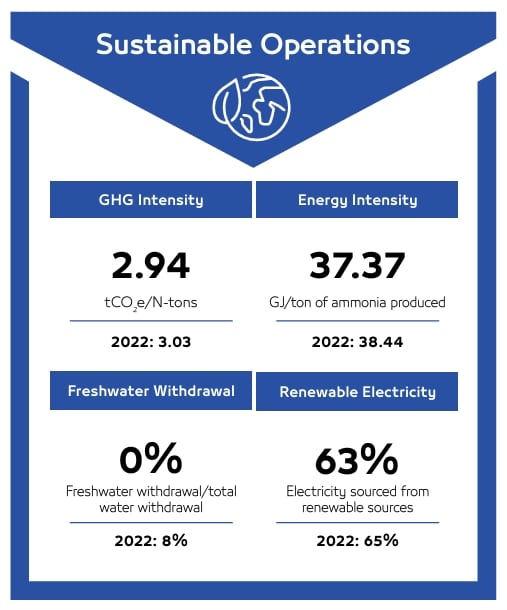
We discovered from the company’s sustainability report that ADNOC is allocating $15 billion (AED 55 billion) to invest in various decarbonization projects, including carbon capture, electrification, new CO₂ absorption technology, hydrogen, and renewables.
This investment will increase to $23 billion (AED 84.4 billion) in early 2024. Additionally, the company has raised its carbon capture capacity target to 10 mtpa by 2030. This is 2x its previous goal of 5 million tonnes.
Source: ADNOC
By 2025, ADNOC aims to improve energy efficiency by 5% (based on 2018 levels) and keep upstream methane intensity below 0.15%.
By 2030, it plans to produce 1 million tons of low-carbon ammonia annually, reduce operational emissions intensity by 25% (compared to 2019), and safely sequester 10 million tons of CO₂ per year. ADNOC is also targeting a 5% share of the global low-carbon hydrogen market and near-zero methane emissions in its operations.
By 2045, the company plans to deploy 100 GW of renewable energy capacity through Masdar, eliminate routine flaring, and achieve net zero operational emissions.
In summary, ADNOC’s acquisition positions Fertiglobe to lead in the low-carbon ammonia market. The plan holds immense promise for sustainable energy growth in UAE and international markets while delivering long-term value to shareholders.
Sibanye-Stillwater, the multinational mining and metals giant entangled in a major legal battle with Appian Capital Advisory. This case stems from a deal worth $1.2 billion that was abruptly terminated in January 2022.
The ongoing proceedings, which are being heard in the High Court of England and Wales, revolve around the acquisition of two Brazilian mines: Santa Rita, a nickel mine, and Serrote, a copper mine. Notably, the former is one of the rare nickel sulfide mines that is still operating. It also produces copper, cobalt, and platinum group metals as by-products.
Sibanye’s decision to withdraw from the deal has led to accusations and legal claims for compensation by Appian. As both sides prepare for the next phase of the case in November 2025, the stakes are high, with claims that could exceed $600 million, as reported by MINING.COM
The Massive $1.2B Deal and Its Collapse
Going back in time, in October 2021, Sibanye-Stillwater struck a $1.2 billion deal with Appian to acquire the Santa Rita and Serrote mines. These assets are owned by Atlantic Nickel and Mineração Vale Verde. Appian’s funds were meant to strengthen Sibanye’s stock of critical metals. The latter was looking to shift its focus from platinum and gold to new opportunities.
Notably, Sibanye-Stillwater had robust plans to expand into battery metals like nickel and copper which are the most essential for the fast-growing electric vehicle (EV) market.
However, just three months later, Sibanye-Stillwater terminated the share purchase agreements (SPAs), citing a “geotechnical event” at the Santa Rita mine as the primary reason. The mining company cited the event as significantly impacting future operations and used it to justify backing out of the deal. Appian, however, claimed that the event was minor and did not justify the termination of the agreements, leading to the start of legal proceedings in 2022.
The first stage of the legal battle began in June 2024 and centered on whether the geotechnical event could be reasonably expected to have a material and adverse impact on Santa Rita’s operations. After a five-week trial, Justice Butcher ruled in October 2024 that Sibanye was not justified in terminating the SPAs.
The press release revealed that, according to the judgment, the geotechnical event at Santa Rita was neither as material nor as adverse as Sibanye claimed, meaning the company had no right to withdraw from the deal based on this event.
However, Sibanye achieved a partial victory in the ruling. The court dismissed Appian’s claim of “wilful misconduct”, with the judge acknowledging that Sibanye’s management genuinely believed they were acting in the company’s best interest. This ruling suggests that while Sibanye’s reasoning was flawed, the company did not act with malicious intent.
Appian’s Compensation Claims and Initiation of the Quantum Trial
Appian is now pursuing compensation for the failed deal. The company initially sought $522 million in damages but has indicated that the total claim could exceed $600 million, including interest and legal costs. These figures represent the difference between the agreed purchase price and the mines’ current market value, alongside expenses incurred during the resale process.
Appian further pressed that Sibanye’s termination caused substantial financial losses, and they aimed to recover the full amount.
The legal battle is far from over, as the case now moves into the second phase—a trial scheduled for November 2025. This trial, known as the Quantum Trial, will determine the exact amount of damages Sibanye will be required to pay, if any. Appian argues that they would have sold the mines to another buyer for a similar price if the deal had not fallen through.
However, Sibanye maintains that Appian received multiple offers for the mines after the deal’s collapse and, therefore, cannot claim that they suffered a significant financial loss.
Sibanye’s position in the Quantum Trial is that Appian failed to mitigate its losses. Under English contract law, a party seeking compensation is required to take reasonable steps to reduce the damages they incur. Sibanye argues that Appian could have, and should have, sold the mines at fair market value soon after the deal was terminated. The company also asserts that Appian’s continuing ownership of the mines may have resulted in profits, which would reduce the overall damages they could claim.
High Stakes for Sibanye-Stillwater, Will Nickel Pay Off?
The legal battle with Appian comes at a difficult time for Sibanye-Stillwater. Leading media agencies reported that CEO Neal Froneman is already grappling with declining prices for platinum group metals, which has put additional pressure on the company’s financial performance.
As Sibanye seeks to diversify its portfolio and reduce its reliance on these traditional metals, the outcome of the trial could have significant implications for the company’s strategic direction.
Sibanye-Stillwater’s expansion into battery metals is a crucial part of its growth strategy. The company has made several moves in recent years to acquire assets in this sector, including its initial attempt to purchase Appian’s Brazilian mines.
However, the collapse of this deal has forced Sibanye to explore other opportunities. Analysts have noted that the prices of nickel, copper, and other battery metals have risen sharply in recent years, making it more challenging to find affordable assets.
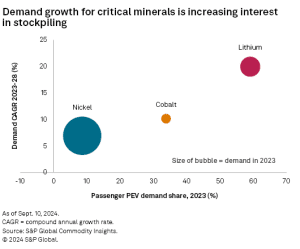
Nickel, in particular, is increasingly important for the production of lithium-ion batteries used in electric vehicles. However, miners and market experts predict that the demand for nickel and other critical metals will certainly surge with the EV boom.
This leads to the most inevitable scrutiny- can Sibanye-Stillwater’s ability to secure access to these materials propel its growth in the battery metals market in the future?
Image: Nickel Demand from EV and Other Applications, 2022-2030
Source: IRENA report
Appian vs. Sibanye: The Final Verdict Looms
As both parties prepare for the Quantum Trial in November 2025, investors and industry experts will closely watch the case’s outcome. For Appian, a successful claim could result in a massive payout. But Sibanye hopes to reduce or eliminate the potential damages.
In the meantime, the Brazilian mines in question continue to operate, with Santa Rita transitioning from open-pit to underground operations. This transition to high-grade nickel can potentially extend the mine’s life by over 20 years. Alternatively, it significantly highlights the ongoing value of these assets and the high stakes involved in this legal battle.
Sibanye-Stillwater now shifts its focus to defending its position in court. This means it will continue to argue that Appian’s claims are exaggerated. However, the company will pursue new battery metal assets, but finding affordable, high-quality projects remains challenging. As the verdict nears, both parties will brace for one of the mining sector’s biggest compensation rulings in years. Fingers crossed!
The American Forest Foundation (AFF) is set to launch a groundbreaking carbon auction in February 2025, focusing on carbon credits generated through its Family Forest Carbon Program (FFCP).
This initiative aims to offer companies a streamlined and transparent process to purchase high-quality nature-based carbon credits. At the same time, it will also provide support for rural communities and family forest owners.
Unlocking Nature’s Carbon Potential with Carbon Credits
As more companies work towards reducing their carbon footprints, there’s a pressing need for upfront financing to implement nature-based carbon projects that meet global climate goals. Nature-based solutions, which leverage natural ecosystems like forests to sequester carbon, have significant potential but remain underfunded.
Currently, only 1.2% of the annual potential of these solutions has been tapped through the voluntary carbon market (VCM). This underinvestment is a key barrier to reaching climate-mitigation targets and keeping global temperature rise below 1.5°C.
Moreover, prices of nature-based carbon offset credits have been plunging and falling below $1.0/ton since July this year.
The AFF Carbon Auction aims to bridge the funding gap by providing upfront payments. This approach enables project developers to kickstart their initiatives, ensuring a steady supply of high-quality carbon credits, that contribute to climate resilience. By linking payments to the progress of projects, the auction model will align corporate investments with tangible climate impacts.
How the Auction Works
The auction process is designed to simplify how companies buy carbon credits. All necessary due diligence resources will be available in one centralized location, allowing companies to review information over several weeks before the bidding period.
During the one-week auction in February, companies will place bids on the credits they wish to purchase. This approach will provide a transparent view of the market and competitive pricing.
Additionally, the FFCP benefits from this structure by gaining the upfront funding needed to scale its carbon-saving projects.
Redefining Investment in Nature-Based Solutions
The AFF Carbon Auction introduces a novel approach to financing nature-based carbon projects through hybrid commercial terms. Traditional carbon credit purchases often involve payment upon delivery, which can delay project initiation.
However, the auction will offer partial upfront payments, allowing buyers to secure credits at a discount while providing developers with the capital they need to get started.
This method will enable companies to tie their investments to specific milestones, such as the number of acres enrolled in the program and successful verification steps. Such down payments help ensure that projects deliver measurable environmental and community benefits.
Buyers also benefit from this model by securing carbon credits at competitive prices, protecting themselves from potential future price increases while contributing to long-term decarbonization goals. Major companies like Google are massively investing in nature-based carbon removal solutions.
According to the International Union for Conservation of Nature and Natural Resources, nature-based solutions could contribute 30% of the global mitigation by 2030 to achieve the critical temperature rise goal of the Paris Agreement. They also have the potential to achieve emission reductions and removals of at least 5 GtCO2e per year by 2030, out of a maximum estimated potential of 11.7 GtCO2e per year.
When the AFF auction begins in February, both removal and emission reduction credits will be up for bidding, with removal credits making up the majority. Buyers will have the opportunity to place bids on four different terms:
Empowering Small Landowners
A central goal of the AFF’s Family Forest Carbon Program is to empower small landowners to take part in climate action. This partnership between AFF and The Nature Conservancy ensures that funding flows to forest owners who are implementing sustainable practices.
Tim Stout, a Vermont landowner enrolled in the FFCP, highlighted the importance of such initiatives in his mission to protect forests and combat climate change. He further highlighted that, with the right support, landowners have a remarkable capacity to make a difference.
The FFCP provides technical assistance and financial incentives to help small landowners manage their forests for optimal carbon storage. This approach not only captures carbon but also delivers ecological co-benefits like:
improved water quality,
enhanced biodiversity, and
more resilient woodlands.
Reshaping the Voluntary Carbon Market
The AFF’s upcoming auction could help reshape the VCM in the United States by addressing key barriers to investment in nature-based solutions. Traditionally, buyers have been hesitant to provide upfront capital, creating a funding gap that delays project implementation. By offering a more direct and efficient way to secure credits, the AFF aims to make it easier for companies to participate in meaningful climate action.
Kevin Maddaford, director of US and Canada Carbon Markets at The Nature Conservancy, remarked:
“This groundbreaking auction will redefine how corporations invest in nature-based solutions to address the threats of climate change and biodiversity loss.”
The auction’s design also provides incentives for early investment, helping to secure the future of the carbon market. By offering discounts on credits for companies that prepay, the auction encourages buyers to commit to projects sooner rather than later.
The AFF’s Carbon Auction represents a pivotal moment in the evolution of corporate climate action, transforming the landscape of nature-based carbon credit projects in the country. By offering a transparent and efficient pathway for companies to invest in nature-based solutions, the auction has the potential to close the funding gap that has hindered the growth of the VCM.
Amazon is diving deep into nuclear power as part of its ambitious data center expansion plan, investing over $52 billion across three U.S. states. The e-commerce giant has inked 3 key deals to explore and develop small modular reactors (SMRs).
SMRs are a new type of nuclear technology that promises more efficient, compact, and clean power generation. AWS CEO Matt Garman noted that SMRs present unique potential to provide scalable and reliable power to meet the ever-growing energy needs of data centers.
Shares of nuclear companies surged following Amazon’s announcement of the agreements. Nano Nuclear Energy and Nuscale Power saw their shares rise nearly 10% in premarket trading, while Oklo experienced an over 11% increase.
SMRs are advanced nuclear reactors designed to be less than 10% of the size of traditional nuclear plants. But they can generate up to about ⅓ of the power output of traditional reactors. As such, they allow for easier deployment and integration into the energy grid.
Developers aim to have these reactors generating electricity by the early 2030s, contingent on receiving approval from the Nuclear Regulatory Commission (NRC) to build and operate their designs, as well as proving the technology’s viability.
Amazon’s most recent collaboration with Dominion Energy, a $48 billion market-cap utility company, aims to explore the deployment of SMRs in Virginia near Dominion’s North Anna power station in Louisa County.
Virginia hosts nearly half of all U.S. data centers, with a significant concentration in Northern Virginia, particularly in the Data Center Alley, located in Loudoun County. It is estimated that 70% of the world’s internet traffic passes through Data Center Alley each day.
The region has experienced a doubling of power demand over the last 5 years. It is also projected to see a 4x increase over the next 15 years. The planned SMR could contribute at least 300 megawatts of power, which could support multiple data centers in the region.
AWS has committed to investing $35 billion by 2040 to develop multiple data center campuses across Virginia, as announced by Governor Youngkin last year.
Nuclear Meets the Cloud: Dominion, X-Energy, and Amazon
Garman emphasized that the push for nuclear is part of Amazon’s broader goal of achieving net-zero emissions by 2040. He noted that:
“We see the need for gigawatts of power in the coming years, and there’s not going to be enough wind and solar projects to be able to meet the needs, and so nuclear is a great opportunity.”
The specific targets for nuclear’s contribution to AWS’s power needs remain undisclosed. But Garman noted that Amazon hopes SMRs will be a “material source of power generation” by 2040.
Alongside the Dominion deal, Amazon announced agreements to develop SMRs in Washington state with Energy Northwest, a public power agency, and to back X-energy, an advanced nuclear startup.
X-energy is building its first SMR project in Seadrift, Texas, in collaboration with Dow Chemical. Amazon is providing significant financial support to X-energy, anchoring a $500 million investment through its Climate Pledge Fund. This commitment aims to bring 5 gigawatts of SMR-based energy online across the U.S. by 2039.
Why Small Modular Reactors?
The said SMRs could power entire mid-sized cities, but for Amazon, they’re integral to supporting the energy-intensive demands of data centers, especially those driven by artificial intelligence (AI). Data centers require stable and continuous energy supplies, something that SMRs, unlike intermittent renewable sources like wind or solar, can reliably offer.
With capacities of up to 300 megawatts, SMRs can be tailored to meet local energy demands, making them suitable for data centers and other energy-intensive operations. X-energy’s Xe-100 reactor, for example, can produce 80 megawatts of power per unit, with the flexibility to scale up by deploying multiple reactors at a single site.
Another key advantage is the carbon-free nature of nuclear power, aligning with Amazon’s goal of reducing its environmental impact. Unlike fossil fuels, nuclear energy does not produce greenhouse gas emissions during operation. Thus, it offers a reliable solution for tech companies seeking to curb their carbon footprints.
AWS, like its peers, is committed to cutting emissions, but it has faced challenges. In 2023, Amazon’s carbon footprint was just under 69 million metric tons of CO2, slightly lower than its peak in 2021 but still substantial.
Beyond its partnership with Dominion in Virginia, Amazon is also eyeing other regions for SMR projects. In Washington, it is collaborating with Energy Northwest to build an SMR near the Columbia Generating Station in Richland. This project aims to provide up to 960 megawatts of power, with Amazon securing the rights to purchase electricity from the first 320 megawatts produced.
This flexibility makes SMRs appealing for scaling energy projects across different regions. It enables Amazon to replicate its nuclear model wherever energy demand is high. AWS recently acquired a 960-megawatt data center campus in Pennsylvania from Talen Energy, which includes access to fixed-price nuclear power from Talen’s Susquehanna nuclear plant.
Amazon’s venture into nuclear power mirrors a broader industry trend. Google recently announced its own SMR project with Kairos Power. Similarly, Constellation Energy is planning to restart operations at the iconic Three Mile Island to power Microsoft’s data centers. Sundar Pichai, Google’s CEO, expressed optimism about the potential of SMRs, highlighting the surge of capital and innovation driving the technology forward.
X-energy CEO Clay Sell sees a significant opportunity in this trend, noting that demand for nuclear energy, especially in the context of AI’s energy requirements, is reshaping how companies think about power in the U.S.
The Biden administration has invested billions into clean energy initiatives. As part of Amazon Web Services’ recent announcement, U.S. Energy Secretary Jennifer Granholm revealed that an additional $900 million in funding is now available for projects aiming to deploy SMRs. This funding supports the broader push to accelerate clean and reliable energy solutions across the nation.
For Amazon, SMRs represent a promising path forward. While the journey to widespread deployment of advanced nuclear technology is fraught with challenges, the potential payoff—a more resilient, sustainable energy future—makes the effort worthwhile.
Earlier this month, CarbonCredits reported that Sundar Pichai, Google’s CEO, hinted at the possibility of using nuclear energy to help the company reach its ambitious 2030 net-zero emissions target. Confirming those hints, Google officially announced on October 14 a groundbreaking nuclear energy agreement with Kairos Power.
This milestone isn’t just about power. It’s about accelerating a global clean energy transition, ensuring that nuclear becomes a key player in the fight against climate change.
Google Teams Up with Kairos to Tackle Rising Emissions
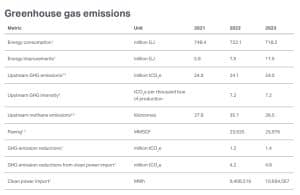
Google’s push for nuclear power comes at a critical time. In 2023, its greenhouse gas (GHG) emissions rose to 14.3 million metric tons of CO2 equivalent (tCO2e), a 13% increase from the previous year and a 48% jump from 2019. This increase was largely driven by higher energy consumption in data centers, AI, and supply chain emissions. As its energy use grows, emissions reduction is going to be more challenging.
Source: Google
Coming to the main segment, the tech giant has signed the world’s first corporate agreement to purchase nuclear power from small modular reactors (SMRs),designed by Kairos Power.
Under this agreement, Kairos Power will develop, build, and operate advanced reactor plants, supplying clean energy to Google through Power Purchase Agreements (PPAs).
Michael Terrell, Google’s Senior Director of Energy and Climate, said
“This landmark announcement will accelerate the transition to clean energy as Google and Kairos Power look to add 500 MW of new 24/7 carbon-free power to U.S. electricity grids. This agreement is a key part of our effort to commercialize and scale the advanced energy technologies we need to reach our net zero and 24/7 carbon-free energy goals and ensure that more communities benefit from clean and affordable power in the future.”
These plants will be strategically located to power Google’s data centers, with the first SMR deployment expected by 2030. More reactors will roll out by 2035.
The multi-plant agreement will boost innovation by advancing Kairos Power’s demonstration plan. Each new plant will help refine and improve the technology. Furthermore, the pre-determined milestones will keep Kairos Power accountable and ensure proper progress throughout the partnership. This approach will also speed up commercialization and build trust over time.
Mike Laufer, CEO and co-founder of Kairos Power remarked,
“Our partnership with Google will enable Kairos Power to quickly advance down the learning curve as we drive toward cost and schedule certainty for our commercial product.By coming alongside in the development phase, Google is more than just a customer. They are a partner who deeply understands our innovative approach and the potential it can deliver.”
Economic Benefits
Industry experts have estimated that the U.S. could potentially create over 375,000 new jobs by achieving 200 GW of advanced nuclear capacity by 2050. Google’s deal with Kairos Power supports this vision by creating jobs in nuclear technology, construction, and energy sectors.
For local communities, this means more than just employment. The presence of nuclear energy infrastructure can foster economic growth while also contributing to the reduction of carbon emissions. In a world of rising energy demand, reliable, clean power isn’t just a solution—it’s also a powerful driver of economic growth.
Uranium Royalty Corp is the first company to apply the successful royalty and streaming business model exclusively to the uranium sector.
With interests in advanced, permitted and producing uranium projects, the company is well positioned as a capital provider to meet the growing need for uranium as fuel for carbon free, nuclear energy. Learn more about Uranium Royalty Corp’s portfolio of royalty assets and uranium holdings.
*** This content was reviewed and approved by Uranium Royalty Corp. and is being disseminated on behalf of Uranium Royalty Corp. by CarbonCredits.com for commercial purposes. ***
Founded in 2016, Kairos Power takes a unique approach to bringing advanced nuclear technology to market. In 2023, the U.S. Nuclear Regulatory Commission granted Kairos Power a construction permit for its Hermes demonstration reactor. This was the first non-water-cooled reactor approved for construction in over 50 years.
By using a rapid, iterative development process and vertical integration, the company is speeding up the deployment of safe and efficient small modular reactors (SMRs). Their reactors feature a molten-salt cooling system and ceramic pebble-type fuel, ensuring better heat transfer to steam turbines for power generation. Operating at low pressure, this system reduces risks and creates safer, more reliable operations.
Additionally, they conduct multiple hardware tests to identify and resolve potential issues before large-scale deployment. Google’s involvement will help speed up this process, leading to quicker and more cost-effective SMR installations across the U.S.
The Kairos Power FHR (KP-FHR): A Novel Advanced Reactor
Well, many consider nuclear energy as complex and slow to develop. However, new reactors, especially like the SMRs from Kairos Power are changing this concept. Their advanced designs are smaller, simpler, and quicker to build, making them easier to deploy in more locations.
The modular design of these reactors allows for scalability. Instead of a one-size-fits-all approach, these smaller units can be addedon to match energy demands. And because they are quicker to build and safer to operate, the timeline to achieving carbon-free energy is shortened significantly. Simply put, the tech giant is investing in nuclear energy that is both safer and more economically viable than traditional reactors.
Secondly, SMRs provide a constant supply of clean energy. Thus, Google believes this partnership is about finding a balance between renewable sources like wind and solar and more constant energy like nuclear, which can ensure reliable power every hour.
Overall, one can infer that this partnership would accelerate clean energy by bringing affordable nuclear power to U.S. grids. As a result, Google can effectively meet rising electricity demands, especially for AI, while advancing its goal of going 24/7 carbon-free energy by 2030.
To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behavior or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.
Functional
Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes.The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.




 Source: IEA

 Source: Lithium Americas