
Climate Week NYC 2026 has put a growing issue in the carbon dioxide removal (CDR) market under the spotlight: Can carbon removal projects actually deliver the tonnes they promise?
As CDR moves from early-stage development toward larger commercial projects, buyers and investors are looking beyond the quality of carbon removal credits. They also want to know whether projects can deliver the contracted volume on time.
This is where delivery risk comes in.
Relae, formerly Carbon Direct, and Microsoft are addressing the issue through the sixth edition of their Criteria for High-Quality Carbon Dioxide Removal. Released during Climate Week, the 2026 framework adds a dedicated approach for assessing delivery risk alongside carbon removal quality for the first time.
The change reflects an important shift in the CDR market. A project can use a credible removal method and meet quality requirements, but that does not automatically mean it will deliver the promised tonnes.
What Is Delivery Risk in Carbon Removal?
Delivery risk is the possibility that a CDR project will fail to produce the amount of carbon removal it has promised or fail to deliver it within the agreed timeframe.
The reasons can extend well beyond the underlying technology. A project could face construction problems, higher-than-expected costs, financing delays, supplier failures, weak project management or regulatory obstacles.
The new Relae-Microsoft framework therefore looks at delivery as a broader project-development challenge.
The TECOP Framework
Its delivery risk assessment covers five areas within a new framework called TECOP. It covers Technical, Economic, Commercial, Organizational, and Political risks.
These factors examine whether a project has the technology, financing, contracts, management capacity, and external conditions needed to move from development to actual carbon removal.
Importantly, the framework distinguishes between open-system and closed-system projects, recognizing that different CDR approaches face different execution risks.
A facility-based project, for example, may depend heavily on construction, equipment, and storage infrastructure, while an open-system project can face risks linked to land, feedstocks, field conditions, and decentralized operations.
This makes delivery risk broader than simply asking whether a technology works.
Why Delivery Risk Matters in the Current CDR Market
The timing of the new framework is significant because the CDR market is entering a more execution-focused phase.
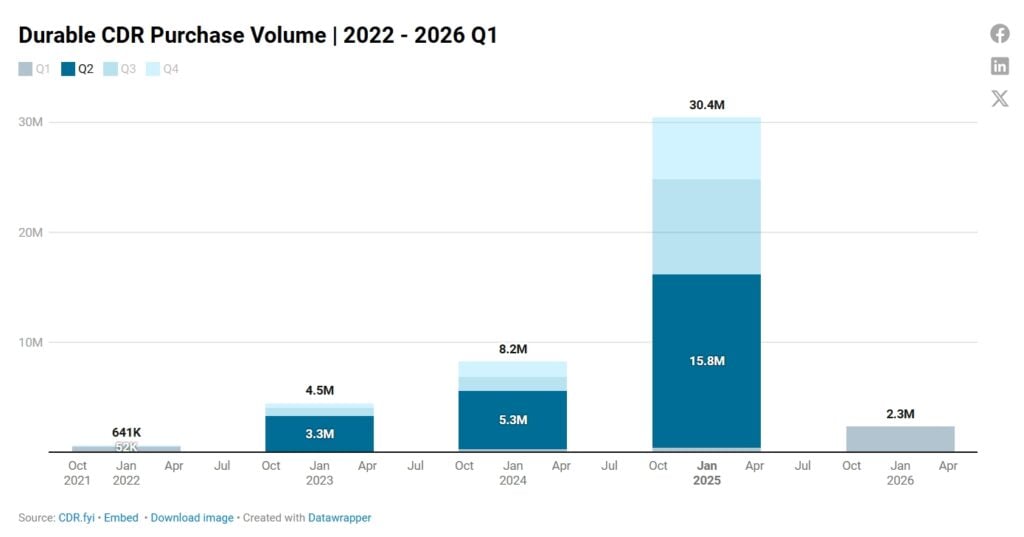
The market expanded rapidly in 2025. CDR offtake volumes reached about 64 million metric tons, more than double the 30 million tonnes recorded in 2024, according to a 2025 market review. Durable CDR accounted for 29 million tonnes of that volume, up from 8 million tonnes a year earlier.
However, contracted tonnes are not the same as delivered tonnes.
- In the first quarter of 2026, durable CDR buyers contracted about 2.3 million tonnes, the strongest first quarter on record. Yet only about 145,000 tonnes were delivered during the quarter.
That gap illustrates why delivery has become a bigger issue for buyers. Developers may announce large future projects and sign long-term offtake agreements years before facilities or removal systems reach full-scale operations.
As commitments become larger, the consequences of delays also increase.
For buyers, delivery risk can affect when credits become available, how they plan their climate strategies and whether contracted tonnes arrive in the quantities expected. For developers, failure to meet commitments can affect financing, customer relationships and future contracts.
Microsoft Shows Both the Scale and Concentration of CDR Demand
Microsoft’s role in the market makes the delivery question particularly important.
The company has contracted more than 78 million metric tons of CDR from more than 60 projects across 10 removal approaches, according to its January 2026 portfolio update. Microsoft said it was increasingly targeting near- to medium-term deliveries while maintaining longer-term purchases linked to its carbon-negative goal beginning in 2030.
This procurement strategy has helped provide developers with long-term demand signals. However, it has also contributed to a highly concentrated market.
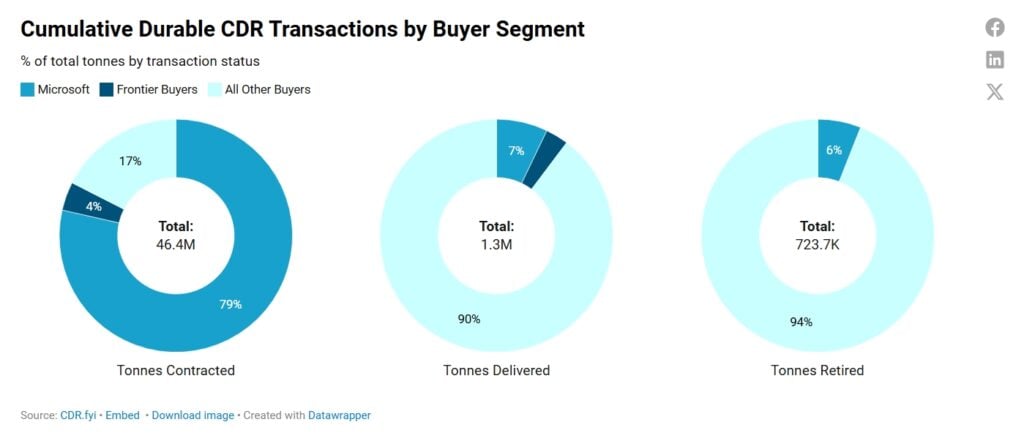
- CDR.fyi estimated in April 2026 that Microsoft accounted for 78.5% of disclosed durable CDR tonnes contracted, equal to more than 36.4 million tonnes.
Diversification of the CDR Market
The market has continued to diversify outside Microsoft. Sylvera reported that disclosed non-Microsoft offtake volume increased 73% year over year in the first half of 2026 to 12 million tonnes, even as total disclosed offtake volumes fell sharply.
That creates an important backdrop for the new delivery framework. CDR developers are not only competing for buyers. They are also moving from contracts and project announcements toward actual construction, operations, verification and delivery.
Relae and Microsoft Have Tracked CDR Quality Since 2021
Relae and Microsoft first introduced the CDR quality criteria in 2021.
The criteria have been updated annually as scientific understanding, project experience and the voluntary carbon market have evolved. The 2026 edition draws on lessons from diligence conducted across hundreds of real-world projects and adds delivery risk as a distinct assessment area.
Relae says it conducted 170 additional diligence reports since the 2025 criteria. Its assessment has now covered more than 900 projects, with fewer than 10% meeting its threshold for high quality. More than 60 subject matter experts contributed to the 2026 update.
The purpose is not to replace the existing quality framework. Instead, delivery risk adds another layer to project assessment.
The basic questions for buyers now become:
- Is the removal scientifically credible?
- Does the project meet quality requirements?
- Can the developer actually deliver the contracted tonnes?
- What could prevent delivery, and how resilient is the project to those risks?
Six Principles Still Define High-Quality CDR
The delivery framework sits alongside the existing quality requirements.
The 2026 criteria continue to assess six core areas across CDR pathways:
- Social harms, benefits and environmental justice
- Environmental harms and benefits
- Additionality and baselines
- Measurement, monitoring, reporting and verification
- Durability
- Leakage
These principles focus on whether the carbon removal is credible and whether the project avoids significant environmental and social harms.
Delivery risk addresses a different part of the equation: whether the project can execute its plan.
This distinction matters because a project can satisfy quality requirements while still facing financing, construction, supply-chain or regulatory problems.
Direct Counterparties Are Part of the Delivery Equation
The updated criteria also place greater attention on direct counterparties.
These are organizations that developers depend on to generate and deliver carbon removal. They can include feedstock suppliers, landowners, transportation companies, storage providers, local implementation partners, and major offtakers.
For many CDR projects, these relationships are essential to the project’s operating model.
A biochar developer, for example, may depend on a consistent supply of biomass. A geological storage project may rely on transportation and injection infrastructure. Nature-based projects can depend on landowners and local implementation partners.
The 2026 criteria therefore call for greater due diligence on these relationships and consideration of whether counterparties could introduce social or environmental risks.
This expands project assessment beyond the company selling the carbon removal.
CDR Pathways Face More Detailed Scrutiny
The updated criteria also increase the level of scrutiny for individual CDR pathways.
- Enhanced rock weathering (ERW) faces stronger requirements around measuring actual carbon removal, managing potentially toxic elements, and protecting farmers. Projects are expected to use physical field measurements rather than relying solely on modeled results.
- Afforestation, reforestation and revegetation (ARR) projects face updated requirements around dynamic baselines and statistically matched controls. These changes are intended to improve confidence that measured removals represent genuine additional climate benefits rather than changes that would have occurred without the project.
The framework therefore continues to evolve alongside the technologies it evaluates.
The Next Phase: From CDR Commitments to CDR Delivery
The biggest change in the market may be the growing importance of the gap between contracted tonnes and delivered tonnes.
CDR.fyi’s 2026 data shows that buyers outside Microsoft and Frontier accounted for only a minority of contracted durable CDR volumes but a much larger share of deliveries and retirements to date. This suggests that market activity looks different when measured by actual delivered tonnes rather than future commitments.
The trend also helps explain why delivery risk is becoming more important as the sector matures.
Large CDR contracts can provide developers with revenue visibility and help unlock project financing. But those contracts also create expectations around timing and volume.
The market now needs to demonstrate that contracted tonnes can move through the entire chain: project development, financing, construction, operation, measurement, verification and delivery.
Relae and Microsoft’s framework does not guarantee that a project will meet those milestones. Instead, it gives developers, buyers and investors a structured way to identify potential weaknesses before they become delivery failures.
For the CDR industry, that represents a shift from asking whether carbon removal can work in principle to asking whether projects can execute at commercial scale.
The discussion at Climate Week NYC reflects this next phase. Carbon removal is no longer only about developing better technologies or securing large offtake agreements. It is increasingly about building projects that can deliver measurable, durable, and high-quality tonnes at the scale and time promised.