Whatโ€™s Shaping North America’s Natural Gas in 2024? Insights from Wood Mackenzie

The natural gas market has immensely benefitted this year from robust storage levels and stabilized prices after the sharp spikes of 2022. However, challenges such as volatile pricing, seasonal demand fluctuations, and supply-demand imbalances persist. The emergence of renewable natural gas (RNG) and LNG export projects reflects ongoing structural shifts in this dynamic energy landscape of North America.

Industry experts predict that the North American natural gas market is projected to grow at a 5% CAGR between 2022 and 2027. This will be driven primarily by increasing industrial demand from the refining, petrochemical, and fertilizer sectors.

Winter 2024: What Will Drive North Americaโ€™s Natural Gas Markets?

Apart from production levels and storage capacity, the North American natural gas market is also shaped by power market trends, LNG exports, imports, and changing weather patterns. But which of these will play the most critical role in the upcoming season? Letโ€™s study the Wood Mackenzie findingsโ€ฆ

Cold Snaps Impact Demand and Supply

Changing weather conditions significantly impact the natural gas market. And this is the direct effect of climate change. Cold snaps not only just spike demand, they also disrupt supply. Freeze-offs, where water or liquids in gas wells solidify and block production, are a recurring issue in North America.

Wood Mac reports that historically, these events have reduced about 0.7% of Lower 48 output during winter. However, losses vary and depend on the location and intensity of the cold. These disruptions are most critical because they hit supply when demand peaks.

LNG Exports Fluctuate Gas Price

LNG exports are driving growth in the U.S. gas market, with new projects like Venture Globalโ€™s Plaquemines in Louisiana and Cheniere Energyโ€™s Corpus Christi expansion boosting capacity. However, this surge constricts domestic gas supplies, especially when demand is at its highest level.

For instance, natural gas inflows for LNG exports dropped from 15 billion cubic feet per day (bcfd) to 7 bcfd to meet local needs due to severe cold this January. This shortage drove Henry Hub prices to $13, with some regions experiencing even higher spikes. This showed that LNG exports are increasingly acting as “synthetic storage,” thereby balancing supply when stored gas falls short.

Production Choices May Strain the Supply

North American natural gas producers are increasingly managing supply through proactive decisions. Companies like EQT and Expand Energy (formerly Chesapeake Energy) have found strategic ways to adjust the supply based on market price.

Some techniques like delaying the activation of new wells or turning existing wells on and off can transform gas production into “synthetic storage“. However, this widely adopted approach is expected to still keep markets unpredictable this winter.

Renewables Fuel Demand Volatility

Natural gas demand for electricity generation has also become more unpredictable. Several factors influence this surge, including the retirement of coal plants, low gas prices fueling coal-to-gas switching, and an overall increase in power load.

Power generation during summer hit a record high of 58 bcfdย of gas, surpassing 50% of the total U.S. production of just over 100 bcfd. Last winter, demand also peaked at a record 44 bcfd, reflecting a year-round trend.
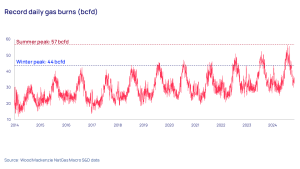
natural gas burns north america

However, renewable energy plays a key role in the power sector. Simply put, during summer solar availability is high, while wind power is low and itโ€™s just the opposite during winter. These fluctuations increase reliance on natural gas during extreme weather.

Storage Shortfalls and Supply Concerns

Storage capacity acts as a buffer during high demand or low supply. The report revealed that in recent years, storage capacity was limited. This was mainly due to narrow summer-winter price spreads which offered very minimal commissioning to set up new storage facilities. The planned 50 billion cubic feet of capacity falls short of market needs.

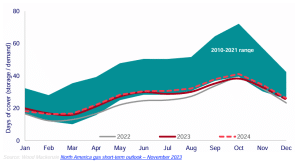
The demand for stored gas remains substantially high during peak winters like in January 2024 which led to 64 bcfd withdrawals. Conversely, the “days of cover” metric, measuring storage relative to demand, remains low in the cold. Thus, raising supply concerns.
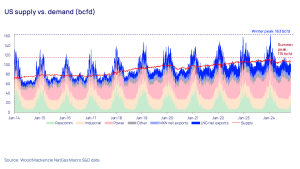
natural gas supply vs demand

Price Volatility

We can comprehend now that North Americaโ€™s natural gas market faces significant instability due to storage-related struggles. However, this year storage inventories showed a 10% surplus compared to the five-year average which caused a sharp price drop in Henry Hub gas prices.

Despite this surplus, long-term storage capacity lags behind market expansion. Currently, U.S. storage covers only 25 days of full demandโ€”a historic low. Without significant expansion, volatile prices could dominate the years ahead.

US L48 storage represented as days of demand cover
natural gas price

North Americaโ€™s Natural Gas Market: Opportunities Amid Challenges

We have studied the challenges that North Americaโ€™s gas market faces but at the same time, it has transformed significantly tapping the opportunities that lie ahead. Quite evidently, natural gas will play a vital role while replacing coal and renewables, bolstering the energy mix.

Several ongoing and upcoming projects will expand capacity and address the challenges related to price, demand, and supply of natural gas.

Renewable Natural Gas Gains Momentum

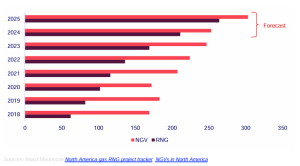
Renewable Natural Gas (RNG) has emerged as a promising tool for decarbonization. Supported by policies like California’s Renewable Gas Standard, RNG production is growing, with 324 projects in operation across the U.S. and Canada.

In 2024, demand-side contracting is expected to gain traction, particularly in hard-to-decarbonize sectors and heavy-duty transportation. Companies like Walmart and UPS are already testing RNG-powered fleets which signals a transition toward sustainable fuel solutions.

North American gas RNG production and NGV demand
wood mackenzie Natural gas

LNG Export Boom: North America’s Next Wave

With rising U.S. and Canadian gas production and storage levels hitting highs in 2023, the North American gas market eagerly waits for the upcoming LNG export projects. While the timelines for large-scale terminals like Plaquemines and Golden Pass are well-known, the impact of this new demand surge remains uncertain.

Low gas prices have recently discouraged production growth. However, forward price projections showing premiums of up to $4/mmbtu for late 2024 and 2025 signal more lucrative returns when this demand kicks in.

Some promising LNG projects in North America include Plaquemines LNG Phase 1ย in Louisiana, Golden Pass LNG, Theย Corpus Christi, Fast Altamira FLNG projectย in Mexico,ย LNG Canada, etc.

These developments highlight the growing structural demand for LNG across North America and beyond. While challenges persist, the regionโ€™s LNG export potential is poised to reshape global energy markets.

All in all, natural gas continues to be pivotal for North Americaโ€™s energy system. However, itโ€™s crucial to tackle challenges like weather, limited storage, redundant infrastructure, and the need to integrate renewables smoothly. So, overcoming these hurdles will be key to ensuring the sectorโ€™s growth and stability in the future.

Sources:

  1. Woodmac: North America Gas: 5 things to look for in 2024ย ย 
  2. 5 factors affecting North American natural gas markets this winter | Wood Mackenzie

Rio Tinto-Backed Lithium Startup’s $18M Funding: How Can It Revolutionize the Industry?

With 85 million electric vehicles (EVs) expected on the road by 2025, the demand for lithium is skyrocketing. However, traditional lithium extraction methods pose serious environmental risks. They deplete water supplies, contaminate ecosystems with chemicals, and rely heavily on energy-intensive mining processes that expand the carbon footprint.

ElectraLith, a Melbourne-based startup backed by Rio Tinto, is tackling these issues with its Direct Lithium Extraction (DLE) technology. This innovative process bypasses the need for water and chemicals, extracting lithium directly from brine solutions.ย 

The lithium tech startup is set to conclude a funding round worth A$27.5 million (almost $18 million) next week to support its global growth initiatives. CEO Charlie McGill confirmed the plans, as reported by Reuters.

ElectraLithโ€™s Game-Changing Lithium Technology

Traditional lithium production can take months and devastate water-stressed regions like Chileโ€™s Atacama Desert. ElectraLithโ€™s proprietary DLE-R technology completes the process in hours, drastically cutting production time and environmental costs.ย 

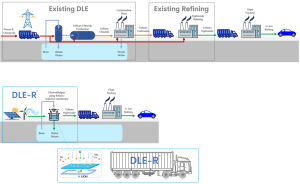
ElectraLith DLE-R Technology

Direct Lithium Extraction DLE-R
Image from ElectraLith

The tech’s advanced filtration membranes convert lithium into lithium hydroxide while reinjecting unused brine into aquifers, ensuring minimal environmental disruption.

According to McGill, this breakthrough is especially critical in areas where water scarcity makes conventional mining untenable. He specifically noted that:

โ€œYou canโ€™t get a water permit [referring to water-stressed regions like the Colorado River basin]… So we show up and we are like, โ€˜We donโ€™t need water.โ€™โ€

Backed by Rio Tinto, venture capital firm IP Group, and Monash University, ElectraLith is preparing to scale its operations. The companyโ€™s upcoming funding round, which has been oversubscribedโ€”is a testament to investor confidence despite a challenging market.

The funds will support the construction of ElectraLithโ€™s first pilot plant at Rio Tintoโ€™s Rincon operations in Argentina, set to be operational within a year. Two additional pilot plants are planned, as the company aims to produce lithium hydroxide at half the cost of competitors.

Transforming the $10 Billion Lithium Industry

Direct Lithium Extraction is expected to drive the lithium industryโ€™s growth to over $10 billion in annual revenue within the next decade. ElectraLithโ€™s energy-efficient process not only accelerates production but also positions the company as a leader in sustainable EV battery material supply.

By addressing the dual challenges of water scarcity and environmental impact, ElectraLithโ€™s technology could redefine lithium production. As McGill emphasizes:

โ€œThis isnโ€™t just a better methodโ€”itโ€™s a necessary one for the future of EVs and the planet.โ€

With its revolutionary approach, ElectraLith is paving the way for a greener, more efficient future in lithium extraction and EV battery manufacturing.

Cutting Costs and Carbon, Not Corners: Lithium at Half the Price?

Lithium prices have been a driving force in the EV battery market, with significant fluctuations impacting producers and manufacturers.ย 

After peaking at nearly $85,000 per metric ton in late 2022, prices have recently cooled, stabilizing around $26,000 per metric ton. While this decline offers some relief to EV makers, it has created challenges for lithium producers, especially those reliant on cost-intensive extraction methods.

High-cost concentrate operations, including Nemaska, Mt Cattlin, and North American Lithium (NAL), are at risk of losses unless spodumene prices rise above $800/ton.ย 

To stay competitive, Sayona Mining and Piedmont Lithium, the two owners of NAL, announced a merger to streamline costs. This partnership, unlike the large-scale acquisition of Arcadium Lithium by Rio Tinto, focuses on cutting corporate overhead and operational inefficiencies.

However, challenges remain. Protectionist trade policies and the potential repeal of the US EV tax credit could dampen demand for Canadian lithium exports, adding further pressure to high-cost producers.

ElectraLith’s Direct Lithium Extraction technology offers a significant cost advantage. By producing lithium hydroxide at nearly half the cost of traditional methods, the company is poised to thrive even in volatile market conditions. This cost efficiency could help buffer against future price fluctuations, ensuring a steady supply of affordable lithium for EV battery production.

The cost of lithium is a critical factor for the industry, per Charlie McGill. However, their technology allows them to maintain competitiveness, even in challenging markets.

Lithium Prices: A Story of Volatility

The lithium market remains dynamic, with prices responding sharply to changes in supply and demand.ย 

For instance, the lithium carbonate China price surged to reach 83,000 yuan/ton, a three-month high. This rally followed production curtailments at key Australian mines and stronger-than-expected battery and cathode demand in China.

Spodumene concentrate prices have stayed stable, averaging $820-$830/ton through mid-November. Meanwhile, China’s traction battery production in October demonstrated unusual resilience. It declined only slightly month-over-month compared to a bigger drop a year earlier.ย 

Data suggests a recovery in battery and cathode output, further boosting demand for lithium.

A wave of supply cuts has also tightened the market. The latest cuts include halting operations at the Bald Hill and Altura mines and reducing 2025 production by 73,000 metric tons of lithium carbonate equivalent (LCE). Meanwhile, Australiaโ€™s Kathleen Valley mine has announced plans to delay and trim production.

The tightening supply coincides with lithium carbonate prices dropping, putting high-cost producers under pressure. Some companies are already planning to transition into care and maintenance by mid-2025, while others seek strategic mergers to cut costs.

Outlook for 2025 and Beyond

Lithium supply reductions are expected to shrink the market until 2027, driving a deeper deficit by 2028. Prices for 2028 are projected at $17,077 per tonne, per Goldman Sachs forecast.

With supply cuts narrowing the market surplus and demand from the EV industry projected to grow, lithium prices may find support in the medium term.

Ultimately, lithium prices are expected to remain volatile as demand accelerates. Amid all this, ElectraLithโ€™s revolutionary direct lithium extraction tech could help stabilize supply chains and drive the global energy transition forward.

Powering the Future of Nickel with NMC 811 Batteries

Disseminated on behalf of Alaska Energy Metals Corporation (AEMC).

As automakers prioritize energy efficiency and sustainability, nickel-rich batteries are becoming essential in the electric vehicle (EV) market. This silvery-white metal is now one of the most coveted elements for high-performance batteries that can power the future of electric mobility.

In this nickel revolution, high-nickel cathodes, such as those in NMC 811 batteries are taking the lead. These batteries offer higher energy density, reduced weight, and extended driving ranges which are vital consumer needs.

To name a few, top EV brands like Tesla, Volkswagen, Ford, and Stellantis are betting on NMC 811 batteries. Notably, these batteries reduce reliance on cobalt- a high-risk material, making them a more sustainable and cost-effective choice for the EV industry.

The Rise of NMC 811: Old vs. New

Traditional NMC 111 batteries rely on equal parts nickel, manganese, and cobalt. In contrast, the new standardโ€”NMC 811โ€”packs 80% nickel, cutting cobalt and manganese usage to just 10% each. This shift brings some powerful benefits to the new generation batteries:

  • 15% weight reduction
  • 30% longer battery life
  • Improved energy density and range

These upgrades not only enhance EV performance but also align with sustainability goals by reducing dependency on cobalt.

So, What Sets NMC 811 Batteries Apart?

The latest generation of NMC 811 batteries differs significantly from earlier versions, thanks to advancements in their composition.

  • Increased Nickel Content: The 8:1:1 ratio in NMC 811 refers to a higher proportion of nickel compared to cobalt and manganese. This shift enhances energy density, allowing EVs to travel farther on a single charge.
  • Cobalt Reduction: By minimizing cobalt content, these batteries reduce supply chain risks and improve affordability without sacrificing performance.
  • Lighter and More Efficient: Lightweight and longer battery life make them energy efficient for EVs, thereby contributing to better overall performance and lower energy consumption.

The Future of Nickel: Surge in Demand with Battery Innovation

We have seen and read earlier that battery nickel demand has faced challenges in 2024 mainly due to weak EV sales in Western markets. However, despite these short-term setbacks, the long-term outlook for nickel appears highly promising. Projections suggest that demand for battery-grade nickel will grow by 27% year-on-year in 2024, highlighting its critical role in the EV revolution.

  • According to the Benchmark Nickel Forecast, batteries will drive over 50% of nickel demand growth by 2030, with consumption expected to reach 1.5 million tons by the decade’s end.

This growth reflects the increasing reliance on nickel-based chemistries, which are expected to dominate sustainable battery manufacturing. The Benchmark analysis also shows that such prototypes will account for 85% of battery cell production capacity outside China by 2030.

Thus, it seems inevitable that high-nickel chemistries, precisely the NMC 811 batteries will be the key driver for nickel demand and represent a significant breakthrough in the EV industry.

MUST READ: Nickel Could Be the Key to U.S. Energy Independence: Alaska Energy Metalsโ€™ Strategic Role

FEATURED: Live Nickel Prices


Disclosure: Owners, members, directors, and employees of carboncredits.com have/may have stock or option positions in any of the companies mentioned: AEMC.

Carboncredits.com receives compensation for this publication and has a business relationship with any company whose stock(s) is/are mentioned in this article.

Additional disclosure: This communication serves the sole purpose of adding value to the research process and is for information only. Please do your own due diligence. Every investment in securities mentioned in publications of carboncredits.com involves risks that could lead to a total loss of the invested capital.

Please read our Full RISKS and DISCLOSURE here.

COP29 Key Outcomes: Milestones, Setbacks, and What Comes Next for Global Climate Action

The recently concluded COP29 in Baku marked another critical milestone in global climate action with mixed outcomes. Developed nations committed to channeling at least $300 billion annually into developing countries by 2035 for climate action. However, this fell short of the $1.3 trillion annual target demanded by developing nations.ย 

The climate summit also finalized Article 6 on carbon markets, operationalizing the Paris Agreement nearly a decade after its inception. Meanwhile, key decisions on the global stocktake and fossil fuel transition were postponed to COP30 in Brazil. The negotiations occurred amidst political tensions, including Donald Trumpโ€™s re-election and potential U.S. withdrawal from the Paris Agreement.

Below we share our six key takeaways from this yearโ€™s climate talks.ย 

Article 6: Carbon Markets Take Center Stage

Article 6 of the Paris Agreement, which deals with carbon market mechanisms, took center stage at COP29. After years of negotiation, the summit finalized mechanisms for global carbon trading.ย 

Article 6.2 governs direct country-to-country carbon credit trading, while Article 6.4 establishes the Paris Agreement Crediting Mechanism (PACM), a centralized carbon market under UN supervision. It allows countries, corporations, and individuals to trade emission reduction units, referred to as A6.4ERs (Article 6.4 Emission Reductions Units).

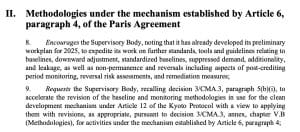
The PACM introduces enhanced safeguards, including sustainable development tools and stricter methodologies to prevent “locking-in” high emissions. For example, it enforces baseline adjustments and “additionality” checks, ensuring projects generate genuine emission reductions.ย 

methodologies under Article 6.4

These features aim to avoid pitfalls of past carbon market mechanisms, like the Clean Development Mechanism (CDM). Some projects under the CDM, such as afforestation, may transition into the PACM if they meet updated removal standards.

To prevent double-counting of credits, stringent rules for “corresponding adjustments” were introduced. For example, when a country sells emission credits, it must deduct the equivalent reductions from its own accounting, ensuring transparency and integrity.

Despite progress, experts remain cautious. While negotiators hailed the deal as a milestone, critics argue it oversells the mechanism’s potential to deliver large-scale mitigation. Concerns persist over transparency, particularly under Article 6.2, where “cooperative approaches” could lack stringent oversight.ย 

To address these concerns, COP29 decisions require enhanced reporting and transparency in Article 6.2 activities and encourage swift finalization of PACM methodologies by 2025. These measures are pivotal for building trust and ensuring that carbon markets contribute meaningfully to global climate goals.

  • Additionally, a โ€œShare of Proceedsโ€ mechanism was adopted, channeling 5% of transaction volumes and 3% of issuance fees into the Adaptation Fund. This provides critical resources for climate resilience in vulnerable regions while fostering global emissions reductions.

A New Era for Climate Finance

One of the most anticipated outcomes of COP29 was the agreement on a new collective quantified goal (NCQG) for climate finance. This goal seeks to replace the $100 billion annual target set at COP15, which had been criticized for being insufficient and inadequately mobilized. The NCQG represents a more dynamic, needs-based approach to climate financing.

At COP29, a new global climate finance target was introduced, aiming to raise $300 billion annually for developing countries by 2035. The goal includes public funds, development bank loans, and private investments mobilized by governments.

The NCQG has been a point of contention in climate talks. Developed countries are expected to provide significant funding, but developing nations argue that trillions of dollars are needed for their transition to cleaner economies.

The agreement also allows for “voluntary” contributions from nations like China, which have not traditionally provided climate finance.

Disagreements over the size and scope of the target caused delays and frustrations, with several drafts and revisions circulating before reaching a final agreement.ย Developed countries argue that global efforts must include a diverse range of contributors. As Jacob Levine, a senior director for climate and energy at the White House, stated:

“When you consider the magnitude…we need people to contribute, to do their fair share and to recognize the opportunity to work together.”

In contrast, developing nations, led by groups like the G77 and China, have insisted that developed countries bear the primary responsibility. Ali Mohamed, African Group Chair, remarked:

“We need equitable access for all developing countries. Cherry-picking certain groups won’t solve the global climate crisis.”

  • The final agreement urges contributions from all sources, public and private, to meet a broader target of $1.3 trillion annually by 2035.

Mitigation Work Programme: Accelerating Action

The Mitigation Work Programme (MWP), established at COP26, received renewed attention at COP29. Delegates agreed to expand efforts to enhance renewable energy deployment and phase down unabated fossil fuel use.

However, progress has been limited to workshops and discussions. At COP28 in Dubai, negotiations faltered over whether the MWP should convey high-level political messages or remain strictly procedural. This stalemate carried into the Bonn negotiations in June 2024, with disagreements centering on linking the MWP to the global stocktake and its outcomes.

At COP29, these disputes persisted, particularly over including references to transitioning away from fossil fuels. Developing nations, represented by groups like the LMDCs and Arab states, opposed such language, citing concerns over top-down mandates.

Meanwhile, developed nations sought to integrate global stocktake results and emphasize stronger NDC updates. Paragraph 32 of an informal note, which mentioned the fossil fuel phaseout, proved particularly divisive, stalling discussions.

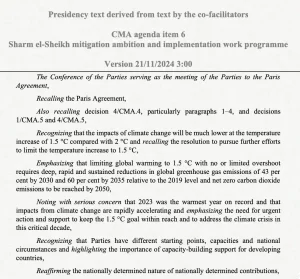
Despite efforts to revive negotiations in the summit’s second week, the final text (shown below) offered minimal progress. High-level political messaging was softened, with no explicit mention of the stocktake or fossil fuels.ย 

mitigation work program draft COP29

While the dialogues under the MWP, focused on urban systems, were deemed productive, the adopted text primarily reaffirmed procedural elements, leaving substantial mitigation ambitions largely unresolved.

Adaptation: Scaling Resilience

Adaptation is one of the significant COP29 outcomes. Discussionsย focused on the Global Goal on Adaptation (GGA) and National Adaptation Plans (NAPs), yet progress was hindered by disagreements. The UAE-Belรฉm work program, introduced at COP28, aims to establish indicators for adaptation targets, including resilience in water, ecosystems, and cultural heritage.ย 

Midway through this two-year initiative, countries clashed over including โ€œmeans of implementationโ€ (MOI)โ€”primarily financial supportโ€”and the concept of โ€œtransformational adaptation,โ€ which developing nations feared might create obstacles to funding access.

The outcome included the โ€œBaku Adaptation Roadmap,โ€ softening MOI language to โ€œenablers of implementationโ€ to balance developed countriesโ€™ demands for governance and transparency with developing nationsโ€™ calls for financial support. While this compromise acknowledged both sides, it left many countries dissatisfied, particularly those advocating for robust financial commitments.

NAP discussions, initially slated to conclude in week one, also experienced delays due to extensive disagreements. By week two, facilitators proposed procedural conclusions, deferring substantive decisions to Bonn in June 2025. Other adaptation-related matters, such as the adaptation fund and performance reviews, were similarly postponed.

The roadmapโ€™s adoption and continued GGA discussions underscore adaptation’s complexity and urgency as climate impacts intensify. COP30 is expected to revisit unresolved issues, including financial commitments and equitable adaptation frameworks.

Loss and Damage Fund: A Historic Step

COP29 marked a turning point with the operationalization of the Loss and Damage Fund, initially agreed upon at COP27. This fund aims to provide financial support to nations suffering from climate-induced disasters such as hurricanes, floods, and sea-level rise.

The fundโ€™s governance structure ensures equitable distribution of resources, prioritizing least-developed countries and small island developing states (SIDS). Discussions also explored innovative funding sources, including levies on fossil fuel exports and international shipping, to sustain the fund over the long term. โ€‹

The operationalization of this fund underscores the principle of climate justice, acknowledging the disproportionate impact of climate change on vulnerable populations.ย 

Still, loss and damage funding remained contentious at COP29. While the fund advanced with pledges rising to $759 million, developing nations criticized the insufficient funding.

UN chief Antรณnio Guterres highlighted the lack of justice for vulnerable nations. He stated that the fundโ€™s capitalization falls far short of addressing the need.

Negotiators failed to include loss and damage in the new climate-finance goal (NCQG), as developed countries resisted expanding finance obligations. Discussions on the Warsaw International Mechanism (WIM) and Santiago Network stalled due to disagreements, with progress deferred to mid-2025.

The UAE’s Global Stocktake

The UAE-hosted conference underscored its role as a key stakeholder in global climate action through the first-ever global stocktake (GST). This assessment measured the worldโ€™s progress toward the Paris Agreement goals, providing a clear picture of where nations stand on mitigation, adaptation, and finance.

At COP29, climate talks became contentious as nations grappled with commitments from COP28’s GST. The UAEโ€™s approach to discussions about fossil fuel transitions sparked debate.ย 

Developed nations and vulnerable countries demanded stronger commitments for transitioning away from fossil fuels, while Saudi Arabia opposed the inclusion of specific fossil fuel language, emphasizing the need for finance-focused discussions. This clash led to diluted draft texts and an impasse on key issues.ย 

In the end, the UAE dialogue was postponed until the 2025 talks, leaving many disappointed. However, COP30 in Brazil holds the potential for renewed momentum, especially in terms of accountability and climate action.ย 

Conclusion

The COP29 outcomes in Baku delivered a mix of progress and challenges, with significant advancements in climate finance, carbon markets, and adaptation efforts. The outcomes reflect a growing recognition of the need for collective action to address the climate crisis.

The focus now shifts to implementing these agreements and bridging gaps in ambition, funding, and delivery. As the world gears up for COP30, the lessons from Baku will serve as a critical foundation for driving forward the Paris Agreement goals.

EU’s Green Bonds to Slash 55 MTS of COโ‚‚ Annually. Can it Hit Europe’s 2050 Net Zero Target?

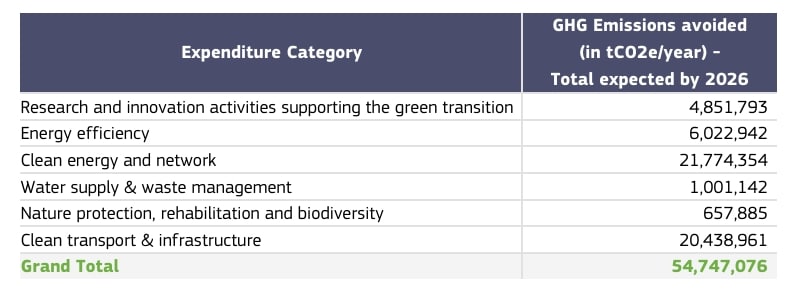
The European Commission released its NextGenerationEU (NGEU) Green Bonds Allocation and Impact Report 2024 explaining how proceeds from green bonds are being used to combat climate change. The report highlights substantial achievements in reducing greenhouse gas (GHG) emissions. Therefore, the EU estimated that 55 million tons of COโ‚‚ emissions should be avoided annually across the European Union to meet Europeโ€™s net zero target.

Estimated impact per expenditure categoryEU green bonds

Source: EU Green Bonds Allocation and Impact Report 2024

Key Climate Impacts of EU’s Green Bond Projects

This year’s report has refined 2023โ€™s methodologies for assessing the environmental impacts of green bond-funded projects. The findings reveal significant progress:

1. GHG Reductions

Projects funded by NGEU Green Bonds can avoid ~ 54.7 million tons of COโ‚‚ annually. This is much higher than that of last yearโ€™s estimate of 44.2 million tons This accounts for approximately 1.5% of the EUโ€™s annual emissions in 2022.

2. Sectoral Contributions

Investments focused on Clean Transport & Infrastructure in rail networks and zero-emission vehicles lead to a reduction in emissions. Clean Energy & Networks projects span solar and wind energy are significant. Additionally, Nature Protection and Biodiversity, sector although comparatively smaller, are also included in the analysis focusing on environmental restoration and preservation.

3. Methodology Enhancements

The analysis evaluated 2,096 milestones and targets robust quantifiable data. This expanded scope allows for a more comprehensive understanding of the climate benefits. Significantly, some sectors achieve higher emissions reductions per euro spent. Nonetheless, all investments must achieve climate neutrality by 2050.

NextGenerationEU: A Green Recovery Initiative

Launched in 2021, NextGenerationEU is an โ‚ฌ800 billion recovery program meant to boost Europeโ€™s post-pandemic recovery while advancing its green and digital transformation. The EU explains that the initiative aims to make the body more resilient and sustainable. A significant portion of its funding comes from NGEU Green Bonds, which play a critical role in financing climate-friendly projects.

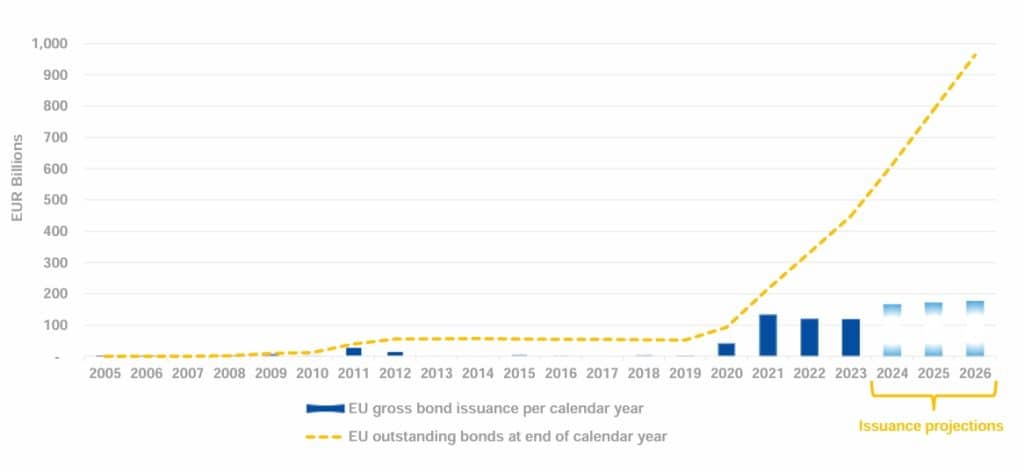
To date, the EU has issued โ‚ฌ12 billion in green bonds and notably, itโ€™s the worldโ€™s largest green bond transaction. The European Commission plans to fund 30% of the NextGenerationEU program through green bonds. Consequently, this will make the EU the largest green bond issuer globally.

EU Bond Issuancesgreen bonds EU ISSUANCESSource: EU

Strategic Importance of NGEU Green Bonds

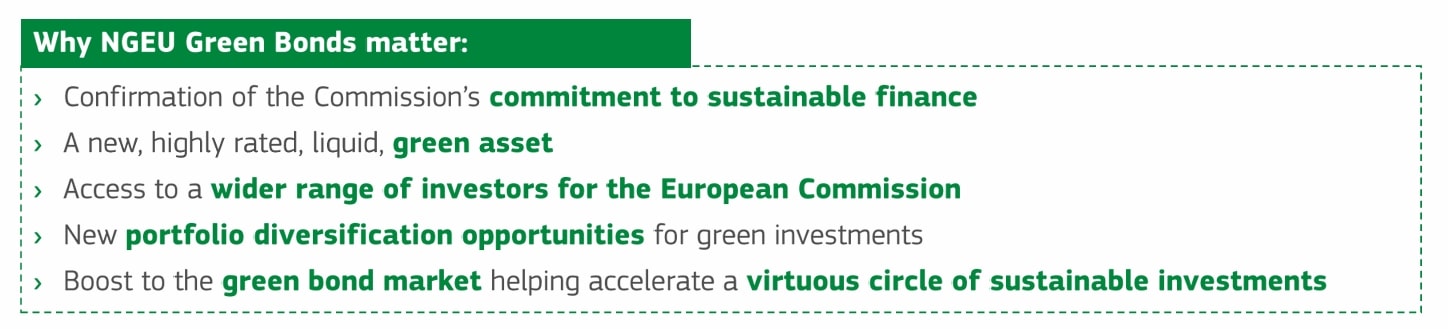
NextGenerationEU Green Bonds are not only transforming Europeโ€™s environmental landscape but also boosting global sustainable finance. Their benefits include:

  • Sustainable finance commitment reinforces the EUโ€™s dedication to environmental sustainability.
  • Market liquidity introduces a highly rated and liquid green asset to investors.
  • Investor confidence attracts a broader range of investors while offering portfolio diversification.
  • Market growth inspires other issuers and strengthens the green bond market.
  • EU leadership enhances the European Unionโ€™s role in sustainable finance globally.

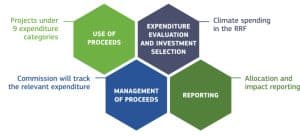
The European Commission issues its NextGenerationEU Green Bonds based on a structured framework designed to ensure transparency and accountability. This framework aligns with international standards, setting a strong foundation for sustainable investments across the EU.EU green bondsSource:

Inside the NextGenerationEU Green Bond Framework

The NextGenerationEU Green Bond framework revolves around four key pillars:

1. Use of Proceeds

Funds raised through these green bonds are allocated to nine key categories, including energy efficiency, clean energy projects, and climate change adaptation measures.

2. Expenditure Evaluation and Investment Selection

Investments are guided by the Recovery and Resilience Plans, which allocate 37% of their budgets to climate-related projects. These plans serve as the blueprint for the Recovery and Resilience Facility at the core of NextGenerationEU.

3. Management of Proceeds

The European Commission carefully monitors and tracks how the funds are spent, ensuring they are used for eligible green initiatives.

4. Reporting

The Commission provides two types of reports: Allocation Reportsย which highlight how funds have been distributed and Impact Reports demonstrate the achievements and environmental impacts of these investments. The first allocation report was released in 2022, followed by a comprehensive allocation and impact report in November 2023.

EU NextGenerationEU (NGEU) Green Bonds

Source: EU

Alignment with Global Standards

Noteworthy, the framework adheres to the Green Bond Principles of the International Capital Market Association (ICMA), a global benchmark for green bond issuances. This compliance was independently verified by Vigeo Eiris, part of Moodyโ€™s ESG Solutions.

They confirmed that the framework aligns with the EUโ€™s broader Environmental, Social, and Governance (ESG) strategy. Furthermore, the evaluation assures investors that the framework contributes immensely to Europeโ€™s sustainability goals.

Financing Mechanisms and Future Goals

The European Commission utilizes diverse instruments such as EU bonds, EU bills, and NGEU Green Bonds to fund policy programs. Funding plans are communicated bi-annually, with โ‚ฌ712 billion expected to be raised through NGEU bonds by 2026.

Additionally, the EU also highlighted that it leverages funding to support external needs, including financing loans for Ukraine. Under the Ukraine Facility, the Commission plans to raise โ‚ฌ33 billion in EU bondsย from 2024 to 2027.

EU Green Bond Supporting Europeโ€™s Green Transition

The NextGenerationEU Green Bond framework is one of the key propellers of the EUโ€™s fight against climate change. As outlined before it follows strict principles, ensures transparency, and provides detailed reporting to ensure that โ€œevery euroโ€ raised supports environmental and economic resilience. Investments funded by NGEU Green Bonds span critical sectors like clean energy, transport, and nature restoration, highlighting the importance of diverse efforts to achieve net-zero emissions by 2050.

The EUโ€™s proactive strategy, supported by robust funding and transparent practices truly makes it a leader in sustainable finance. By fostering innovation and scaling investments, NGEU Green Bonds are shaping a greener, more resilient Europe.

Source:

  1. NextGenerationEU Green Bonds – European Commission
  2. Green Bonds Allocation and Impact Report 2024

BHPโ€™s $14B Investment Plan for its Chile Copper Mines. Will it Impact Global Copper Supply?

BHP has set ambitious plans for its largest copper mine i.e. its Escondida mine and other operations in Chile, with investments ranging from $10.7 billion to $14.7 billion over the next decade. The mining giant aims to address declining ore grades and prepare for the eventual closure of the Los Colorados plant. The Escondida mine plays a significant role in this strategy, with its upcoming projects projected to initiate production between 2027 and 2032.

BHP Americas president Brandon Craig told Reuters inย a recent interview,

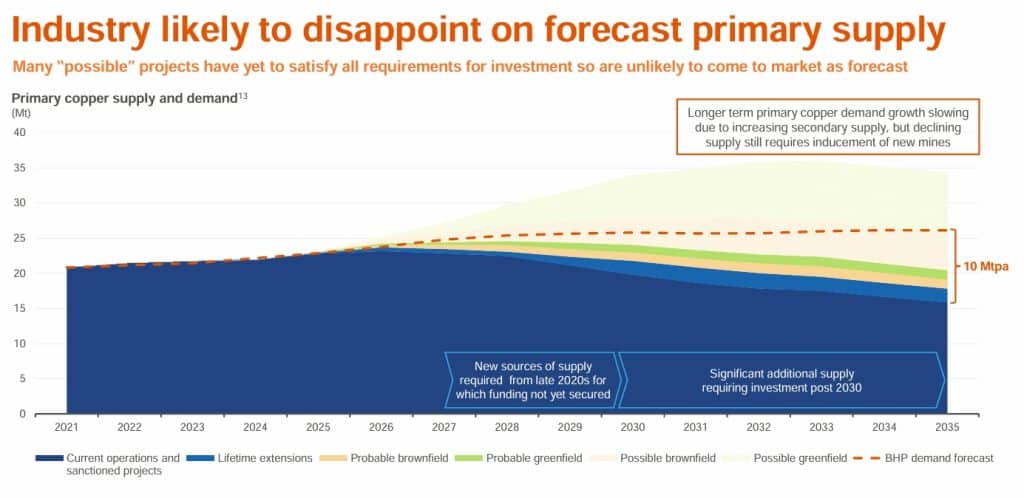
โ€œWe think the deficit is going to be around 10 million tons by 2035.”

He further estimated a $250 billion cost to develop enough mines to match demand and hailed it as quite a challenging task for mining companies.

BHP Copper forecast

Source: BHP

Escondida: BHPโ€™s Copper Catalyst

Located in the Atacama Desert of Northern Chile, Escondida, the largest copper mine lies 170 km southeast of Antofagasta. Escondida in Spanish means “hidden,” which is synonymous with the copper deposit thatโ€™s buried under hundreds of meters of overburden. The mine feeds three concentrator plants and two leaching operations, producing copper essential for global industries.

BHP owns a 57.5% stake in Escondida, with Rio Tinto holding 30% and JECO Corp controlling the remaining 12.5%. Their joint efforts have made Escondida a vital player in boosting Chileโ€™s GDP.

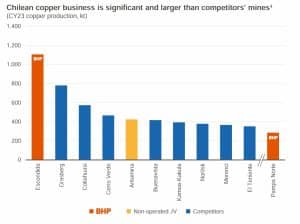
We also discovered from its corporate deck that BHPโ€™s Chilean mine has delivered 38 million tons of copper since 1990 which accounted for 7% of global copper mine output.

BHP’s Chilean Copper Dominance

BHP COPPER chile

Source: BHP

To address declining ore grades, BHP plans to expand its processing facilities and implement advanced copper extraction technologies. For example, introduceย leaching technologies to extract copper from sulfide ores.

The company will launch four new projects at Escondida, starting between 2027 and 2032, with peak investments expected during fiscal years 2030 and 2031.

Key Projects Supporting BHP’s Investment Plans

Let’s take a look at the investment breakup as outlined by MINING.COM.

  • The new concentrator will have a capacity of 220,000 and 260,000 tpa from 2031 or 32, with an estimated capital budget of $4.4 billion to $5.9 billion.
  • Expand production at Laguna Seca by 50,000 to 70,000 tpa starting in 2030/31, with an investment of $2 billion to $2.6 billion.
  • New leaching facilities will add ~ 35,000 to 55,000 tpa from 2030/32 onwards, requiring a capital expenditure of $900 million to $1.3 billion.
  • The Los Colorados facility will continue operations until fiscal year 2029, maintaining an output of 130,000 to 145,000 tpa before its scheduled closure.
  • Allocate $2.8 billion to $3.9 billion for its Pampa Norte division, which includes the Spence and Cerro Colorado mines.
  • Boost production at Pampa Norte by 125,000 to 155,000 tpa. Restart the Cerro Colorado mine, using supergene leaching to deliver 85,000 to 100,000 tpa.

Through these investments, the company expects to stabilize production at 1.4 Mtpa by the early 2030s and maximize output from Chileโ€™s copper-rich regions, including Escondido.

With these strategies and rationale, BHP aims to overcome the challenges of depreciating ore grades and increasing project complexities. Significantly, the investment, ranging between $10 and $14 billion, will be at a capital intensity of $23,000 per tonne of copper equivalent (CuEq) to achieve its targeted expansion plans.

BHP’s Copper Output: Meeting the Demand Surge

Copper, a pinkish-orange metal known for its exceptional conductivity and non-corrosive properties makes it a daily life metal. Itโ€™s widely used in electrical systems and has antimicrobial properties as well. The global copper demand is projected to rise in the coming years, but BHP has warned of a possibility of a 10mmt supply deficit by 2035.

Chile, the worldโ€™s largest copper producer, contributes 28% of the global supply annually. BHPโ€™s operations contribute solely to 27% of Chileโ€™s copper output. ย 

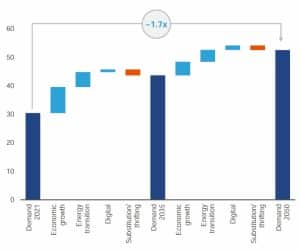
  • In 2023, BHP produced 1,716 kilotons (Kt) of copper. The company forecasted global demand to be approximately 2X in the next 30 years.

The rising demand for copper will be driven by the global energy transition and advancements in technology. Particularly by the growing adoption of electric vehicles and the rapid expansion of data centers.

Copper demand is projected to grow ~70% through to 2050.
(Copper semis end-use demand by key theme, Mt)

Copper demand BHP

Source: BHP

Streamlined Operations and Strategic Advantages

Further putting the expansion plans into perspective, BHP expects to boost copper production by 430,000 to 540,000 tpa in its Chile operations. It shows the companyโ€™s adeptness in streamlining its operations and managing fewer but larger assets by efficiently using its infrastructure and workforce.

Being a pioneer in mining, it has time and again proved its deep geological knowledge to minimize technical risks while exploring low-risk brownfield opportunities.

Even though the global copper industry faces significant challenges, with a looming supply deficit nearly equal to 50% of todayโ€™s production, BHP remains committed. Itโ€™s adopting new technologies over time and fostering strong, mutually beneficial relationships with stakeholders to ensure sustainable growth amid market downturns.

As outlined earlier, by investing heavily in advanced technologies and strategic expansions, BHP ensures Escondida remains a critical pillar of the global copper supply and continues supporting the worldโ€™s current and future energy transition goals.

Data sources:

  1. BHP to spend up to $14bn in Chilean copper expansion – MINING.COM
  2. BHP bets billions on Chile mines to face global copper crunch – MINING.COM
  3. BHP 2024 Chilean copper site tour

HSBC Drops Carbon Credit Trading Amid Voluntary Carbon Marketโ€™s $1B Decline

HSBC Holdings Plc, Europeโ€™s largest bank, has abandoned its plans to establish a carbon credits trading desk, per a Bloomberg report. The decision reflects mounting concerns about the voluntary carbon market (VCM), which has been plagued by greenwashing allegations and declining corporate confidence.ย 

Originally intended to trade credits and finance project developers, HSBCโ€™s carbon credit desk initiative was short-lived, with the team now reassigned to other roles.

From Pledges to Pivots: HSBC Rethinks Carbon Market Role

HSBC unveiled its HSBC Infrastructure Finance (HIF) last July, a new business unit dedicated to infrastructure financing and project advisory for low-carbon initiatives. The unit seeks to capture significant deals in major markets with expertise from the bankโ€™s Global Banking Real Asset Finance.

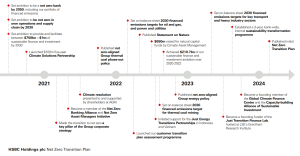
This move aligns with HSBCโ€™s broader climate strategy, including its 2050 net-zero target and Net Zero Transition Plan. During the launch, HIF underscores HSBCโ€™s commitment to supporting the low-carbon economy through sustainable financing and risk management initiatives. But only four months later, the unit had to stop operating.ย 

HSBC Net Zero Pathway

HSBC net zero journey to 2050

HSBCโ€™s operational and supply chain emissions are modest compared to its financed emissions. Still, cutting these emissions is vital to its net zero goals.ย 

The bank aims to achieve carbon neutrality by 2030 through 100% renewable electricity and minimized environmental impacts. Key measures include reducing emissions from energy use, travel, and supply chains.ย 

HSBC also pledged $1 billion last year to accelerate global climate technology advancements, particularly in the following areas:

This is part of HSBCโ€™s broader commitment to achieving 2050 net-zero emissions across its financed portfolio.

The funding builds on HSBC’s existing climate initiatives, including HSBC Innovation Banking and Climate Tech Venture Capital. Both are designed to advance cleantech sectors like energy and transportation.ย 

Additionally, HSBC invested $100 million in Bill Gatesโ€™ Breakthrough Energy Catalyst Fund, further supporting green projects and scaling climate-focused innovations.

Earlier this year, the bank teamed up with Google Cloud to support companies driving climate innovation via the Google Cloud Ready-Sustainability (GCR-Sustainability) program. This initiative aids businesses in reducing carbon emissions, improving supply chain sustainability, and managing ESG data to address climate risks.

Through this collaboration, HSBC will provide financial backing to selected companies, aligning with its $1 billion commitment to climate tech ventures in areas such as EVs, battery storage, and sustainable food systems by 2030.

However, its recent decision to drop its carbon credit trading desk speaks of a sudden shift in the financierโ€™s strategy. It sent shockwaves in the VCM, showing how corporates are taking market issues into account.

Why Pull Back From the VCM?

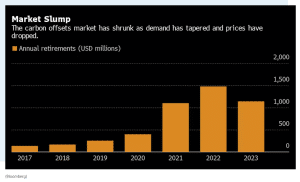
The voluntary carbon market, which peaked a few years ago, experienced a sharp contraction in 2023, shrinking by nearly 25% to an estimated $1 billion.ย 

carbon credit offsets annual retirements
Source: MSCI Note: Data sourced from registries ACR, ART Trees, BioCarbon, CAR, CDM (NDC eligible credits only), Climate Forward, EcoRegistry, GCC, Gold Standard, PlanVivo, PuroEarth, UKPC, UKWCC and Verra.

Concerns about the marketโ€™s integrity have driven major companies to scale back their reliance on offsets. These include Google, Delta Air Lines, and EasyJet. They are now prioritizing direct emission reductions over purchasing credits, reflecting a broader trend across industries.

One major issue undermining the VCMโ€™s credibility is the over-issuance of carbon credits. Some of these credits, intended to represent the avoidance or removal of one metric ton of COโ‚‚, fail to deliver the promised climate benefits as reported by studies. This has led to a loss of trust among buyers and a corresponding decline in market activity.

HSBCโ€™s decision follows a similar move by Shell Plc, which recently announced plans to divest a majority stake in its nature-based carbon projects. Despite being the largest publicly disclosed buyer of carbon credits last year, Shell is reevaluating its approach amid market uncertainties.

Banks like Bank of America have also exercised caution toward the VCM due to its lack of liquidity. Abyd Karmali, Bank of Americaโ€™s environmental business advisory lead, described the past two years as challenging for the market, which has seen declining participation and interest.

Shifting Priorities: HSBC Targets Cleantech

HSBCโ€™s decision aligns with the vision of its new CEO, George Elhedery, who assumed the role in September. The new leadership has since focused on streamlining the organization.ย 

While HSBC steps back from direct involvement in carbon credit trading, it remains committed to addressing emissions. The bankโ€™s latest transition plan emphasizes purchasing credits to address residual emissions and supporting Climate Asset Management, its joint venture with Pollination, to develop new carbon credit pipelines.

The regulatory landscape is also evolving, with COP29 negotiators advancing Article 6.4. It is a framework that allows countries and corporations to trade carbon reductions. This development, along with new quality standards from the Integrity Council for the Voluntary Carbon Market, aims to restore confidence and liquidity in the market.

HSBCโ€™s retreat from carbon credit trading underscores the challenges facing the VCM as it struggles with integrity issues and waning demand. Europeโ€™s largest bank pivot reflects a broader trend of recalibrating strategies to align with evolving market and regulatory conditions.

Zefiro Methane Tackles Methane Emissions: Completes its First Oklahoma-Based Gas Well Remediation Project

Zefiro Methane Corp. (ZEFI) announced that its subsidiary, Plants & Goodwin, Inc. (P&G), has successfully completed its first gas well remediation project in Oklahoma. The project involved a complex operation known as “plug and abandonment” on a deep gas well in Custer County, Oklahoma. The well, 15,000 feet deep, required the removal of 5,000 feet of casing to seal it permanently. This operation is expected to generate carbon offset products approved by the American Carbon Registry.ย 

Zefiro Methane’s Founder and Chief Executive Officer Talal Debs commented,

โ€œToo many Oklahomans and Americans living across the south-central United States are still forced to navigate the public health threats posed by these vestiges of a bygone era. The completion of this project not only represents Zefiroโ€™s successful entry into a key marketplace but also reinforces the Companyโ€™s forward momentum and total commitment to executing our growth strategy by helping more of our neighbors combat this legacy issue.โ€

Unplugged Wells: A Major Challenge Across the U.S.

For decades, fossil fuel companies in the United States have drilled oil and gas wells to boost production, consumption, and exports. Once these wells become unprofitable, they are often abandoned. Many are left unplugged or improperly sealed, leading to environmental risks and fueling climate change.

Zefiro Methaneโ€™s press release explained that in the U.S., millions of oil and gas wells remain unplugged. For example, Oklahoma has about 18,000 known abandoned wells, while Texas and Louisiana have thousands more.

  • Experts estimate it could cost up to $158 billion just to plug the suspected 1.14 million unplugged wells in these three states alone.
  • Nationwide, sealing all abandoned wells could cost as much as $435 billion.

Dangerous Methane Source

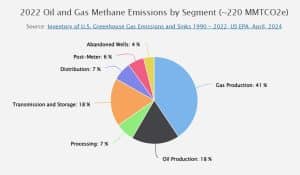
Abandoned and unplugged oil and gas wells are leaking methane which is a potent greenhouse gas. Methane is 25X stronger than carbon dioxide at trapping heat and is a powerful contributor to global warming. This gas causes climate change, pollutes water, and is harmful to human health.

oil and gas methane emissions EPA

Source: EPA

Financial Burden on States

Unplugged oil and gas wells create significant environmental and financial risks. When these wells become orphaned, meaning abandoned without responsible parties, they pose a burden on taxpayers with the costly cleanup. The responsibility to manage these wells falls on the states. Moreover, funds from industry fees and bonding requirements might not cover the costs.

Due toย improper management, they release harmful pollutants, leading to air pollution, groundwater contamination, and degraded soil quality. These environmental impacts are highly detrimental to ecosystems, wildlife, and the land.

Safety Hazards

Another significant hazard of these unplugged and abandoned wells is the risk of explosions. It then becomes a persistent threat to both communities and the environment. Thus, addressing these wells is crucial to minimizing their long-term impacts.

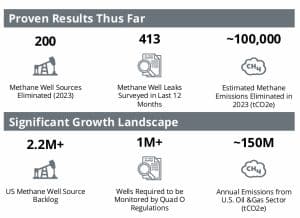
Zefiro Methane

Source: Zefiro Methane

Letโ€™s see what other leaders of Zefiro Methane remarked on this project.

Zefiro’s Chief Commercial Officer Tina Reine commented,

โ€œNow more than ever, investors throughout the international voluntary carbon marketplace are seeking offset products that can immediately help clean up our critical air, land, and water resources. The expertise of the oil and gas well remediation specialists on this project have further diversified both Zefiroโ€™s operational presence and unique portfolio of high-quality, verified carbon credits, and our entire team cannot be more excited to continue meeting this long-unaddressed sector demand.โ€

Senior Vice President of Business Development and Chief Executive Officer of P&G Luke Plants commented,

โ€œThe Custer County project is the largest leap forward that our environmental remediation and carbon markets teams have taken together to help solidify Zefiro as the methane abatement sectorโ€™s leading comprehensive service provider. This successful effort is indicative of our environmental service divisionโ€™s drive to help plug more of these wells throughout the south-central United States and in every corner of the country by expanding technical capacity, making operations even more efficient, and helping generate high-quality carbon credits.โ€

Zefiro Methane Credits: Maximizing Climate Impact

Zefiro also noted that its methane abatement credits deliver immediate and impactful climate solutions. As said before, methane has a significantly higher global warming potential than CO2 and has contributed to 30% of global temperature rise since the Industrial Revolution.

By focusing on methane reductions, Zefiro provides high-value credits that have significant demand for their ability to create measurable environmental benefits. These credits not only help bridge the gap for companies striving to meet net-zero goals but also play a crucial role in tackling the urgent challenge of climate change.

Expanding into New Regions

All said and done, the company is tackling the unplugged abandoned wells crisis seriously. It recently launched operations in West Virginia and acquired companies in Ohio and Pennsylvania to strengthen its capabilities nationwide. The company has partnered with federal and state agencies, including the National Park Service and the Commonwealth of Pennsylvania, to seal orphaned wells.

Additionally, it plans to expand its remediation efforts into other southern states like Texas and Louisiana within the next year. These regions also harbor thousands of abandoned oil and gas wells, many of which are not yet properly sealed.

By addressing methane leaks, which trap heat 25 to 85 times more than carbon dioxide, Zefiro is protecting communities and combating climate change efficiently.

Sources:

  1. Zefiro Methane – News: Zefiro Methane Corp. Completes Its First Ever Oklahoma-Based Well Remediation Project
  2. Zefiro Corporate Presentationย 

COP29: Singapore and Peru Seal the Deal on Article 6 Carbon Credits Framework

Singaporeโ€™s Ministry of Trade and Industry (MTI) announced on Nov. 21, during the COP29 climate summit in Azerbaijan, that it has substantively concluded negotiations on a bilateral carbon trading agreement with Peru. The Implementation Agreement (IA), aligned with Article 6 of the Paris Agreement will allow Singapore to purchase carbon credits from Peru.

Singaporeโ€™s Minister for Sustainability and the Environment and Minister-in-charge of Trade Relations, Ms Grace Fu, said,

โ€œThe successful conclusion of substantive negotiations on the Implementation Agreement with Peru marks a significant milestone in our collective efforts to combat climate change and achieve our climate targets through cooperation. We thank our Peruvian counterparts for their partnership to advance global climate action. When the agreement is signed, we look forward to the private sector utilizing this agreement to develop carbon credits projects to actualize concrete environmental outcomes.โ€

Carbon Credits Cooperation: Unlocking the Implementation Agreement

This partnership builds on a 2022 memorandum of understanding (MOU) between the two countries, which laid the foundation for bilateral cooperation in carbon markets.

The next step involves formalizing the agreement through an implementation signing. The key highlights of the collaboration and the agreement include the following:

  • The collaboration aims to boost mitigation efforts and scale effective climate solutions, helping both countries advance their climate goals.
  • The agreement also creates a framework for generating and transferring Article 6-compliant carbon credits internationally.
  • It defines clear criteria and processes for developing carbon credit projects. It also outlines how credits will be transferred between Singapore and Peru.
  • The agreement outlines steps to ensure independent and robust accounting and eliminate double counting of carbon credits.

Once completed, Singaporean companies liable for carbon taxes can purchase credits from Peru to offset up to 5% of their taxable emissions. This marks a significant step in Singaporeโ€™s efforts to explore alternative pathways to reduce its carbon footprint.

COP29 Spotlight: Singapore Expands Carbon Market Ties

Singapore has been active in advancing carbon credit initiatives at COP29 and achieved some important milestones in this space. On Nov. 18, the Singapore Sustainable Finance Association signed a pact with five major carbon market associations representing Malaysia, Indonesia, Singapore, Thailand, and ASEAN to create a unified ASEAN Common Carbon Framework. This collaboration aims to reduce implementation costs and unlock regional carbon project opportunities.

Recently, Singapore and Zambia signed a similar Memorandum of Understanding (MOU) to collaborate on carbon credits aligned with Article 6 of the Paris Agreement at the COP29 summit. This was announced on November 19. The MOU enables both countries to share best practices and knowledge on carbon credit mechanisms. It also helps identify carbon credit projects that benefit both nations and support their climate goals.

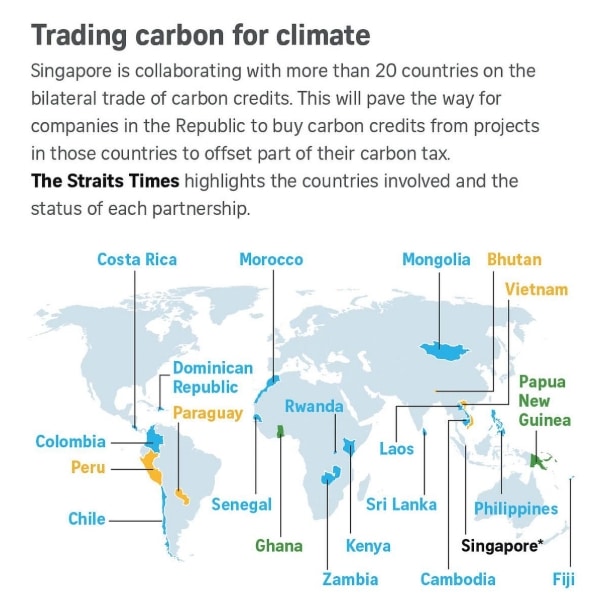
Singapore carbon credits

Source: The Straits Times

Singapore has already signed implementation agreements with Papua New Guinea and Ghana, although trading under these agreements has not started.

The country is actively engaging with over 20 countries on carbon markets, most of which remain in the MOU phase. MTI revealed that the country has signed similar agreements with Cambodia, Chile, Fiji, Kenya, Lao PDR, Mongolia, Peru, Rwanda, Senegal, Sri Lanka, and the Philippines.

Peru now joins Bhutan, Vietnam, and Paraguay as countries that have reached the advanced stage of finalizing crucial issues on carbon trading with Singapore.

A Win-Win for Sustainability and Development

Singapore faces significant challenges in decarbonizing due to its lack of alternative energy resources Therefore, buying carbon credits seems like the most viable solution. Thus, the country can mitigate carbon emissions by funding projects with the parenting county.

Singapore carbon emissions

For Peru, this agreement provides access to international carbon markets, bringing investments into sustainable projects such as reforestation. Such projects not only address environmental goals but also promote local development, create green jobs, and foster innovation.

Peruโ€™s Deputy Minister of Strategic Development of Natural Resources of the Ministry of Environment, Ms Raquel Soto, said,

โ€œThe Implementation Agreement with Singapore brings significant benefits for Peru, enhancing our ability to address climate change while driving sustainable development. Through this agreement, we can access international carbon markets to channel investments into high-quality mitigation projects that support our environmental and economic goals. It reinforces Peruโ€™s leadership in leveraging Article 6 mechanisms of the Paris Agreement to promote innovation, create local green jobs, and achieve our climate commitments in a transparent and effective manner. This partnership with Singapore underscores the power of international cooperation in building a more sustainable future.โ€ย 

MTI emphasized Singapore’s commitment to upholding transparency, quality, and accountability in carbon markets. With these growing partnerships, the Southeast Asian nation can eventually be a leader in global carbon markets and trade carbon credits effectively. Last but not least, the country is leveraging international cooperation to address its sustainability challenges while supporting global climate goals.

Sources:

    1. Sโ€™pore and Peruโ€™s carbon trading agreement reaches advanced stage | The Straits Times
    2. Conclusion of Substantive Negotiation on IA with Peru

Indonesiaโ€™s Bold Push to Net Zero: Shutting Down All Coal Plants in 15 Years

Indonesia has unveiled an ambitious plan to transition away from fossil fuels and achieve net-zero emissions by 2050, a decade earlier than its previous target. Speaking at the G20 Summit in Brazil, President Prabowo Subianto announced a timeline to retire all coal-fired and fossil-fueled power plants within 15 years.ย 

From Coal to Clean: Indonesiaโ€™s 15-Year Plan for Energy Revolution

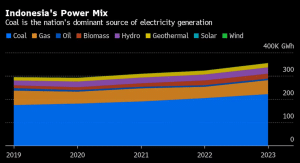
The Southeast Asian nation aims to replace its fossil fuel capacity with over 75 GW of renewable energy, utilizing its rich geothermal resources and expanding its solar and wind infrastructure. This commitment marks a significant shift for a country heavily reliant on coal and natural gas. These energy sources account for almost 80% of Indonesia’s electricity production.ย 

Indonesia Power Mix
Source: BloombergNEF

Indonesia’s coal-fired power emissions surpassed 185 million metric tons of COโ‚‚ equivalent (MtCOโ‚‚e) in 2023. This makes the country a significant contributor to global power sector emissions. With coal dominating its electricity mix, Indonesia remains heavily reliant on this fossil fuel for energy production.ย 

As of the end of 2023, Indonesiaโ€™s combined wind and solar capacity was less than 1 GW, per BloombergNEF data above. This underscores the vast scale of transformation required to meet its targets.ย 

Despite these challenges, the country is determined to pivot towards renewable energy and be a regional leader in the green energy transition.

Building on Global Partnerships

Indonesiaโ€™s ambitious agenda builds on the $20 billion Just Energy Transition Partnership (JETP) deal signed in 2022. This initiative, co-led by nations like the U.S., Japan, and European countries, aims to fund early coal plant retirements and accelerate renewable energy adoption.ย 

However, progress has been slow. Much of the pledged funding remains undelivered, with officials expressing the urgency of receiving the support to achieve its goals.

President Prabowoโ€™s announcement underscores Indonesiaโ€™s intent to lead by example, revealing a more aggressive approach toward reducing carbon emissions. His predecessor initiated the JETP deal, but Prabowoโ€™s leadership seeks to overcome the challenges that have stalled its progress.

Earlier this month, Indonesia inked a $10 billion agreement with China at the Indonesia-China Business Forum. The event focuses on economic growth in clean tech, biotechnology, water conservation, and mining.ย 

Indonesiaโ€™s nickel industry remained a focal point, with Chinese firms like GEM Co. partnering with PT Vale on a $1.42 billion HPAL plant. Investments by Tsingshan and Huayou Cobalt further affirm Indonesiaโ€™s vital role in supplying nickel for EVs, batteries, and green technologies.

Nickel and Nature: Leveraging Resources for Climate Goals

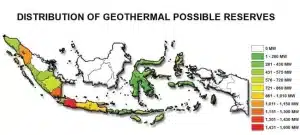
Indonesia plans to tap into its vast natural resources to drive its energy transition and reach net zero. The country is rich in geothermal energy, making it an ideal candidate for large-scale renewable energy projects.ย 

Geothermal reserves distribution in Indonesia
Source: Research Gate

Alongside geothermal, the government plans to expand solar and wind capacity to bridge the gap left by retiring fossil fuel plants.

Additionally, biodiesel production will play a significant role in the transition. Indonesia has been using palm oil to produce biofuels, and President Prabowo emphasized its importance in reducing dependence on coal and gas.ย 

Beyond energy generation, Indonesiaโ€™s expansive rainforests offer a unique opportunity to generate carbon credits. The country aims to produce over 550 million tons of carbon credits, helping offset emissions and contributing to the global fight against climate change.

In September, President Prabowo unveiled plans for a $65 billion green economy fund by 2028. This innovative fund will leverage carbon credit sales from large-scale environmental projects, including forest preservation and reforestation. Managed by a โ€œspecial mission vehicle,โ€ the initiative will centralize sustainable activities nationwide.ย 

Indonesia’s nickel industry is also pivotal to its economic strategy. In 2023, the country produced over half of the world’s mined nickel, solidifying its position as a leading global supplier of metallic commodities. Despite falling nickel prices, Indonesia’s cost-efficient production remains robust.

Bold Targets, Big Challenges: Will Indonesiaโ€™s Green Vision Succeed?

Hashim Djojohadikusumo, Indonesia’s climate envoy to COP29, outlined the nationโ€™s target to install 100 GW of new energy capacity over the next 15 years. Of this, 75%โ€”or 75 GWโ€”will come from renewable energy sources. These projects will add to the countryโ€™s existing installed capacity of over 90 GW, of which coal currently dominates.

The plan involves a massive budget of $235 billion, technology, and scientific expertise.

However, the scale of these ambitions raises questions about feasibility. With renewables currently accounting for less than 15% of Indonesiaโ€™s energy mix, the road to 75 GW of renewable capacity will require significant investments in infrastructure, technology, and workforce training.

Moreover, the nationโ€™s reliance on coal exports as a major revenue source adds economic complexity to the transition. Retiring coal plants will not only require financial support from international partners but also a clear strategy to manage the social and economic impacts on coal-dependent communities. Amid all these challenges, President Prabowoโ€™s leadership signals a new chapter in Indonesiaโ€™s energy policy.ย 

With global eyes on its progress, Indonesiaโ€™s journey to net zero will be a litmus test for the feasibility of large-scale energy transitions in emerging markets. If successful, it will show that even coal-reliant economies can shift toward sustainable energy with the right policies and support.