Silverโ€™s Industrial Demand Is Changing: AI, EVs and Power Infrastructure Are Rewriting the Market

Disseminated on behalf of Sierra Madre Gold & Silver Ltd.

Silver is no longer being driven by one industrial story. Solar remains one of the metalโ€™s biggest applications, but a broader technology shift is reshaping demand.ย ย 

Artificial intelligence, data centers, electric vehicles, electronics, and power-grid investment are creating new uses for silver across the global economy.

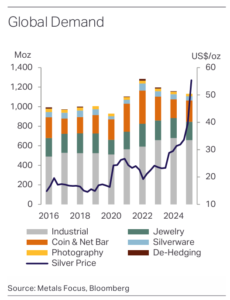
Industrial demand hit 657.4 million ounces in 2025. This made up over half of total global silver demand, as noted in the Silver Instituteโ€™s World Silver Survey 2026.ย 

Although industrial demand declined 3% last year because of weaker photovoltaic consumption, the underlying mix is changing. Structural growth in AI infrastructure, automotive applications, and electricity networks helped offset part of the decline in solar.

That shift matters for silver producers because the next demand cycle may be less dependent on any single end market.
silver industrial demand

Silver Is Becoming a Technology Metal

Silverโ€™s value in industrial applications comes largely from one property: electrical conductivity.

The metal is used in electrical contacts, circuit boards, switches, and power electronics. Itโ€™s vital for parts that need reliable conductivity. That makes silver increasingly relevant as the global economy becomes more electrified and more digitally connected.

The Silver Institute estimates a 2% drop in electrical and electronics demand for 2025. However, gains from grid infrastructure, automotive applications, and AI-driven electronics still support the sector.ย 

Those gains were not enough to offset falling photovoltaic demand, where manufacturers have accelerated efforts to reduce silver loadings through thrifting and substitution.

The result is an important distinction: silver demand can remain structurally tied to technology even when total industrial demand temporarily declines. That makes the composition of demand increasingly important.

AI Is Creating a New Silver Demand Channel

The growth of artificial intelligence is adding another layer to silver demand.

AI models need a lot of computing resources. This includes servers, processors, networking gear, power systems, and data centers. Silver is used throughout electrical and electronic equipment because of its conductivity and reliability.

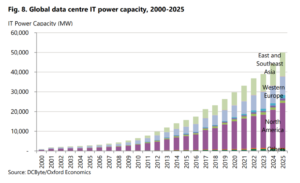
The Silver Institute’s 2025 tech report shows that global IT power capacity rose from 0.93 gigawatts in 2000 to almost 50 GW in 2025. That’s about a 53-fold increase. The organization expects data centers and AI-related technologies to remain important drivers of industrial silver consumption through 2030.
global data center IT power capacity

The connection is broader than AI chips themselves.

More computing requires more data center capacity. More data centers require more electricity. More electricity requires additional transmission, distribution, and power-management infrastructure. That creates multiple potential pathways for silver demand.

As AI adoption grows, the metal faces new demands. It is now needed for semiconductor production and the infrastructure for power-hungry computing systems.

EVs Add Another Layer of Electrical Demand

Transportation is undergoing a similar transformation.

Electric vehicles have more electrical parts than traditional internal-combustion vehicles. This opens up more uses for silver. Itโ€™s now found in electrical contacts, power electronics, battery management systems, and charging infrastructure.

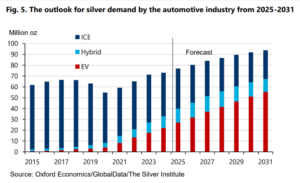
A Silver Institute report from Oxford Economics shows that battery-electric vehicles use 67% to 79% more silver than internal combustion vehicles. Each EV has about 25 to 50 grams of silver. It forecasts automotive silver demand to grow at a 3.4% compound annual growth rate between 2025 and 2031.
SILVER DEMAND OUTLOOK AUTOMOTIVE

The change is not limited to the vehicle itself. A larger EV fleet requires a larger charging network. That means additional electrical equipment, connections, and power infrastructure.

Oxford Economics predicts that by 2027, EVs will lead automotive silver demand. They expect EVs to make up 59% of this demand by 2031.

These figures show why electrification may be a long-term source of silver use. This is true even as manufacturers try to use less material.

Power Grids Could Become an Overlooked Silver Driver

The growth of AI and EVs ultimately leads back to electricity.

Data centers need power. EV charging requires power. Manufacturing, industrial automation, and broader electrification all require additional generation and transmission capacity.

Silver is used in electrical systems due to its excellent conductivity. This includes contacts, switches, and other electrical parts.

The Silver Institute specifically identified power-grid investment as one of the structural factors supporting electrical and electronics demand in 2025. This creates an important second-order effect for silver.

The world does not simply need more devices. It needs the electrical infrastructure capable of supporting those devices.

That means silver demand can be linked to several investment cycles at once:ย 

  • data center construction, vehicle electrification, renewable energy deployment, grid modernization, and broader industrial automation.

Solar Is Still Huge, But the Silver Story Is Changing

Solar remains critical to the silver market, but it is also where the industry is confronting one of its biggest challenges.

Photovoltaic demand helped drive years of industrial silver growth. However, manufacturers have increasingly reduced the amount of silver used per solar cell through thrifting and substitution.

The effect was significant in 2025.

Industrial silver demand fell 3% to 657.4 Moz, while the electrical and electronics segment declined 2%. The Silver Institute noted that the drop in PV demand was the main cause of the weakness. This happened even with ongoing gains from AI, automotive, and grid applications.

The Institute predicts that industrial demand will drop another 3% in 2026. This decline is mainly due to ongoing weakness in photovoltaic silver use. At the same time, it expects AI infrastructure, automotive applications and power-grid investment to remain areas of structural growth.
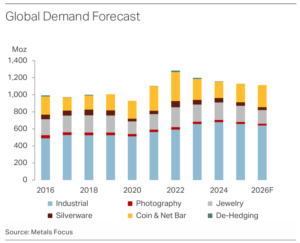
silver Global Demand Forecast

This does not make solar less important. Instead, it shows why the silver market is becoming more diversified.

The next phase of industrial demand may rely less on just adding more solar panels. Instead, it will focus on expanding digital infrastructure, transportation electrification, and electricity networks together.

A Changing Demand Mix Raises the Stakes for Supply

This evolution creates an unusual challenge for the silver market.

Demand is becoming increasingly connected to industries that governments and companies are investing in for long-term economic reasons. AI infrastructure, EV adoption, grid modernization, and digitalization are not single-year trends.

However, silver supply cannot necessarily respond at the same speed.

The Silver Institute reported that global mine production reached 846.6 million ounces in 2025, up 3%, while the market still recorded a deficit. Its 2026 outlook calls for mine production to remain broadly flat and projects another 46.3 million-ounce structural deficit.

That makes existing production capacity increasingly relevant. New mines can take years to permit, finance, build, and ramp up. Expansions and restarts at existing mining operations can happen more quickly. This is especially true when there is already processing infrastructure and mining facilities in place.

That is where Sierra Madre Gold & Silver enters the picture.

Sierra Madre Is Expanding Into a Changing Silver Market

Sierra Madre is building its production base while the industrial demand story is becoming more diversified.

At La Guitarra in Mexico, the company is boosting its current operation from 500 tonnes per day to 750โ€“800 tpd. They also plan to expand to 1,200โ€“1,500 tpd by Q3 2027. The company recently reported processing rates reaching as high as 720 tpd, showing the operation is already moving beyond its original 500-tpd level.
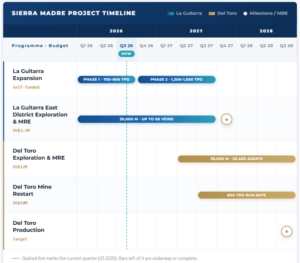
Sierra Madre Project Timeline

The expansion is designed around existing infrastructure rather than starting a new mine from scratch. Sierra Madre has increased its milling, crushing, material handling, and tailings capacity. It is also making progress in developing the Guitarra complex.

The company also now has Del Toro, a past-producing silver-lead-zinc complex in Zacatecas.

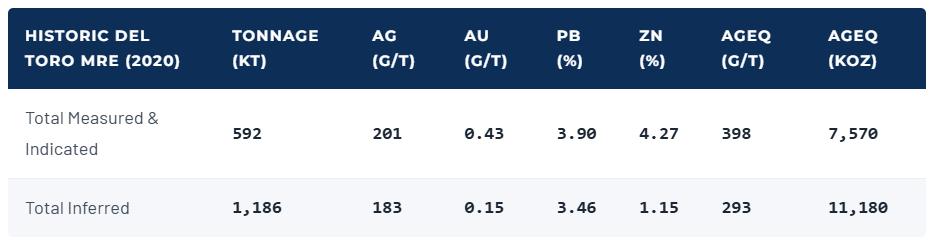
Del Toro includes three underground mines and a 3,000-tpd processing facility, along with more than 62.5 kilometers of underground development. Sierra Madre is evaluating a restart beginning at approximately 800 tpd, with potential to scale toward 1,600 tpd.ย 

Historic Del Toro MRE (2020)

The significance is not that one company can solve the global supply problem.

Sierra Madre shows how producers can meet a market linked to long-term tech and electrification trends. They can: expand current operations, restart old infrastructure, and build more production capacity.

The Silver Market Is Becoming More Electrified

Silver’s industrial story is entering a broader phase. Solar remains a major source of consumption, but AI, data centers, EVs, electronics, and power infrastructure are creating additional demand channels.ย 

Some applications will use less silver and become more efficient. But others will need more electrical equipment as economies go digital and electrified.

The result is a market where demand growth cannot be reduced to a single theme.

For producers, that creates a parallel challenge: supplying a metal that sits inside multiple growth industries while mine supply remains difficult to expand quickly.

Sierra Madreโ€™s La Guitarra expansion and Del Toro restart strategy provide a direct example of how established mining assets can be positioned to participate in that changing market.

The bigger question for silver is whether new supply can keep pace as the metal moves from being primarily a precious metal into an increasingly important industrial and technology input.

DISCLAIMER

New Era Publishing Inc. and/or CarbonCredits.com (โ€œWeโ€ or โ€œUsโ€) are not securities dealers or brokers, investment advisers, or financial advisers, and you should not rely on the information herein as investment advice. Sierra Madre Gold and Silver Ltd. (โ€œCompanyโ€) made a one-time payment of $25,000 to provide marketing services for a term of one month. None of the owners, members, directors, or employees of New Era Publishing Inc. and/or CarbonCredits.com currently hold, or have any beneficial ownership in, any shares, stocks, or options of the companies mentioned.

This article is informational only and is solely for use by prospective investors in determining whether to seek additional information. It does not constitute an offer to sell or a solicitation of an offer to buy any securities. Examples that we provide of share price increases pertaining to a particular issuer from one referenced date to another represent arbitrarily chosen time periods and are no indication whatsoever of future stock prices for that issuer and are of no predictive value.

Our stock profiles are intended to highlight certain companies for your further investigation; they are not stock recommendations or an offer or sale of the referenced securities. The securities issued by the companies we profile should be considered high-risk; if you do invest despite these warnings, you may lose your entire investment. Please do your own research before investing, including reviewing the companiesโ€™ SEDAR+ and SEC filings, press releases, and risk disclosures.

It is our policy that information contained in this profile was provided by the company, extracted from SEDAR+ and SEC filings, company websites, and other publicly available sources. We believe the sources and information are accurate and reliable but we cannot guarantee them.

CAUTIONARY STATEMENT AND FORWARD-LOOKING INFORMATION

Certain statements contained in this news release may constitute โ€œforward-looking informationโ€ within the meaning of applicable securities laws. Forward-looking information generally can be identified by words such as โ€œanticipate,โ€ โ€œexpect,โ€ โ€œestimate,โ€ โ€œforecast,โ€ โ€œplan,โ€ and similar expressions suggesting future outcomes or events. Forward-looking information is based on current expectations of management; however, it is subject to known and unknown risks, uncertainties, and other factors that may cause actual results to differ materially from those anticipated.

These factors include, without limitation, statements relating to the Companyโ€™s exploration and development plans, the potential of its mineral projects, financing activities, regulatory approvals, market conditions, and future objectives. Forward-looking information involves numerous risks and uncertainties and actual results might differ materially from results suggested in any forward-looking information. These risks and uncertainties include, among other things, market volatility, the state of financial markets for the Companyโ€™s securities, fluctuations in commodity prices, operational challenges, and changes in business plans.

Forward-looking information is based on several key expectations and assumptions, including, without limitation, that the Company will continue with its stated business objectives and will be able to raise additional capital as required. Although management of the Company has attempted to identify important factors that could cause actual results to differ materially, there may be other factors that cause results not to be as anticipated, estimated, or intended.

There can be no assurance that such forward-looking information will prove to be accurate, as actual results and future events could differ materially. Accordingly, readers should not place undue reliance on forward-looking information. Additional information about risks and uncertainties is contained in the Companyโ€™s managementโ€™s discussion and analysis and annual information form for the year ended December 31, 2025, copies of which are available on SEDAR+ at www.sedarplus.ca.

The forward-looking information contained herein is expressly qualified in its entirety by this cautionary statement. Forward-looking information reflects managementโ€™s current beliefs and is based on information currently available to the Company. The forward-looking information is made as of the date of this news release, and the Company assumes no obligation to update or revise such information to reflect new events or circumstances except as may be required by applicable law.

For more information on the Company, investors should review the Companyโ€™s continuous disclosure filings available on SEDAR+ at www.sedarplus.ca.

Disclosure: Owners, members, directors, and employees of carboncredits.com have/may have stock or option positions in any of the companies mentioned: None.

Carboncredits.com receives compensation for this publication and has a business relationship with any company whose stock(s) is/are mentioned in this article.

Additional disclosure: This communication serves the sole purpose of adding value to the research process and is for information only. Please do your own due diligence. Every investment in securities mentioned in publications of carboncredits.com involves risks that could lead to a total loss of the invested capital.

Please read our Full RISKS and DISCLOSURE here.

GEVO Stock Slips Despite Signing 3-Year Carbon Credit Supply Agreement With CEEZER

Gevo, Inc. (NASDAQ: GEVO) has signed a three-year carbon removal credit supply agreement with CEEZER, adding another corporate buyer to its growing carbon business. The deal will supply durable carbon dioxide removal (CDR) credits from Gevoโ€™s North Dakota ethanol facility through 2029.

Announced on October 14, the agreement marks Gevoโ€™s first multi-year carbon removal contract with CEEZER. The company expects the growing business to generate more than $30 million in annual carbon revenue from its existing operations.

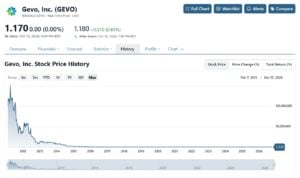
However, GEVO stock fell 9.3% on October 14, closing at $1.17, compared with $1.29 a day earlier. Shares remained at $1.17 at the close on October 15. The decline coincided with the announcement, although the available data does not establish that the deal caused the drop.

gevo stock
Source: Stock Analysis

Nonetheless, the agreement strengthens Gevoโ€™s carbon credit sales pipeline as companies seek long-term supplies of durable removals. However, investors will need more information about contract pricing, delivery volumes, and revenue recognition to assess its direct financial impact.

Gevo Signs Three-Year Carbon Removal Deal With CEEZER

  • Under the agreement, Gevo will supply a five-figure volume of carbon removal credits to CEEZER through 2029. CEEZER will procure and manage the portfolio for an unnamed Fortune 500 enterprise software company.

The companies have not disclosed the exact number of tonnes covered by the contract or its financial value.

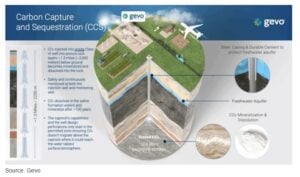
Gevo will generate the credits at its North Dakota facility, where the company captures biogenic carbon dioxide released during ethanol fermentation and stores it in deep geological formations.

According to Gevo, the facility stores COโ‚‚ more than a mile underground, with expected permanence exceeding 1,000 years. The project also operates without a dedicated COโ‚‚ pipeline.

The process uses bioenergy with carbon capture and storage (BECCS), which combines biomass-based production with carbon capture and permanent storage. When projects account for emissions across the production process, this approach can remove more carbon dioxide from the atmosphere than it releases.

gevo north dakota

Gevo says its North Dakota project is among the first commercial-scale U.S. BECCS facilities delivering verified carbon removal credits to the voluntary carbon market.

The company has also supplied credits to organizations including Nasdaq and Whirlpool. Its carbon removal certificates have appeared in the Puro.earth registry through purchases involving other buyers and intermediaries.

The CEEZER agreement gives Gevo another route to corporate customers and extends its contracted sales pipeline through 2029.

CEEZER Senior Vice President of Sourcing & Delivery Stephan Fuechtenhans, said:

โ€œCompanies building carbon removal portfolios increasingly need certainty of supply, price and quality over several years, not just individual purchases. Seeing Gevoโ€™s operation, including on-site storage and supply chain, during our teamโ€™s recent site visit confirmed the kind of traceability our clients look for. Long-term offtakes with suppliers that combine an operating project with a proven delivery record are becoming central to how companies meet their long-term climate goals.โ€

Durable Carbon Removal Demand Grows, but Deliveries Lag

Gevoโ€™s latest agreement comes as the durable carbon removal market expands. However, the gap between contracted purchases and delivered credits remains a major industry challenge.

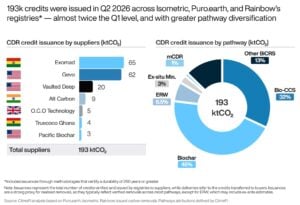
Suppliers delivered 145,000 tonnes during the quarter, up 67% year over year. Buyers retired just over 100,000 tonnes. Biochar carbon removal accounted for 93% of newly contracted volume, while biomass-based carbon removal methods dominated deliveries.

GEVO CDR

The figures show that market demand is growing, but suppliers still need to turn contracts into verified deliveries. Long-term agreements can help developers plan production and give buyers greater confidence about future credit availability.

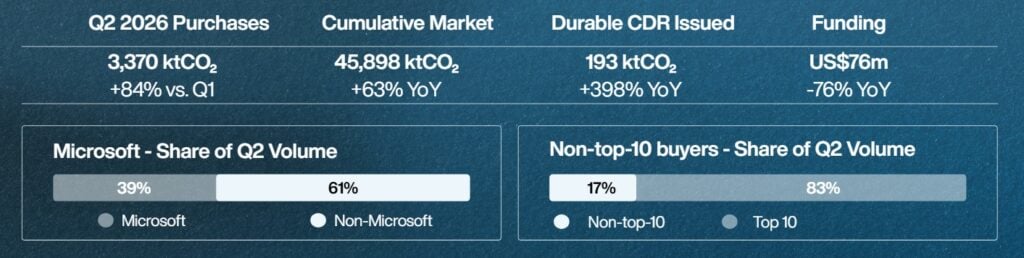
According to ClimeFiโ€™s Q2 2026 CDR Market Review, buyer commitments increased by 83% from the first quarter. Purchases from buyers other than Microsoft also reached a record high, with non-Microsoft commitments rising 136% year over year. These trends suggest that demand is broadening beyond the marketโ€™s largest corporate buyer.

carbon credits BECCS
Source: ClimeFi 2026 Q2 CDR market review

The quarter also marked a shift in purchasing patterns. Bioenergy with carbon capture and storage (Bio-CCS) overtook biochar to become the largest contributor to quarterly purchase volumes for the first time in more than a year. Credit issuances nearly doubled from the first quarter, according to ClimeFi.

For Gevo, existing ethanol production and carbon storage infrastructure provide a potential advantage because the company can generate removal credits alongside its core operations. However, future sales will depend on available credit volumes, buyer demand and the project’s ability to maintain verification standards.

Gevo Targets More Than $30 Million in Annual Carbon Revenue

The company is building its carbon business alongside its renewable fuels operations. In a June 2026 update, the company said first-half carbon removal sales had already surpassed its total 2025 sales, with deliveries on schedule.

Gevo also reported that its North Dakota facility had issued more than 500,000 carbon dioxide removal certificates since carbon capture and storage activities began in June 2022. The company sells these certificates under the Puro.earth standard.

Gevo CDR
Source: ClimeFi 2026 Q2 CDR market review

It expects its carbon business to generate more than $30 million in annual revenue from existing operations. The CEEZER agreement supports that objective, although the undisclosed contract value makes it difficult to estimate how much revenue the deal will contribute.

Section 45Z Tax Credit Revenue

Gevo is also monetizing government incentives tied to low-carbon fuel production. On October 1, it announced that it had sold substantially all the Section 45Z tax credits it expected to generate in 2026, representing $70 million. The company had received more than $30 million in cash from those sales through September 30 and expected the remaining proceeds over the following six months.

It also forecast more than $77 million in Section 45Z credits for 2027. Planned improvements at its North Dakota facility could increase production capacity and carbon capture volumes by 10% to 15%, supporting additional credit generation.

Section 45Z credits are separate from carbon removal credits. The government incentive supports qualifying low-emission transportation fuel production, while CDR credits are sold to buyers seeking verified carbon removals.

What the CEEZER Deal Means for GEVO Stock

The agreement adds another potential source of recurring revenue for Gevo and supports its strategy of generating additional value from existing infrastructure.

For investors, the key question is whether carbon credit sales can become a material and predictable contributor to the company’s financial performance. The $30 million annual revenue target provides a benchmark, but Gevo has not disclosed the CEEZER contract’s pricing or enough detail to quantify its contribution.

GEVO shares’ decline on October 14 also highlights why investors should distinguish a commercial milestone from its immediate stock-market impact. One session’s price movement does not establish how the market values the contract or whether the announcement influenced trading.

Going forward, investors will be watching carbon credit deliveries, realized prices, additional long-term agreements and progress toward the company’s revenue target. Gevo’s ability to turn growing demand for durable carbon removals into consistent cash-generating sales will be central to the investment case.

Google and McKinsey Back Brazil Silvopasture Project in 320,000-Tonne Carbon Removal Deal

Google and McKinsey are backing a new carbon removal project in Brazil that aims to store carbon while keeping cattle farming productive. The deal could help bring a nature-based climate solution to a larger scale and create a new source of income for ranchers.

The two companies agreed to buy 320,000 metric tonnes of carbon removal credits over 10 years from a project developed by climate technology company Working Trees. The purchase is part of the Symbiosis Coalition, a group of major corporate buyers seeking long-term supplies of nature-based carbon removal credits.

The project will initially restore 8,700 hectares of degraded and partly degraded cattle pasture in Brazil’s southeastern Amazon and Cerrado regions. It forms part of a wider 50,000-hectare effort.

The approach is called silvopasture, which combines trees, pasture, and livestock on the same land. Trees absorb carbon as they grow, while cattle can continue grazing.

The agreement highlights a growing role for corporate carbon finance: helping projects secure money before they generate credits. Yet, the climate benefits will depend on how much carbon the project removes, how that removal is measured, and whether the carbon remains stored over time.

Julia Strong, Executive Director of Symbiosis Coalition, remarked:

โ€œSilvopasture is one of the most underused tools we have for nature-based carbon removal, and what excites us about the Working Trees project is how much room there is to scale it. Working Trees’ project is sequestering carbon while also improving the land that communities rely on. That’s the kind of outcome we strive for at Symbiosis, real climate impact that supports the livelihoods of the communities this project touches while thinking holistically about landscape-level impacts that last.โ€

Silvopasture: How Trees and Cattle Can Share the Same Pasture

Traditional cattle pasture often has few trees. Silvopasture adds rows of trees to grazing land, allowing ranchers to keep cattle while increasing tree cover.

Working Trees says it combines native trees with commercial timber species and other trees suited to the land. The trees can absorb carbon, provide shade, improve soil conditions, and create additional income through timber sales. The company also says shade can reduce heat stress in cattle and help pastures cope with hot and dry conditions.

This matters in Brazil, where cattle farming is a major part of agriculture and land conversion is an important source of environmental pressure. Restoring degraded pasture could improve land productivity and reduce the need to clear additional areas for farming.

However, silvopasture is not the same as restoring a natural forest. The project must balance tree growth, grazing, and farm income. Its climate value will depend on the amount of carbon stored in trees and soil, minus relevant project emissions and any carbon losses.

Why the 320,000-Tonne Purchase Matters

The Google and McKinsey agreement gives Working Trees long-term buyers for a large share of its planned carbon removal. The companies have not publicly disclosed the purchase price or a detailed delivery schedule.

Long-term purchase agreements, often called offtake agreements, can help carbon project developers raise money and plan future work. Buyers agree to buy credits that meet specified requirements, often before all the credits have been generated.

This can help address some of the main barriers facing nature-based projects:

  • the high upfront cost of planting trees,
  • working with landowners, and
  • monitoring results over many years.

Working Trees says it covers most implementation costs for participating farmers and provides technical support. That can lower the financial burden on ranchers who want to change how they manage their land.

The company reports that it has planted about 450,000 trees across 2,167 hectares with 18 partner farmers. It also reports interest from landowners covering 200,000 hectares. These are company-reported figures, not independently verified measures of carbon removal.

The new deal could help the company expand beyond its existing projects. Still, the 320,000 tonnes represent contracted carbon removal, not carbon already removed from the atmosphere.

Corporate Buyers Are Building a Larger Carbon Removal Market

The agreement is part of a wider push by companies to secure future carbon removal. Google, Microsoft, Meta, and Salesforce are among the companies involved in the Symbiosis Coalition. The group aims to contract more than 20 million tonnes of carbon credits by 2030, with a focus on nature-based carbon removal.

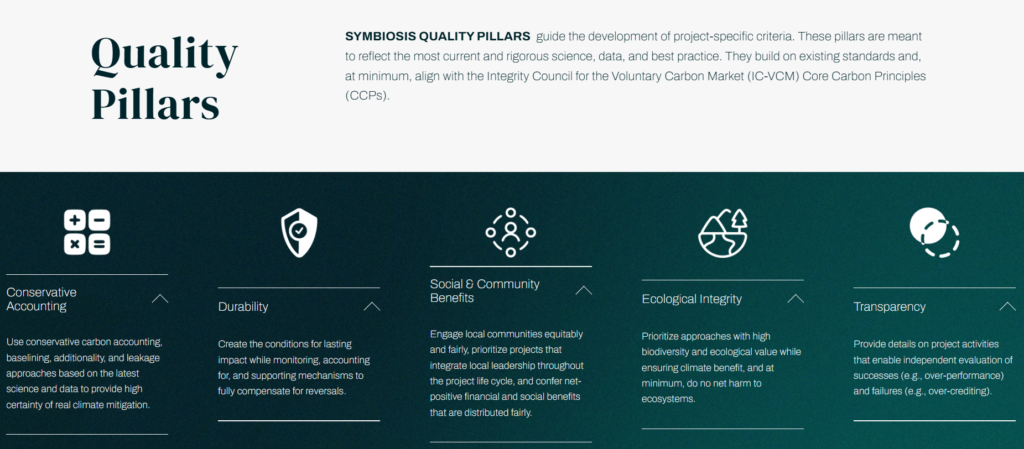
Symbiosis Coalition quality criteria
Source: Symbiosis Coalition

This demand can help developers secure funding for projects that take years to grow and deliver measurable results. Market data also show why nature-based removal matters.

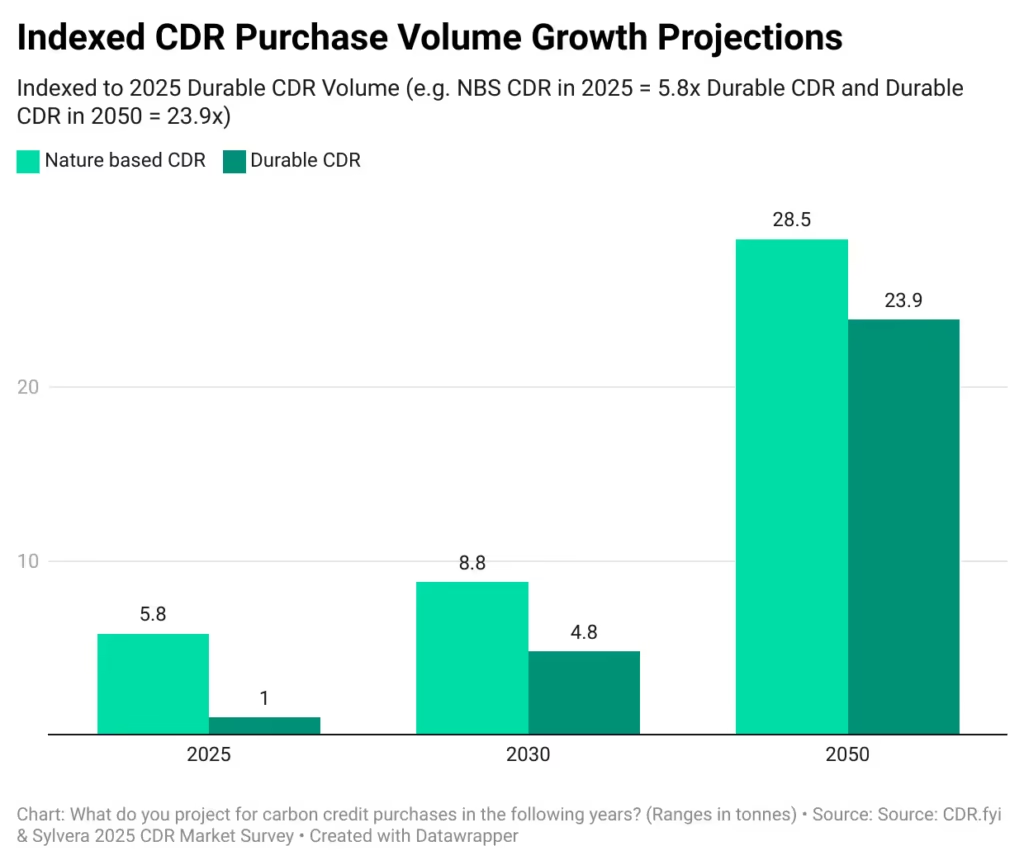
A 2025 survey by CDR.fyi and Sylvera found that nature-based carbon removal was much larger than durable carbon removal in terms of credits retired in 2024:

  • About 11 million nature-based credits compared with roughly 200,000 durable removal credits.

Nature-based projects can often be deployed across large areas, but they face risks such as fires, drought, pests, and changes in land use. Durable removal methods, such as direct air capture with storage, can offer longer-lasting storage but often have higher costs and greater energy needs.

carbon removal credits nature-based versus durable
Source: Sylvera

The two approaches serve different roles. This Brazilian deal shows how corporate buyers are helping build a supply of nature-based removal credits while seeking projects that can expand over time.

Brazil’s Carbon Market Adds Another Layer to the Investment Opportunity

Brazil has major potential for land-based climate projects because of its large agricultural sector, forests, and areas of degraded pasture.

McKinsey has estimated that Brazil could become a major global supplier of carbon removal credits. Its analysis points to restoration of degraded pasture, reduced deforestation, and improved land management as important opportunities. These are estimates of potential, not guaranteed future credit supply.

The country is also building a regulated carbon market. In December 2024, Brazil passed Law No. 15,042, which created the Brazilian Greenhouse Gas Emissions Trading System, known as the SBCE. The government is now working on the rules, governance, monitoring systems, and registry needed to implement it.

The Working Trees deal is a voluntary carbon removal agreement, not a transaction under the new regulated system. Even so, the wider policy effort could shape how carbon projects are measured and how buyers assess credits in Brazil.

For developers, a clearer market framework could support investment. For buyers, the challenge will remain to distinguish credible carbon removal from credits that overstate their climate benefits.

Carbon Quality Will Determine the Project’s Long-Term Value

The deal’s scale is important, but the project’s credibility will depend on how it measures and verifies carbon removal.

Tree growth can be measured over time, but carbon projects must also account for what would have happened without the project. They need to show that the activity creates additional climate benefits rather than simply paying for changes that were already planned.

Projects must also manage the risk of reversal. Trees can burn, die, or be cut down, releasing stored carbon. Soil carbon can also change with land management. Long-term monitoring and clear rules for handling carbon losses are therefore essential.

Working Trees says future timber revenue is part of its model. Whether that income is enough to support long-term maintenance remains to be demonstrated at scale.

Google and McKinsey Back Carbon Removal Brazil

Can Corporate Carbon Finance Help Silvopasture Scale?

Google and McKinsey’s 320,000-tonne purchase gives Working Trees long-term demand for carbon removal credits and supports the initial restoration of 8,700 hectares of Brazilian pasture.

The project offers a model that links carbon finance with continued cattle production, tree growth, and potential timber income. If it performs as planned, it could help show how degraded land can support both farming and carbon removal.

But the deal is not proof that all the expected carbon has been removed. The project must still deliver its planned work, measure results, and manage risks over time.

For the carbon market, the key test is whether long-term corporate purchases can turn promising land-based projects into verified, lasting carbon removal while creating lasting value for farmers.

Philippines Moves to Build National Carbon Market Under New Executive Order

The Philippines is taking a major step toward building a national carbon market. President Ferdinand Marcos Jr. has ordered the government to develop a policy framework to guide carbon credit projects, attract investment, and support the country’s climate goals.

Under Executive Order No. 127, signed on October 13, 2026, the Department of Environment and Natural Resources (DENR) will lead the development of the Philippine Carbon Market Policy Framework. The order also creates an inter-agency committee to guide the process and names the DENR as the country’s main authority for carbon markets.

The framework will set rules for carbon projects, credit trading, monitoring, and benefit-sharing. It will cover both voluntary carbon markets and international trading under Article 6 of the Paris Agreement. The DENR must submit the proposed framework to the committee for review and approval within 30 days after the order takes effect.

The move could help bring more funding to forest protection, clean energy, farming, and other projects that cut or remove greenhouse gas emissions. However, the detailed rules still need to be developed, and the impact will depend on how the system is put into practice.

Marcos Orders National Carbon Market Rules

Executive Order No. 127 aims to give the Philippines a clearer and more coordinated approach to carbon markets. The government wants the framework to support climate goals while opening the door to investment, funding, and technology. The EO read:

“There is a need to formulate a national carbon market framework aligned with international standards, through a whole-of-government approach, to support the achievement of the countryโ€™s NDCs (nationally determined contributions).”

Carbon markets allow companies and other buyers to purchase credits from projects that reduce or remove greenhouse gas emissions. One carbon credit usually stands for one metric ton of carbon dioxide equivalent. These credits are based on specific rules and standards.

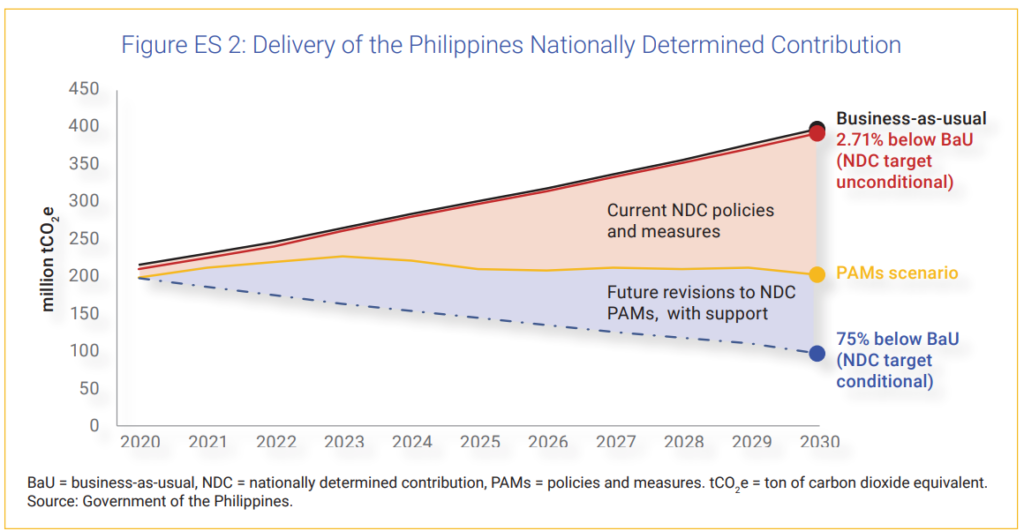
Philippines Nationally Determined Contribution
Source: Climate Change Commission

Selling carbon credits can help fund projects that may struggle to secure enough money through other sources. The new framework will establish rules for:

  • Which projects qualify,
  • How credits are issued and transferred,
  • Accepted carbon standards, and
  • How projects report results.

It will also cover environmental and social safeguards and how project benefits should be shared. These rules could support projects in forestry, renewable energy, agriculture, and other sectors.

The order does not create a new carbon tax. Instead, it sets the direction for regulating carbon market activities and developing a more coordinated system for carbon projects.

DENR Takes the Lead as Agencies Join Carbon Market Committee

The order names the DENR as the national authority for carbon markets. It will oversee eligible projects and help ensure they follow national rules and environmental policies.

An Inter-Agency Committee on Carbon Markets (IACCM) will coordinate government policy and review the proposed framework. The Climate Change Commission will chair the committee, while the Department of Finance will serve as vice chair. Other members include:

  • DENR, Department of Energy, Department of Agriculture, Department of Transportation, Department of Trade and Industry, and the Securities and Exchange Commission.

These agencies cover areas that can affect carbon projects, from climate policy and land use to energy, transport, business, and finance. Their cooperation will be important because projects may need several permits and must meet different technical and reporting requirements.

The committee will review how the framework is applied. It will also approve fair fees for carbon market applications and certifications.

Philippines Plans National Registry to Track Carbon Credits

The government will establish a Philippine National Carbon Registry, which the DENR will manage. The digital system is intended to record carbon credits and related transactions. It should help regulators track credits and reduce the risk of the same emissions reduction being counted more than once.

This matters when credits are sold to different buyers or transferred between countries. If the same emissions reduction is claimed more than once, the climate benefit becomes less reliable.

The framework will also set rules for measuring and checking emissions reductions, approving international transfers, and reporting transactions. These requirements could help buyers assess credits and give project developers a clearer process for selling them in eligible markets.

However, the registry’s value will depend on how well the government checks project data, tracks credits, and enforces the rules.

Opening the Door to International Carbon Trading

The framework will cover both voluntary carbon markets and international trading under Article 6 of the Paris Agreement. In voluntary markets, companies and other organizations buy credits to support their climate goals. Eligible projects may include forest conservation, reforestation, renewable energy, farming, and waste management.

Article 6 allows countries to work together to meet their climate targets. Under Article 6.2, countries can transfer approved emissions reductions or removals, known as internationally transferred mitigation outcomes (ITMOs).

These transfers require government approval and proper accounting. Countries must follow the rules. This stops the same emissions reduction from counting for more than one climate target.

The new framework will set rules for approving international transfers. It will also manage carbon credits. This could help Philippine projects reach international buyers. However, approval under the national framework will not automatically mean that every credit qualifies for every market or buyer.

New National Framework Builds on Existing Sector Rules

The Philippines is not starting from zero. Several government initiatives have already laid the groundwork for carbon market development.

In 2025, the Department of Energy issued a framework for generating, managing, and monitoring carbon credits in the energy sector. It covers issues such as measuring emissions reductions, checking results, credit ownership, and preventing double counting.

The DENR set rules for forest carbon projects. In 2021, they issued an order to measure, verify, and certify forest carbon activities. Executive Order No. 127 creates a national framework. This aims to unite efforts and set broader rules for voluntary and international carbon markets.

The next challenge will be to align existing sector rules with the new framework. Project developers, communities, investors, and buyers will need clear guidance on how the different requirements work together.

Philippines national carbon market framework

Clearer Rules Could Open New Opportunities for Investors and Communities

Clearer rules could make the Philippines more attractive to companies looking to develop carbon projects. Possible areas include forest restoration, forest protection, renewable energy, better farming practices, and waste management. These projects must show that they reduce or remove emissions and meet the relevant standards before they can generate eligible credits.

For investors, clear approval and reporting rules could make it easier to assess project risks. A national registry could also improve transparency by providing a central record of credits and transactions.

Communities and farmers may benefit through project funding, jobs, or a share of revenue. But these benefits are not guaranteed. The final rules and each project’s agreements will help determine how money is shared.

Strong checks will also be important. Projects must prove their claimed emissions cuts or removals, follow environmental and social safeguards, and avoid double counting.

Carbon credits are not guaranteed income. Projects may need upfront funding, technical studies, monitoring, independent checks, and government approval. Revenue will depend on the credits generated, their quality, buyer demand, and the terms of each project.

Will the Philippines’ Carbon Market Gain Momentum?ย 

Executive Order No. 127 gives the Philippines a clearer national plan for developing its carbon markets. It assigns the DENR a leading role, creates an inter-agency committee, and provides for a national registry.

The framework could help attract funding for projects that cut emissions or remove carbon from the atmosphere. It may also create new opportunities for developers, investors, and local communities.

But the order is only the first step. The government still needs to develop the detailed rules and put systems for project approval, verification, reporting, and credit tracking into practice.

The key test will be whether the new framework provides clear rules, attracts investment, and ensures that carbon credits deliver real climate benefits while sharing project gains fairly with local communities.

Global COโ‚‚ Transport Industry to Reach $211 Billion by 2060, Wood Mackenzie Says

The global COโ‚‚ transport industry could attract $211 billion in investment by 2060 as countries build more infrastructure to capture and store carbon emissions. A new analysis from Wood Mackenzie, published on October 14, estimates that the industry could transport 3 billion tonnes of carbon dioxide (COโ‚‚) each year, including 200 million tonnes across international borders.

The forecast highlights the growing role of transport infrastructure in carbon capture, utilisation and storage (CCUS). Companies must do more than capture COโ‚‚ from factories and industrial facilities. They also need pipelines or specialised ships to move the gas to locations where they can use it or store it underground.

As more carbon capture projects emerge, pipelines and COโ‚‚ shipping networks could create investment opportunities across the energy and industrial sectors. However, transport costs, storage availability and government policies will shape the industry’s growth.

Asia Pacific to Drive COโ‚‚ Transport Investment

Wood Mackenzie expects Asia Pacific to attract nearly 60% of global COโ‚‚ transport investment through 2060, followed by North America and Europe.

The region faces a mismatch between industrial emissions and available storage sites. Japan, South Korea, Singapore and Taiwan could generate significant demand for COโ‚‚ transport, while Australia, Indonesia and Malaysia could provide storage capacity.

  • By 2060, demand for cross-border COโ‚‚ transport from Japan, South Korea, Singapore and Taiwan could reach 164 million tonnes per annum (Mtpa).
  • Australia and Southeast Asia could offer 187 Mtpa of storage capacity to meet this demand.

Japan illustrates the challenge. The country aims to store 120 million to 240 million tonnes of COโ‚‚ annually by 2050. However, limited domestic storage options could force it to rely more heavily on overseas facilities.

Wood Mackenzie estimates that Japan may need to ship nearly 50 Mtpa of COโ‚‚ to other countries. For comparison, Japan imports around 65 million tonnes of liquefied natural gas (LNG) annually.

Transporting COโ‚‚ across borders could add about $40 per tonne, accounting for nearly 30% of the total levelised cost of carbon capture and storage (CCS) in some cases. These additional costs could influence project returns and determine which transport routes companies choose.

Pipelines to Account for More Than 80% of Investment

Wood Mackenzie expects pipelines to attract more than 80% of global COโ‚‚ transport investment. Pipelines can connect industrial facilities to onshore and offshore storage sites and move large volumes of captured COโ‚‚ through shared networks.

However, developers must spend heavily on pipeline construction, steel, and supporting facilities. Operators also need a steady supply of COโ‚‚ to recover these costs. Permitting delays, land acquisition, and regulatory uncertainty can further increase expenses.

Companies could reduce these costs by converting suitable natural gas pipelines to transport COโ‚‚. Wood Mackenzie estimates these conversions could cut capital expenditure by more than 60% and halve total transport costs.

However, developers cannot convert every existing gas pipeline. They must assess each pipeline’s technical condition, suitability and safety requirements before repurposing it.

Specialised ships offer another option, particularly when industrial facilities sit far from storage sites or across international waters. These vessels carry liquefied COโ‚‚ between export terminals and storage hubs.

Wood Mackenzie highlights several factors that could influence transport costs:

  • Pipeline and shipping costs can be comparable over distances of up to 1,000 kilometres, depending on project conditions and existing infrastructure.
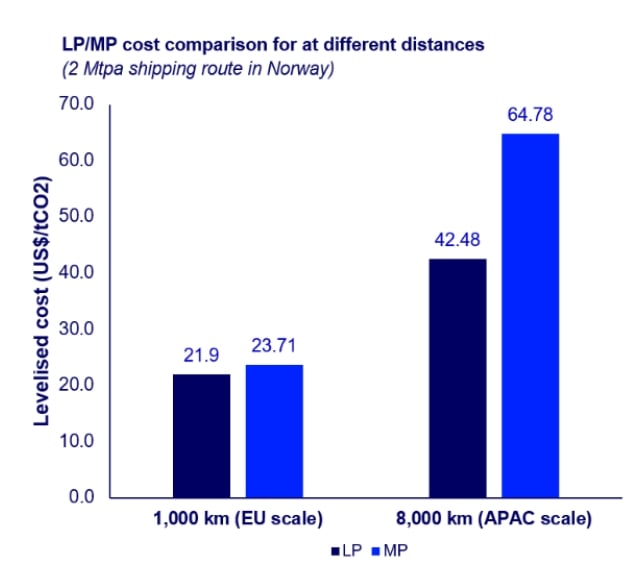
  • Low-pressure COโ‚‚ vessels could cut long-distance shipping costs by up to 34% compared with medium-pressure alternatives.
  • Fuel and electricity account for more than 50% of the levelised cost of COโ‚‚ shipping.
  • In Japan, shipping could become more cost-effective than offshore pipelines for distances exceeding 400 kilometres at a transport volume of 5 Mtpa.

These figures show that companies must weigh transport distance, COโ‚‚ volumes and infrastructure costs when selecting the most economical option.

global co2 transport
Source: Wood Mackenzie

Carbon Capture Needs Reliable Transport Networks

CCUS projects need an integrated system that connects industrial facilities, transport networks and storage sites.

Cement, steel and chemical producers could use carbon capture to reduce emissions from processes that are difficult to decarbonise. Companies can transport captured COโ‚‚ to suitable geological formations and inject it underground for long-term storage.

However, building capture facilities alone will not guarantee that companies can transport and store COโ‚‚ at the required scale. Limited pipeline capacity, insufficient shipping infrastructure, and delays in developing storage sites could restrict project operations.

This challenge could create opportunities for investors across several areas:

  • Pipeline construction and conversion
  • COโ‚‚ liquefaction equipment and export terminals
  • Specialised COโ‚‚ carriers and shipping services
  • Geological storage development and monitoring

Companies could also lower costs by connecting several industrial emitters to shared transport and storage networks. These hubs can spread infrastructure expenses across multiple customers and improve utilisation.

The climate benefits depend on how much COโ‚‚ companies capture, the emissions generated during capture and transport, and the security of long-term storage. Transporting fossil-derived COโ‚‚ for permanent storage can prevent emissions from entering the atmosphere, but it does not automatically qualify as carbon removal.

Policy Will Shape the Industry’s Growth

Governments must establish clear rules to support cross-border COโ‚‚ transport. International projects need agreements that define transport standards, storage permits, long-term liability, and responsibility for monitoring stored carbon.

Wood Mackenzie identifies gaps in bilateral agreements, liability frameworks, and economic incentives as barriers to cross-border CCUS development. These issues matter particularly in Asia Pacific, where several countries could depend on international transport networks and overseas storage sites.

Governments will need to coordinate infrastructure planning and establish clear regulatory frameworks. Developers must also secure reliable access to storage facilities and enough committed COโ‚‚ volumes before investing in large transport projects.

The projected $211 billion investment opportunity highlights the potential scale of the global COโ‚‚ transport industry. Asia Pacific’s growing demand, the expected dominance of pipelines and the expansion of specialised shipping could shape the market over the coming decades.

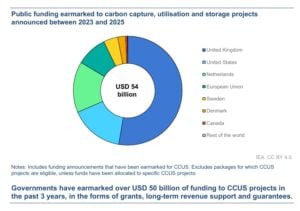
Here’s another data from the IEA that highlights funding prospects:

IEA CCUS
Source: IEA

However, the forecast does not guarantee future investment. The industry will need commercially viable projects, sufficient storage capacity and supportive policies to move captured COโ‚‚ efficiently from industrial facilities to permanent storage sites.

TeraWulf (WULF) Stock: Can Low-Carbon Power Fuel Its AI Data Center Boom?

TeraWulf Inc. (NASDAQ: WULF) is moving beyond Bitcoin mining to become a major provider of data center infrastructure for artificial intelligence (AI). A growing deal pipeline, including a long-term agreement with AI company Anthropic, has put the company in the spotlight as demand for computing power rises.

However, TeraWulf’s growth story is about more than AI. It also depends on access to electricity, the cost of running data centers, and the environmental impact of powering thousands of computer servers.

The company says its access to low- and zero-carbon power gives it an advantage as demand for AI infrastructure grows. Its reported energy mix supports that claim, but questions remain about future power needs, emissions, and the impact of new data centers on local communities.

For investors, the key question is whether TeraWulf can turn its energy strategy into a lasting business advantage while meeting its growth targets.

Anthropic Deal Puts TeraWulf’s AI Growth in Focus

TeraWulf’s move into AI infrastructure gained momentum in July 2026, when it announced a 20-year data center lease with Anthropic. The agreement covers about 401 megawatts (MW) of computing capacity at TeraWulf’s Justified Data Campus in Kentucky.

The company expects the first lease term to generate around $19 billion in contracted revenue. It could go up to about $33 billion if Anthropic chooses to extend for two five-year options.

  • Initial delivery is expected in the second half of 2027, with full delivery planned for early 2028.

The deal is a big step for TeraWulf. It shows their move from Bitcoin mining to high-performance computing (HPC). This shift includes systems used for AI and other tough tasks.

CEO Paul Prager has described the Anthropic agreement as only the beginning of a much larger market. In comments reported by Stocktwits, he pointed to rising demand for AI computing and limited access to ready-to-use power infrastructure.

This matters because building an AI data center requires more than computer chips. Operators also need reliable electricity, cooling systems, grid connections, and suitable sites.

TeraWulf is betting that its existing energy infrastructure and development experience will help it meet this demand. However, the $19 billion figure represents expected revenue over the lease term, not profit or cash already received. The company must still build and deliver the planned capacity.

Low-Carbon Power Could Support Its Competitive Position

Power is one of the highest costs and challenges for large data centers. As AI systems grow, operators need more electricity to run servers and cooling equipment. TeraWulf’s 2025 corporate sustainability report provides a useful look at its energy strategy.

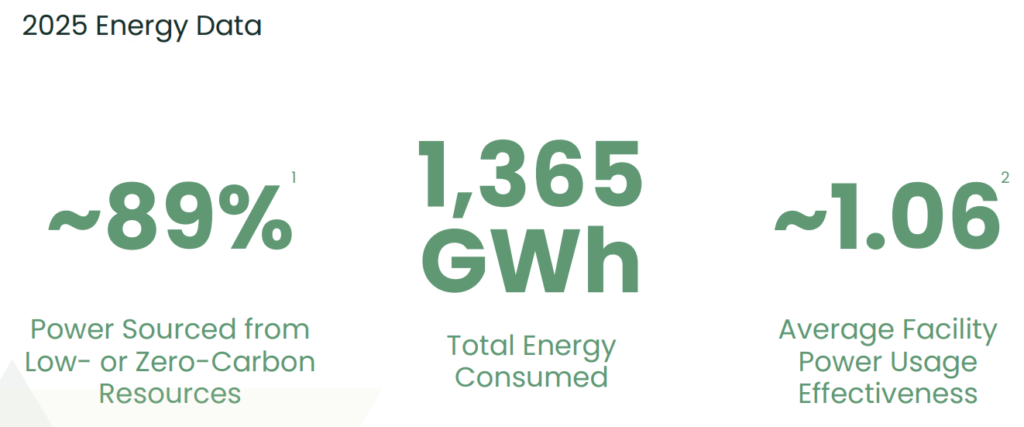
  • The company reported that about 89% of its power came from low- or zero-carbon resources in 2025. It also reported an average power usage effectiveness (PUE) of about 1.06 across its operations.
terawulf energy data
Source: TeraWulf

PUE measures how much total energy a data center uses compared with the energy delivered to its computing equipment. A score closer to 1.0 generally means less energy is spent on supporting systems, such as cooling and power distribution. These figures suggest that TeraWulf has access to relatively low-carbon electricity and operates its facilities with a focus on energy efficiency.

Its Lake Mariner campus in New York benefits from a grid with a large share of nuclear, hydropower, and wind generation. The site is on a former coal-fired power plant. This lets the company use existing industrial land and electrical systems.

This approach could help TeraWulf limit the need for new land development and reduce some of the challenges involved in connecting large facilities to the grid. Still, access to low-carbon electricity does not mean that data centers have no environmental impact.

Construction, equipment, backup power, and rising electricity demand all matter. The company’s reported power mix also does not, by itself, show its total greenhouse gas emissions.

AI Growth Brings New Energy and Emissions Questions

AI can help businesses improve efficiency, but running AI systems also requires large amounts of electricity. As more companies use advanced AI models, the demand for data center capacity is expected to grow.

  • This creates an important challenge for the industry: how to expand computing power without placing too much pressure on electricity supplies or increasing emissions.

The climate impact of an AI data center depends partly on where its electricity comes from. A facility powered mainly by low-carbon sources can have a lower electricity-related emissions footprint than one relying heavily on coal or natural gas.

However, even a relatively low-carbon data center can add pressure to the grid if it uses large amounts of electricity. More demand may require new generation, transmission lines, and other infrastructure.

TeraWulf’s energy strategy may ease some concerns. However, its future impact depends on the power sources available as its facilities grow.

Investors should also look at how the company reports energy use and emissions as it shifts from Bitcoin mining to AI computing. More detailed, comparable data would help show whether its environmental performance improves as the business grows.

WULF Stock Shows Signs of a Rebound, But What Should Investors Watch?

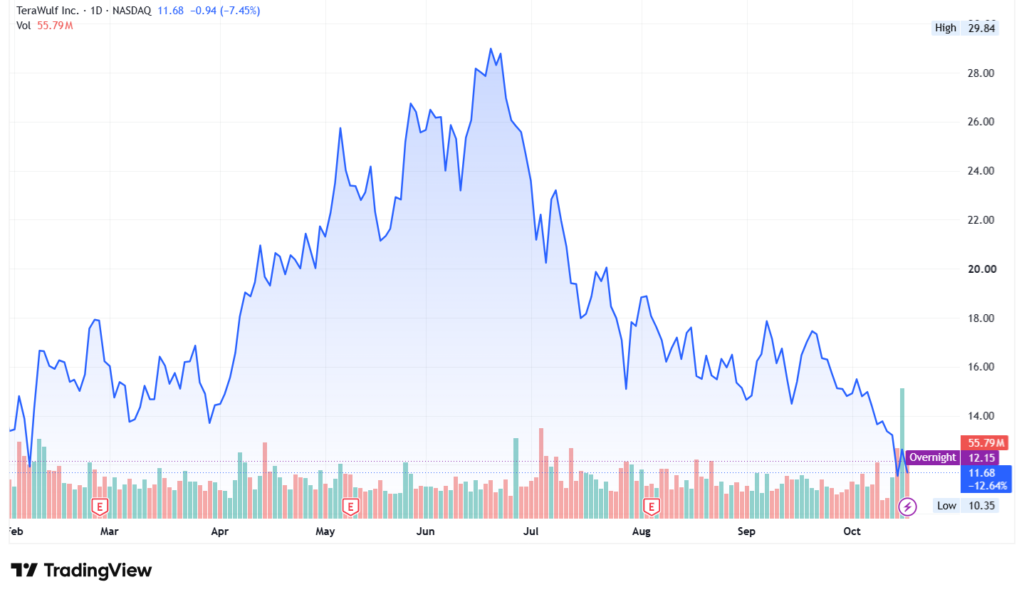
Terawulf WULF stock

TeraWulf (WULF) stock closed down 7.45% at $11.68 on October 16, but rose 3.25% to $12.06 in overnight trading on October 18. The move offers a potential rebound after recent losses, though investors remain focused on the costs and execution risks of the company’s AI data center expansion.

The company’s AI strategy offers significant growth potential, but investors need to look beyond large contract values. TeraWulfย reported second-quarter 2026 revenue of $44.8 million, including $31.9 million from HPC leases. That means HPC leasing accounted for about 71% of total revenue during the quarter.

As the business grows, investors will want to monitor:

  • How much new capacity is operational.
  • Whether projects stay on budget.
  • How quickly contracted revenue turns into cash flow.

Other important factors include financing costs, construction spending, customer commitments, and the risk of raising additional capital. Long-term leases can provide revenue visibility, but they do not remove the costs and execution risks involved in building large data centers.
The company’s energy strategy also deserves close attention. Low-carbon electricity and efficient cooling may help control operating costs and support customer demand. Investors should see if these benefits last as the company grows into new areas. Different power sources and grid conditions may affect this.

TeraWulf’s sustainability disclosures help investors see progress. Still, it’s important to look at the energy mix and efficiency figures along with total energy use, emissions, water use, and community impacts.

TeraWulf stock AI growth strategy

Can TeraWulf Combine AI Growth With Lower-Carbon Infrastructure?

TeraWulf is positioning itself to benefit from rising demand for AI computing. The Anthropic lease provides the company with a strong long-term commitment. Also, access to low-carbon power may help it compete in the energy-intensive industry.

But the opportunity comes with challenges. Building new capacity requires significant investment, and data centers face growing scrutiny over electricity demand, environmental impacts, and local costs.

For WULF shareholders, the key question is whether TeraWulf can achieve its expansion plans. They also want to know if the company can control costs and keep its energy advantages.

Low-carbon power could be a competitive strength, but long-term success will depend on execution, reliable energy supplies, and clear evidence that the company’s growth can be managed responsibly.

Verra Issues First Rice Carbon Credits in India Under New Methodology

Verra has approved the first carbon credits under its methodology for improved rice production, opening a new opportunity to finance farming practices that reduce methane emissions. The credits come from an Indian rice cultivation project developed by Core CarbonX Solutions, which has avoided more than 210,000 tonnes of carbon dioxide equivalent (tCO2e) through improved water and crop management.

The project, called Core Carbon Sustainable Rice Productions 01, is registered under Verra Project 3243. It operates in the Suryapet district of Telangana, a major rice-producing state in southern India.

The milestone comes as carbon markets place greater emphasis on measurable emission reductions and high-quality credits. Rice cultivation offers an opportunity to address methane emissions while helping farmers access additional income from sustainable agricultural practices.

How Rice Farming Can Generate Carbon Credits

Flooded rice fields create conditions that encourage microorganisms to produce methane as they break down organic matter without oxygen. Methane is a potent greenhouse gas that contributes significantly to near-term global warming.

  • The Food and Agriculture Organization (FAO) estimates that flooded rice systems account for around 8% of human-caused methane emissions. Reducing these emissions is therefore an important part of efforts to limit global warming. FAO

How Core CarbonX Helps Farmers Cut Rice Methane Emissions

The Core CarbonX project tackles this problem through alternate wetting and drying (AWD), a water management technique that allows rice fields to dry periodically before farmers irrigate them again.

Under conventional rice cultivation, farmers often maintain standing water throughout much of the growing season. AWD introduces controlled periods of drainage, allowing oxygen to enter the soil and reducing the conditions that support methane-producing microbes.

Core CarbonX Solutions supports participating farmers with water-monitoring tubes, training and technical assistance. The company also shares revenue from carbon credit sales with farmers, providing an additional financial incentive to adopt improved cultivation practices.

The project demonstrates how agricultural emission reductions can create value beyond the farm. Farmers can contribute to climate mitigation while potentially improving water management and earning additional income.

However, the effects on crop yields and other greenhouse gases can vary with local conditions and how farmers implement AWD. Appropriate irrigation schedules and reliable monitoring remain important for achieving environmental benefits without compromising rice production.

What Verraโ€™s VM0051 Methodology Means

The press release highlights that the project uses Verraโ€™s VM0051 Improved Management in Rice Production Systems methodology. Introduced in 2025, the framework establishes requirements for measuring emission reductions from improved water and crop management in flooded rice systems.

The methodology provides a standardized approach to quantifying the difference between emissions under conventional farming practices and emissions after farmers adopt improved techniques. This helps carbon credit buyers assess the reductions associated with a project.

Beyond water management, VM0051 can support practices such as cultivating improved rice varieties and using methanotrophic bacteria, which consume methane. These options can broaden the range of interventions available to project developers.

Verra revised the methodology in July 2026, releasing version 1.1 to align it with updated program requirements and clarify monitoring and quantification procedures. Projects using the earlier version must follow the applicable transition deadlines.

VERRA RICE
Source: Verra

VKU Certification Private Limited served as the validation and verification body for the Core CarbonX project.

The methodology also has potential relevance for aviation-related carbon markets. In April 2026, Verra announced that the International Civil Aviation Organizationโ€™s technical advisory body had included eligible VM0051 credits from projects in qualifying REDD+ countries in the first and second phases of the Carbon Offsetting and Reduction Scheme for International Aviation (CORSIA). Eligibility depends on the project meeting applicable requirements, including host-country authorization.

This could expand the pool of potential buyers for qualifying rice methane credits, although approval of the methodology does not automatically make every project or credit eligible for CORSIA.

Rice Methane Credits and the Carbon Market Opportunity

Agricultural projects remain a relatively small part of the voluntary carbon market despite their potential to reduce emissions across food production systems.

A 2025 assessment by the FAO Investment Centre found that agrifood systems accounted for more than 10% of projects in the voluntary carbon market but generated only around 1% of issued credits. The gap highlights the challenge of scaling projects in a sector where emissions measurement, farmer participation, and implementation can be complex.

Meanwhile, demand for carbon credits is increasingly focused on quality and credible climate benefits. Climate Focus reported that carbon credit issuances fell to their lowest levels in years during the first half of 2026, while retirements remained resilient. The firm reported approximately 98 million credits retired during the period, compared with issuance of just under 100 million credits.

ย  ย  ย  ย  ย Carbon credit demand remained robust, led by retirements of nature-based credits

rice carbon credits

For rice methane projects, this market environment creates an opportunity to attract buyers seeking measurable emission reductions. However, demand will depend on credit quality, pricing, project performance, and the eligibility requirements of different purchasing programs.

Verra lists 13 other projects using VM0051 that are under development or undergoing validation. These projects span countries including India, Brazil, Vietnam, the Philippines, Indonesia, Thailand, Malaysia, Myanmar and Madagascar.

The growing project pipeline suggests that rice methane reduction could become a more established segment of agricultural carbon finance. Yet, projects must demonstrate that their claimed reductions are real, measurable, and supported by reliable monitoring.

For Core CarbonX, the first approved credits provide a starting point for bringing improved rice cultivation practices into carbon markets. The broader opportunity will depend on scaling farmer participation, maintaining robust verification, and ensuring that carbon revenue delivers meaningful benefits to farming communities.

JPMorganChase Extends Climate Targets to 2035 and Expands Green Finance Rules

JPMorgan Chase is changing how it measures climate progress and green financing as global energy demand rises. The U.S. banking giant has updated its emissions targets, expanded the types of projects that count toward its green finance goal, and launched a new center focused on energy and the environment.

The changes reflect the bankโ€™s view that cutting emissions must go hand in hand with reliable and affordable energy. Its updated approach includes financing for nuclear power, electricity grids and other low-carbon energy activities.

The bank also extended key climate targets from 2030 to 2035. It says the targets will help track progress across its lending portfolio, but they will not restrict its financing decisions.

The changes were announced on October 14, alongside the release of JPMorganChaseโ€™s 2025 Sustainability Report. They mark a broader approach to climate finance as artificial intelligence, manufacturing and electrification increase demand for power.

Heather Zichal, Head of the Center for Energy and the Environment and Global Head of Sustainability, said:

โ€œMeeting energy demand while balancing affordability, security, reliability, and sustainability, what we call the โ€˜Four Forces,โ€™ is one of the defining economic opportunities of our era.โ€

Oil, Power and Auto Sectors Get New 2035 Emissions-Intensity Targets

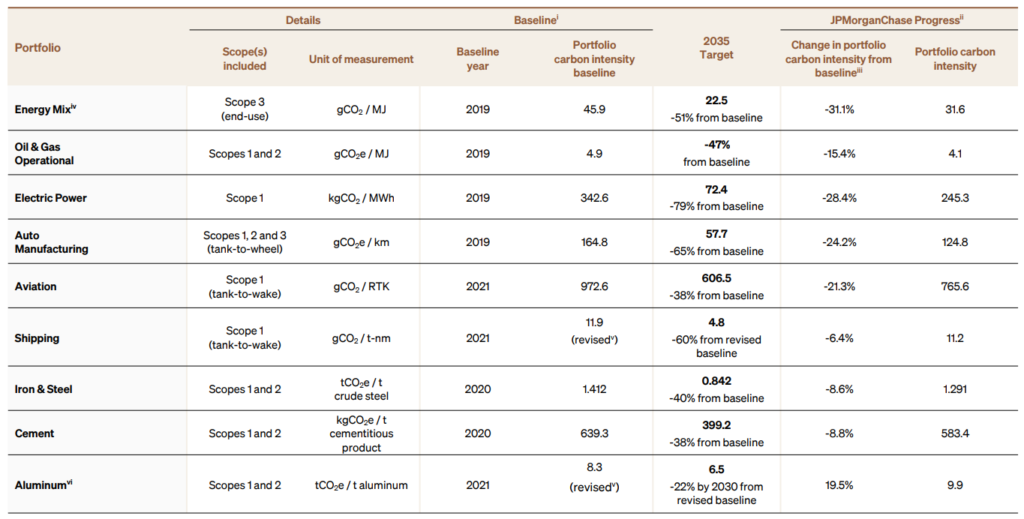
JPMorganChase first set portfolio-level emissions targets in 2021. These targets measure the carbon intensity linked to its financing in selected industries.

Carbon intensity measures emissions against a unit of business activity or output. Tracking it helps the bank assess how emissions linked to its lending change over time.

The bank has now updated its targets to align with the International Energy Agencyโ€™s 2025 Net Zero Emissions by 2050 scenario. The updated targets use 2035 as their target year rather than 2030. Three major changes stand out:

  • Oil and gas: The target is now a 47% reduction in carbon intensity by 2035, compared with the previous 45% reduction target by 2030.
  • Electric power: The target rises to a 79% reduction by 2035, from the previous 69% target by 2030.
  • Auto manufacturing: The target increases to a 65% reduction by 2035, compared with the previous 48% target by 2030.

These percentages refer to carbon intensity, not total emissions. They also do not mean the bank has already achieved these reductions. They are targets for measuring changes across its financing portfolio.

JPMorgan new climate targets 2035
Source: JPMorganChase

The bank also stresses that the IEA scenario is one possible path to reaching net zero, not a prediction of what will happen. JPMorganChase says its targets may change as technology, markets and available information develop.

Green Financing Now Includes Nuclear Power and Electricity Grids

JPMorganChase has also widened the types of activities that count toward the green objective of its $2.5 trillion Sustainable Development Target. The bank launched this 10-year goal in 2021. It aims to finance or help arrange more than $2.5 trillion for sustainable development by the end of 2030, including a $1 trillion green finance objective.

Under the new rules, eligible activities include:

  • Nuclear energy,
  • Electricity networks,
  • Grid upgrades,
  • Electric vehicle charging infrastructure, and
  • Zero- and low-carbon power generation at companies using various energy sources.

The change reflects the bankโ€™s view that a cleaner energy system needs more than renewable power plants. Electricity grids need to link new energy sources to users. They must also provide reliable power to meet rising demand.

However, the expanded definition has an important effect on the reported figures. JPMorganChase applied the new eligibility rules to earlier years, too, allowing it to measure past financing under the updated system.

As a result, a higher green finance total does not necessarily mean the bank provided the same amount in new funding during that period. Some of the increase reflects activities that now qualify under the broader rules.

Bank Reports $520 Billion in Green Finance

JPMorganChase reported that it had financed or helped arrange $1.2 trillion toward its $2.5 trillion Sustainable Development Target by the end of 2025. Of that total, $520 billion counted toward its green finance objective.

  • The bank reported $217 billion in sustainable development financing during 2025, including $96 billion under the green objective.

The expanded eligibility rules contributed $145 billion to the reported green finance total. This is an important point when looking at the bankโ€™s progress. The new figure includes financing that meets the new rules, not just new funding.
The green objective supports activities such as low-carbon energy, clean technology and projects that improve climate resilience. The bank says it has financed or helped arrange more than $500 billion in low-carbon energy since 2021. Its tax-focused investment team has also helped finance one in every four gigawatts of U.S. renewable energy and storage capacity, according to the bank.

These figures show the scale of JPMorganChaseโ€™s financing activity. However, money counted toward a green finance target is not the same as a measured reduction in greenhouse gas emissions. The actual climate impact depends on the projects financed and the results they deliver.

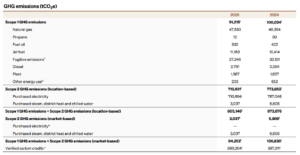
JPMorgan GHG emissions 2025
Sources: JPMorganChase

New Center Will Focus on Energy and Climate Challenges

Alongside the target changes, JPMorganChase launched its Center for Energy and the Environment (CE&E). The new center brings together the bankโ€™s Center for Carbon Transition and its Corporate Sustainability functions. It aims to combine energy and climate expertise with policy knowledge and financial services.

The bank says this approach will help it identify barriers that money alone cannot solve. These include slow permit approvals, delays in connecting projects to electricity grids, worker shortages, supply chain problems, and uncertainty about future rules.

The center plans to work across businesses, policymakers and investors to help address these challenges. The bank has also placed greater emphasis on what it calls four forces: affordability, security, reliability and sustainability. It argues that energy investment must consider all four to support lasting progress.

This wider focus comes as power demand rises from data centers, artificial intelligence, manufacturing and electrification. JPMorganChase says it facilitates nearly $100 billion a year to help add new energy supply from different sources.

Emissions Targets Will Not Limit Lending

A major part of the updated strategy is the bankโ€™s view that financed-emissions figures cannot tell the whole story. Financed emissions are greenhouse gas emissions linked to the activities of companies that a bank lends to or supports. These figures can track changes in a portfolio. However, the bank notes that gaps in data and different measurement methods can limit their usefulness for decisions on individual loans.

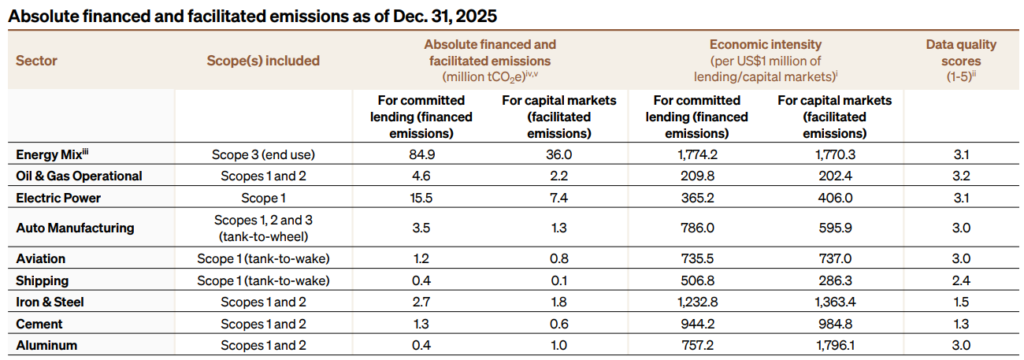
Absolute financed and facilitated emissions
Sources: JPMorganChase

JPMorganChase will continue using its climate targets to monitor trends and guide discussions with clients. However, it says the targets are not designed to restrict financing. This means the bank may continue to finance companies across different energy sectors while tracking how its portfolioโ€™s carbon intensity changes.

The approach also reflects the bankโ€™s focus on energy security and affordability. Nuclear power and grid upgrades might qualify for green finance rules. The bank sees them as key to a reliable, lower-carbon energy system.

The wider definition does not mean every activity at a company that uses fossil fuels automatically qualifies as green. Eligible activities must still meet the bankโ€™s own criteria.

Will Broader Green Finance Deliver Measurable Climate Gains?

JPMorgan Chaseโ€™s new strategy focuses more on the capital it directs to energy projects. It also tracks emissions intensity closely.

The changes also make its green finance figures broader. This can help capture more low-carbon infrastructure types. However, readers need to tell the difference between new financing and amounts that qualify due to rule changes.

The bankโ€™s approach also leaves open questions about how quickly its clients will cut emissions and how much the financing will contribute to real-world climate progress. Its updated targets provide a way to track portfolio trends through 2035, while the new center aims to address practical barriers to energy investment.

For investors and climate-market observers, the key measures to watch will be future financing totals, progress against the revised emissions-intensity targets, and evidence of actual emissions reductions. These will help show whether the broader strategy leads to changes beyond the way the bank reports its activities.

Frontier Signs $11.7M Carbon Removal Deal With 44.01โ€™s Rock-Mineralization Technology

44.01, a carbon removal company founded in Oman and headquartered in London, has signed an $11.7 million carbon removal purchase agreement with Frontier to permanently store carbon dioxide (COโ‚‚) underground by converting it into rock. The deal will support the companyโ€™s efforts to move its technology from short-term field trials to continuous commercial operations.

Under the agreement, Frontier buyers will purchase the removal of 20,932 tonnes of COโ‚‚ between 2028 and 2031. The project marks Frontierโ€™s first offtake agreement for in-situ mineralization (ISM), a process that accelerates natural reactions between dissolved COโ‚‚ and underground rocks to lock carbon away for geological timescales.

How 44.01 Converts COโ‚‚ Into Rock

44.01 uses peridotite, a magnesium-rich rock that reacts with dissolved carbon dioxide to form stable carbonate minerals. The company has demonstrated its approach in Oman and the United Arab Emirates (UAE), where extensive peridotite formations provide potential sites for underground mineralization.

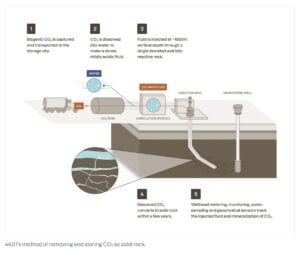
The process involves five main steps:

  • Capture: The project separates biogenic COโ‚‚ during biogas upgrading at a wastewater treatment plant and transports it to the storage site.
  • Dissolution: The company mixes the captured COโ‚‚ with water to create a mildly acidic solution.
  • Injection: A deviated well, drilled to approximately 1,000 meters underground, distributes the carbonated water through naturally fractured peridotite.
  • Mineralization: The dissolved COโ‚‚ reacts with magnesium-rich minerals and forms solid carbonates. 44.01 says this process can take one to three years.
  • Monitoring: Mass-flow meters, fluid samples, and geophysical sensors help track the injected COโ‚‚, verify mineralization and monitor underground fluid movement and potential induced seismicity.

Once the COโ‚‚ becomes solid carbonate, the risk of reversal becomes extremely low, allowing the carbon to remain stored over geological timescales.

Why In-Situ Mineralization Could Expand Carbon Storage

Permanent storage remains a major challenge for carbon removal projects. Technologies such as direct air capture and bioenergy with carbon capture and storage can generate concentrated COโ‚‚ streams, but developers still need suitable locations and infrastructure to store the gas.

Conventional geological storage typically involves compressing COโ‚‚ and injecting it into deep sedimentary formations. Although this approach works for large projects, it can be expensive for smaller facilities that produce limited volumes of COโ‚‚. Pipelines, transportation infrastructure, and lengthy permitting processes can make these projects difficult to develop.

44.01โ€™s technology could help address this problem by allowing developers to store COโ‚‚ in reactive rock formations closer to where emissions originate.

For example, industrial sources near the companyโ€™s existing UAE site are within 50 kilometers of suitable peridotite formations but more than 300 kilometers from viable conventional storage in the Gulf. Similar opportunities may exist in Japan, Oman, Finland, inland Norway, and along the US Pacific coast.

The potential benefits include:

  • Lower transportation needs: Projects could avoid expensive pipelines or shipping when suitable rock formations are located near COโ‚‚ sources.
  • Permanent storage: Mineralization converts dissolved COโ‚‚ into stable solid minerals.
  • Access for smaller facilities: Wastewater treatment plants, biogas facilities and smaller industrial sites could gain additional storage options.
  • Broader industrial applications: The technology could store concentrated COโ‚‚ captured from cement, steel and other hard-to-abate industries.

Frontier estimates that suitable reactive rock formations could support more than 5 billion tonnes of COโ‚‚ storage annually worldwide. It also identifies more than 50 million tonnes of industrial emissions in the UAE that could potentially be captured and stored through in-situ mineralization. These figures represent estimated potential, not existing operational capacity.

carbon removal
Source: McKinsey

Project Targets Commercial-Scale Operations

44.01 has conducted five field pilots and short-duration COโ‚‚ injection programs since 2023. The Frontier agreement will help the company test whether it can maintain target injection rates over multiple years and determine how much water continuous operations require.

The company has designed its deviated wells to expose injected fluids to a larger volume of reactive rock. Drawing on drilling techniques used in enhanced geothermal energy and the oil and gas industries, this approach could improve injection rates and reduce costs.

44.01 also says that dissolving COโ‚‚ in water before injection adds a containment layer. The company monitors underground fluid movement and relies on geological barriers to provide additional safeguards. TรœV SรœD and the XPRIZE Carbon Removal board have conducted third-party safety reviews of its approach.

Talal Hasan, founder and CEO of 44.01, said the agreement would help move in-situ mineralization toward commercialization. The company plans to improve operating performance, reduce costs, and make permanent storage accessible to more customers.

Hannah Bebbington Valori, Frontierโ€™s head, said the technology could expand the range of locations where permanent COโ‚‚ storage becomes economically practical.

CCS: Total Operational Capacity and Growth

As of 2024, global CCS facilities in operation had a combined capture capacity of just over 50 million tonnes of COโ‚‚ per year. This shows steady growth, up from about 40 Mt a few years ago. However, it still accounts for just a small part of the over 40 billion tonnes of COโ‚‚ emitted worldwide each year.

CCS

Carbon Removal Market Sees Rising Demand

The deal comes as companies increase their purchases of carbon dioxide removal (CDR) to address residual emissions that remain after direct emission reductions.

Carbon capture and storage (CCS) and carbon removal serve related but different purposes. CCS generally prevents COโ‚‚ from industrial sources from entering the atmosphere, while carbon removal takes COโ‚‚ already in the atmosphere and stores it durably. In-situ mineralization can support both applications, depending on the source of the captured carbon.

Recent market activity points to stronger demand for durable carbon removal:

  • Corporate demand is growing: Buyers committed to 2.1 million tonnes of carbon removal in Q2 2026, up 136% year over year, across 14 deals.
  • Supply may fall short: McKinsey estimates durable carbon removal demand could reach 100 million tonnes annually by 2030, double the 50 million tonnes of announced supply.
  • Financing supports growth: Advance purchase agreements help early-stage developers fund projects, test technologies and prepare for commercial expansion.

The World Economic Forumโ€™s 2026 analysis, developed with Oliver Wyman and ClimeFi, also highlights limited access to capital, fragmented standards, and unclear accounting rules as barriers to scaling carbon removal technologies.

Frontier Deal Could Open a New Storage Pathway

The agreement allows 44.01 to demonstrate whether in-situ mineralization can operate continuously, store COโ‚‚ permanently, and deliver reliable performance at a commercially viable cost.

If the project succeeds, the technology could expand permanent storage options for industrial facilities and carbon removal developers that cannot economically access conventional geological storage.

However, scaling the technology will depend on the results of multi-year trials, the availability of suitable rock formations, water requirements, and project economics.

For the wider carbon removal market, the deal highlights the importance of financing early-stage technologies that could increase long-term storage capacity. As demand grows, approaches such as in-situ mineralization could help developers build the infrastructure needed to deliver durable carbon removal at a larger scale.

Indonesia Sets New Rules for Farm Carbon Credits and Farmer Benefits

Indonesia has introduced new rules for carbon credit projects in farming. The regulation requires businesses to work with farmer groups and agree on how to share the benefits from these projects. It covers rice farming, livestock and plantations.

The new rule explains how agricultural projects can earn carbon credits, how emissions cuts must be checked, and how farmers should take part. The Indonesian Ministry of Agriculture issued Minister of Agriculture Regulation No. 18 of 2026 on October 6. It was published on October 12 and is set to take effect three months later.

The rules come as Indonesia builds its wider carbon market. Its national carbon exchange had recorded more than 1.6 million tonnes of carbon credits traded by July 2025, with a total transaction value of about US$4.7 million. More than 100 organizations had registered to use the exchange.

The new agricultural rules aim to give farming projects a clearer path into this market while setting conditions for farmer participation and benefit-sharing.

Opening Carbon Trading for Rice, Livestock and Plantations

The new regulation covers three main parts of agriculture: rice farming, livestock and plantations. Projects can earn carbon credits by cutting greenhouse gas emissions or storing more carbon in soil and plants.

Possible activities include changing how rice fields are watered, using lower-emission crop varieties, applying the right amount of fertilizer and improving the handling of crop waste and animal waste.

Other options include improving soil health, planting trees and other long-living crops, restoring damaged farmland and using farming methods that protect the soil. These activities can help reduce emissions or store more carbon. For example, changing how rice fields are watered can lower methane emissions. Better soil management can also help keep carbon in the ground.

Businesses, government agencies and farmer groups may take part in these projects. The rules explain how they can work together to reduce emissions and support Indonesiaโ€™s climate goals.

Businesses Must Agree to Share Benefits With Farmers

One of the most important parts of the regulation is its requirement for businesses to work with farmer groups.

Under Article 4, businesses involved in agricultural carbon trading must work with at least three farmer organizations near the project site. The number and choice of groups must consider factors such as the size of the businessโ€™s land area and its operations.

The business and the farmer groups must sign a written agreement. It must explain what each side will do, how benefits will be shared and how long the agreement will last. Farmers must also give free, prior and informed consent. In simple terms, they must receive clear information and agree to take part without pressure.

The regulation does not set one fixed percentage of carbon revenue for farmers. Instead, the share must consider several factors, including:

  • Cost of technology,
  • Size of the land or business,
  • Amount of emissions reduced, and
  • Number of carbon credits generated.

This means the benefit-sharing arrangement can differ from one project to another.

Farmer groups can also run carbon credit projects themselves through a cooperative or another business. They may also work with outside partners that provide funding, as long as the parties agree on how to share the benefits.

The rules give farmer groups a formal role in carbon projects. They are not simply expected to provide land or help carry out farming activities.Indonesiaโ€™s Agricultural Carbon Credits Guide

Projects Must Prove Their Emissions Cuts

The regulation sets out steps that projects must follow before they can receive carbon credit approval.

Businesses using Indonesiaโ€™s national certification system must first submit a project plan called a Climate Change Mitigation Action Design Document, or DRAM. This document explains what the project will do, how it will reduce emissions and how the results will be measured.

The plan must go through an assessment and independent review. Once the project has carried out its activities, an independent verifier must check the reported results. The business can then apply for a recommendation for an Indonesian Greenhouse Gas Emissions Reduction Certificate, known as SPE GRK.

These steps are designed to make sure that carbon credits are based on real, documented and verified results. Projects using other carbon credit standards may also qualify, subject to the relevant approval process.

Projects must also follow rules on social and environmental protection, public participation and legal compliance.

The regulation also seeks to prevent double counting. This happens when the same emissions reduction is claimed more than once by different parties or programs. Preventing this is important because buyers need to know that a credit represents a real emissions cut or carbon removal that has not already been counted elsewhere.

National Carbon Registry Sets the Path for Tracking Farm Credits

Agricultural carbon projects will use Indonesiaโ€™s national carbon registry, known as the Sistem Registri Unit Karbon, or SRUK. The registry records carbon units and helps track projects and transactions. It is part of the governmentโ€™s wider effort to organize the countryโ€™s carbon market.

Indonesiaโ€™s national carbon registry summary
Source: Sistem Registri Unit Karbon (SRUK)

Project developers must submit the required documents and follow the rules for project review, independent checks and approval. Moreover, projects that want to transfer carbon credits for use by another country or for international purposes may need additional approval from the environment minister. This follows a recommendation from the agriculture minister.

  • Approval to run a project does not automatically allow its credits to be transferred internationally. Projects must meet the separate requirements that apply to those transfers.

The rules also cover projects that combine agriculture with other activities, such as planting trees among crops, making biochar or producing biogas from waste. Any government charges must follow Indonesiaโ€™s rules on non-tax state revenue. The regulation does not set one fee that applies to every project.

Indonesia’s Wider Carbon Market Is Expanding

The new agricultural rules are part of Indonesiaโ€™s wider effort to build a carbon market for both domestic and international trading.

Indonesia launched its national carbon exchange, IDXCarbon, in September 2023. By July 2025, it had recorded more than 1.6 million tonnes traded, worth about US$4.7 million. These figures show that a market is already operating, although they do not represent agricultural credits alone.

The country is also preparing for more international carbon trading under Article 6 of the Paris Agreement. Article 6 allows countries to trade verified emissions reductions under rules designed to prevent the same reduction from being counted twice.

As of October 13, 2026, the UN Environment Programme Copenhagen Climate Centreโ€™s Article 6 database listed four bilateral agreements and 40 Article 6.2 activities for Indonesia. It reported no internationally transferred or received mitigation outcomes yet. This suggests the country has a growing project pipeline, but international transfers remain at an early stage.

Indonesia also has major natural resources that could support its wider carbon market. The country has about 95.5 million hectares of forest and around 3.44 million hectares of mangroves, equal to roughly 20% of the world’s mangrove area. Its FOLU Net Sink 2030 program aims for the forestry and land-use sector to absorb a net 140 million tonnes of COโ‚‚ equivalent by 2030.

Indonesiaโ€™s carbon market potential
Source:

Forestry and land-use projects are different from farm carbon projects, but they show why Indonesia is working to strengthen its rules for carbon trading across several sectors.

In July 2026, Verra announced it would issue at least 20 million tonnes of emissions reductions. This comes from three Indonesian forestry projects under new carbon market rules. This was an expected issuance, not a report that all 20 million tonnes had already been issued.

Will Indonesiaโ€™s New Rules Expand Farm Carbon Investment?

Indonesiaโ€™s new rules create a clearer process for agricultural carbon projects, including credit approval and benefit-sharing with farmers.

Businesses must meet project requirements and agree with farmer groups on how to share benefits. However, farmers are not guaranteed a fixed income, as payments will depend on project results and agreed terms.

The rules add to Indonesiaโ€™s wider carbon market framework under Presidential Regulation No. 110 of 2025. Their impact will depend on how well projects follow the requirements and turn verified emissions cuts into approved carbon credits.