EU Carbon Market Shake-Up: Nearly 100 Million More Free Permits for Industry

The European Union is moving toward a major change in how it gives free carbon permits to industry. The European Parliamentโ€™s environment committee has backed a plan that could provide around 99 million additional free emissions allowances to certain industrial installations from 2026 to 2030.

The proposal aims to help European businesses manage carbon costs and compete with companies in countries with weaker climate rules. But it also raises a key question: how can the EU protect its industries while keeping pressure on them to cut emissions?

The committeeโ€™s position differs from the plan backed by EU member states, which would provide around 121 million allowances. Neither proposal should be treated as final law. The two sides must still agree on the rules.

EU Committee Backs 99 Million Free Allowances

The European Parliamentโ€™s Committee on the Environment, Climate and Food Safety (ENVI) backed changes to the EU Emissions Trading System (EU ETS). The vote was 64 in favor, 11 against, and two abstentions.

The plan covers industrial installations whose free allowances are calculated using heat and fuel benchmarks. These benchmarks apply when a specific product benchmark is not available.

Under the committeeโ€™s approach, around 88 million allowances available for free allocation would be used. It would add another 11 million allowances linked to existing conditions that some installations failed to meet. Together, these would bring the total to about 99 million allowances for the period through 2030.

Each EU ETS allowance permits its holder to emit one metric tonne of carbon dioxide equivalent (COโ‚‚e). Companies that receive more free allowances may need to buy fewer permits to cover their emissions, depending on their actual emissions and allocation.ย  ย 

The proposal does not give every industrial company the same benefit. It concerns installations covered by the relevant heat and fuel benchmarks and remains subject to the final rules.

Why the EU Wants to Ease Carbon Costs for Industry

The EU ETS puts a price on greenhouse gas emissions from power generation, industry, aviation and other covered activities. Companies must surrender enough allowances to match their reported emissions. They can buy allowances at auction or trade them with other market participants.

The system is designed to make pollution more costly and encourage businesses to reduce emissions. However, some industries receive free allowances to limit the risk of carbon leakage. This happens when companies move production to countries with weaker climate rules, potentially shifting emissions rather than reducing them.

Free allocation is based on common benchmarks that reflect the emissions performance of the 10% most efficient installations in each sector. The EU has been tightening its carbon market rules as it pursues deeper emissions cuts.

The new proposal responds to concerns that updated heat and fuel benchmarks could raise costs for some industrial businesses. These rules are especially relevant to sectors that use large amounts of heat or fuel and do not have a specific product benchmark.

The European Commissionโ€™s original July proposal estimated that around 80 million allowances could be used for additional free allocation. Later estimates put the available amount at around 88 million. The committeeโ€™s position adds a further 11 million allowances to that pool.

EU Member States Want an Even Larger Allocation

The European Parliament committee and EU member states have taken different approaches to the available allowances. In September, the Council of the European Union backed a plan to combine around 88 million available allowances with a pool of roughly 33 million allowances linked to existing allocation conditions.

That would bring the total to about 121 million allowances for industry over 2026โ€“2030. Reuters estimated that the Council approach could save affected companies around โ‚ฌ8.25 billion in carbon costs.

The Parliament committee proposes a different split. It would direct about 11 million of the 33 million pool to industry, with one-third going to the Modernisation Fund and another third to the Innovation Fund. These funds support energy-system upgrades and low-carbon technologies.

The disagreement is not only about the number of permits. It is also about how much support should go directly to industrial companies and how much should help finance the wider energy transition.

The Commission has separately estimated that the roughly 88 million available allowances could avoid around โ‚ฌ6 billion in costs for the affected sectors. That estimate relates to the available pool, not the full 121 million allowance option.

The European Parliamentโ€™s legislative tracker still lists the file as awaiting Parliamentโ€™s position at first reading. The committee vote therefore marks progress, but it does not make the proposed allocation rules law.

EU Emissions Are Falling as Climate Rules Tighten

The debate comes as the EU ETS continues to drive emissions reductions. The European Commission reported that verified emissions covered by the system fell by 1.3% in 2025 compared with 2024. Since the system began in 2005, emissions in covered sectors have fallen by about half.
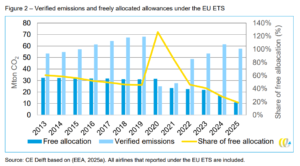
Verified emissions and freely allocated allowances under the EU ETS
Source: CE Delft

The EU ETS remains on track to meet its target of cutting covered emissions by 62% by 2030 compared with 2005 levels. Separately, the EU aims to reduce its net greenhouse gas emissions by at least 55% by 2030 compared with 1990 and reach climate neutrality by 2050.

These targets create a challenge for policymakers. European industries face pressure to lower emissions while managing energy and production costs. Free permits can offer short-term relief, but too much free allocation may weaken the financial incentive to invest in cleaner processes.

The EU has also been changing its wider carbon market rules. The Carbon Border Adjustment Mechanism (CBAM) is designed to address the risk that some carbon-intensive goods could gain a cost advantage by being produced under less stringent climate rules. The EUโ€™s broader ETS framework also phases down free allocation in certain sectors as the new system develops.

How More Free Allowances Could Affect Industrial Investment

If adopted, the extra allowances could lower carbon costs for eligible industrial installations during 2026โ€“2030. The impact on each business would depend on its emissions, allocation level, and the market price of allowances.

The proposal also points to a wider policy choice. Governments want European businesses to stay competitive. They also want companies to invest in energy efficiency, electrification, and lower-carbon production.

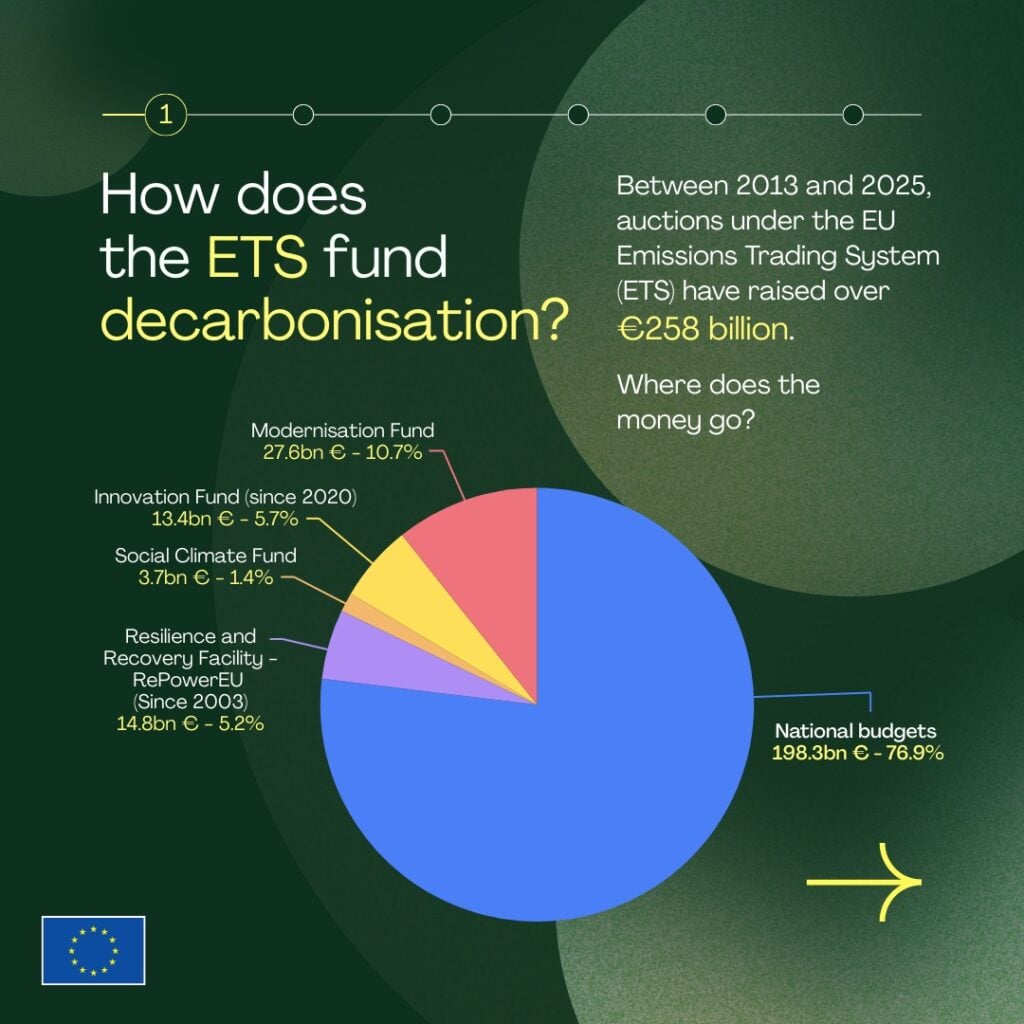
The Innovation Fund and Modernisation Fund are important parts of this effort. EU ETS revenues have helped finance renewable energy, energy efficiency and low-carbon technologies. The European Commission says the system has raised more than โ‚ฌ175 billion since 2013.

EU ETS revenue 2025
Source: EC

For companies, free allowances can reduce near-term costs, but they do not remove the need to plan for tighter climate rules. Businesses that improve efficiency and reduce emissions may be better placed to manage future carbon costs as the emissions cap declines.

The Next Test for Europeโ€™s Carbon Market

The next step is for the European Parliament and the Council to reach an agreement on the final rules. The result will show how many allowances can be freely allocated. It will also decide how to split the rest between industry and climate-related funds.

The decision matters beyond the immediate cost relief. The EU is trying to balance industrial competitiveness with a carbon market that continues to reward emissions cuts. Its official data show that covered emissions are falling, while its 2030 and 2050 targets require further progress.

The final design will determine how the EU shares the cost of that transition. More free permits could ease pressure on eligible industries, but the long-term test will be whether the system continues to support investment and deliver emissions reductions.

Asia-Pacific Carbon Market at a Turning Point: Buyers Rise as Credit Supply Falls

Asia-Pacific is becoming a bigger force in the global carbon market, but not in the way many might expect. The regionโ€™s share of global carbon credit issuance and retirements has fallen since 2021. At the same time, its companies are becoming a major source of new buyers, while governments are shaping how credits are produced, traded and used.

These are key findings from AlliedOffsetsโ€™ APAC Carbon Market Report 2026, published in October. The report examines carbon credit supply, buyer demand, pricing, Article 6 cooperation and aviationโ€™s carbon offsetting system across the region.

The data reveal a market in transition. New demand is emerging, but supply is uneven. Some countries are opening new routes for international carbon trading, while others are building pipelines of credits that could qualify for use under foreign carbon market rules.

APACโ€™s Share of Global Carbon Credit Supply Shrinks

Asia-Pacificโ€™s share of global carbon credit issuance fell from about 50% in 2021 to around 30% in 2025, according to AlliedOffsets. Its share of global credit retirements also declined, from 42% to 33% over the same period.

Retirement happens when a carbon credit is permanently removed from circulation. This often occurs after a company uses it to support a climate claim or meet a requirement. Issuance, by contrast, refers to credits created after a project completes the required process under a carbon crediting program.

The decline in APACโ€™s global share is notable because issuance and retirements grew in regions outside APAC over the same period. This suggests that the regionโ€™s carbon market has not kept pace with growth elsewhere.

However, the report identifies one area of stronger activity: offtake agreements. These contracts allow buyers to purchase credits that a project expects to deliver in the future. APAC accounted for about one-fifth of global offtake volume in 2025 and more than one-third of global volume recorded through October 19, 2026.

APAC carbon credit issuances alliedoffsets
Source: AlliedOffsets

The report cautions that it is too early to know whether this increase marks a lasting trend. Still, offtake activity could help project developers secure revenue and financing before their credits are delivered.

APAC Companies Become a Major Source of New Buyers

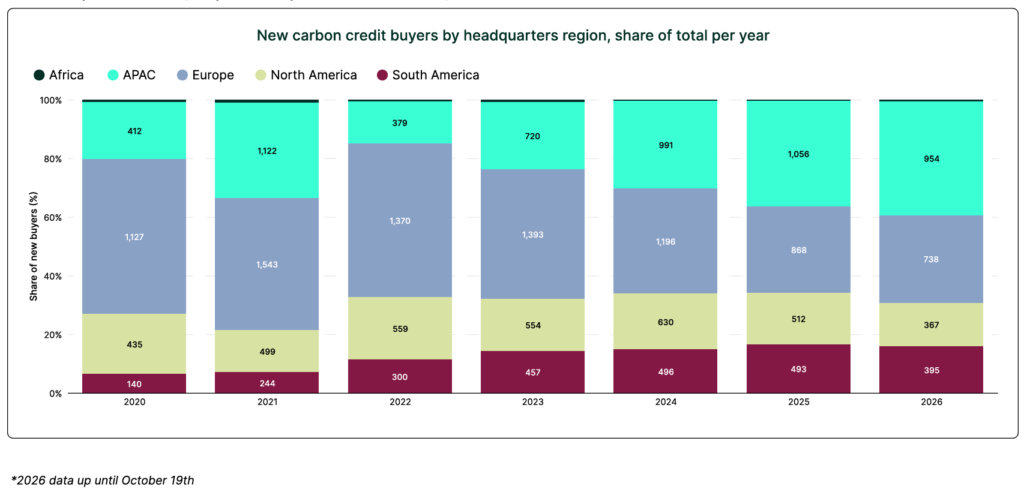
While the regionโ€™s share of credit supply has weakened, demand from APAC-based companies is growing. In 2025, companies headquartered in APAC overtook European companies as the largest source of new carbon credit buyers.

APAC-based businesses accounted for about one-third of new buyers in 2025, up from around one-fifth in 2020. The momentum continued in 2026. AlliedOffsets counted 954 new APAC buyers through October 19, already approaching the record 1,056 recorded for all of 2025.

carbon credit buyers by region alliedoffsets
Source: AlliedOffsets

This shift matters because more buyers can create new demand for projects that deliver credible emissions reductions or remove carbon dioxide from the atmosphere. Buyer numbers alone donโ€™t reveal how much credit each company will buy. They also donโ€™t show if the announced interest will result in completed deals.

The report also finds that APAC nature-based removal supply remains concentrated among a relatively small group of developers. Projects in the region issued about 13.2 million nature-based removal credits in 2025.

Nepalโ€™s Ministry of Forests and Environment accounted for 20% of this total, while Terra Carbon supplied 14%. Permian Global contributed another 12%, and Woodside Burrup accounted for 7%. Smaller developers made up the remaining 38%.

This concentration highlights the role of a few major project developers in regional carbon removal supply.

Carbon Credit Prices Vary by Project Type

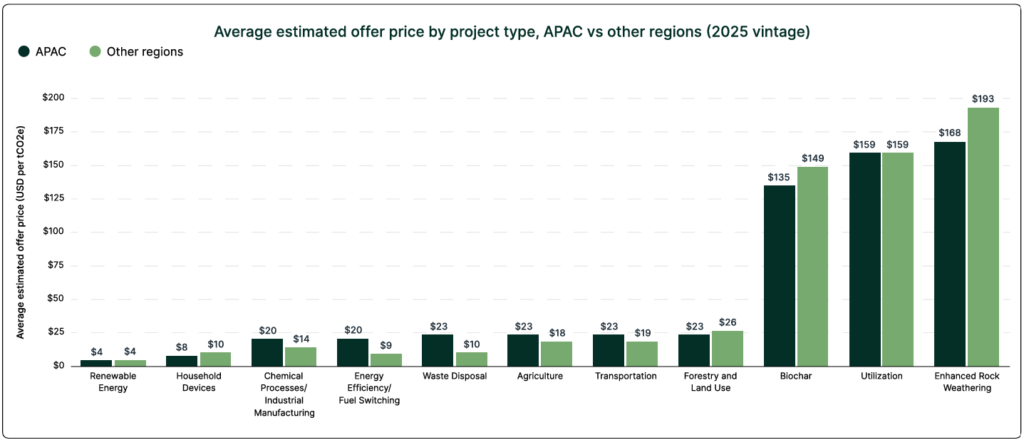
The reportโ€™s pricing data show that APAC credits do not always trade at a discount to those from other regions. Prices depend heavily on the type of project.

AlliedOffsets estimated that in 2025, APAC biochar credits cost an average of $135 per tonne of carbon dioxide equivalent. This is about 10% lower than similar offers from other regions. Enhanced rock weathering credits averaged $168 per tonne, around 13% lower than offers elsewhere.

Average estimated offer price by project type alliedoffsets
Source: AlliedOffsets

Biochar is produced by heating organic material, such as agricultural waste, with little or no oxygen. Enhanced rock weathering uses crushed minerals to speed up natural processes that remove carbon dioxide from the atmosphere.

The pattern was different for some other project categories. APAC energy-efficiency and waste-disposal credits had estimated offer prices more than twice those of comparable credits from other regions.

These figures are estimated offer prices, not confirmed transaction prices. They also apply to specific project types and credit vintages, so they should not be treated as a single market-wide price for APAC credits. The differences show why buyers need to assess credit type, quality, and project details rather than relying only on regional averages.

Article 6 Could Open New Routes for Regional Carbon Trading

International cooperation under Article 6 of the Paris Agreement is another major development in APAC. It helps countries work together to cut emissions. This includes transferring internationally transferred mitigation outcomes, or ITMOs, based on the rules.

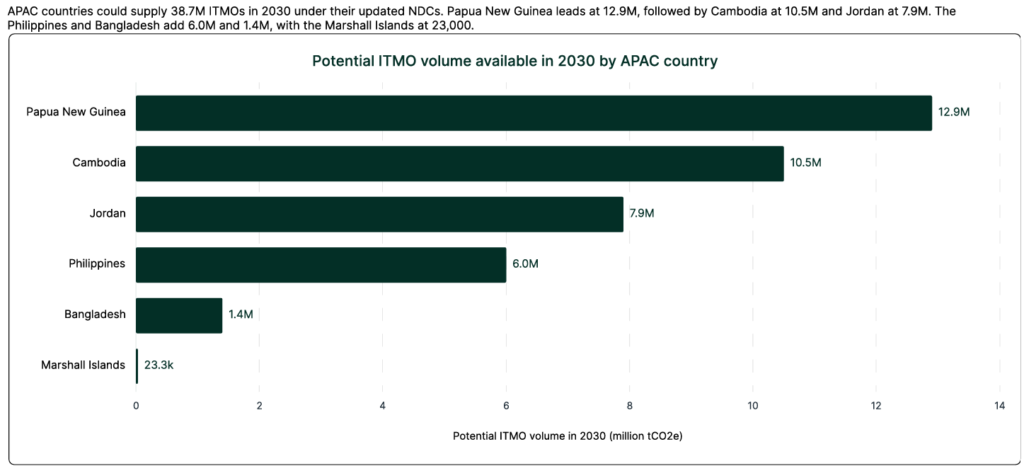
AlliedOffsets estimates that APAC countries could supply 38.7 million ITMOs in 2030 under their updated nationally determined contributions. This is potential supply, not a forecast of credits that will definitely be approved or transferred.

Papua New Guinea accounts for a potential 12.9 million tonnes, followed by Cambodia at 10.5 million and Jordan at 7.9 million. The Philippines might provide 6 million tonnes. Bangladesh contributes 1.4 million, and the Marshall Islands adds about 23,300 tonnes.

ITMO volume available in 2030 by APAC country
Source: AlliedOffsets

The report also tracks projects listed under Singaporeโ€™s eligible carbon credit arrangements. These published lists could provide 27.2 million credits from APAC projects with 2021โ€“2030 vintages.

Mongolian grassland and agricultural land projects account for about 19 million, or almost 70% of the total. Philippine REDD+ projects generate about 6 million credits. Smaller amounts come from cookstoves, electric vehicle charging, reforestation, and rice methane projects.

Being listed does not mean all these credits have already been issued or transferred. Actual use depends on project delivery and the applicable rules.

Meanwhile, the Joint Crediting Mechanism (JCM), which supports cooperation between Japan and partner countries, saw a record 17 APAC projects issue credits in 2025. Yet annual issuance has generally remained at or below 100,000 credits, apart from a Cambodian project that issued about 600,000 in 2023.

Indonesiaโ€™s Carbon Credit Supply Rebounds as Retirements Slow

Indonesia provides another example of the gap between credit supply and demand. Following the reopening of international carbon trading under Presidential Regulation 110/2025, issuance remained close to zero for three quarters before rising sharply in the third quarter of 2026.

  • AlliedOffsets recorded 10.9 million credits issued in that quarter, almost all from the Katingan project.

Yet, retirements have not increased at the same pace. Indonesian credit retirements fell from 5 million tonnes in the first quarter of 2025 to less than 1 million tonnes per quarter during 2026.

This difference matters. New issuance expands the amount of credit available, but it does not guarantee that buyers will purchase and retire those credits. Demand will depend on factors such as eligibility, price, quality, and the rules governing how credits can be used.

For Indonesia, the next challenge is therefore not just to restore supply, but to attract buyers for the credits coming back into the market.

Aviation Rules Add Another Source of Demand

The aviation sector is also influencing APACโ€™s carbon market through the Carbon Offsetting and Reduction Scheme for International Aviation, known as CORSIA. The scheme asks covered airlines to manage certain emissions. They can use approved carbon credits as one of the eligible measures.

AlliedOffsets reports that APAC airlines cancelled just over 1 million credits for CORSIAโ€™s first compliance period. Singapore Airlines accounted for 494,196 credits, while Japan Airlines cancelled 350,200. Together, the two airlines represented about 84% of the APAC airline total recorded in the report.

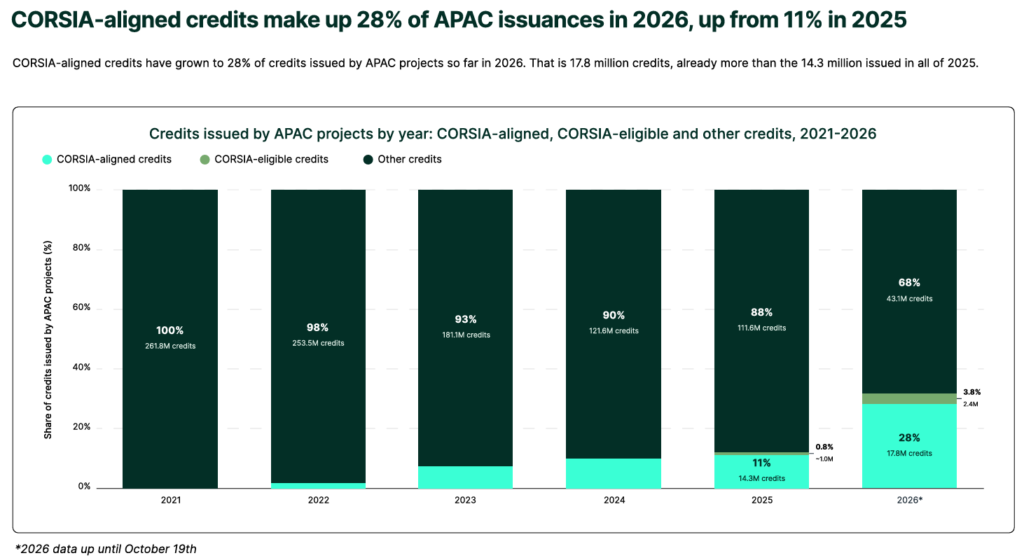
The supply of CORSIA-aligned credits from APAC projects is also growing. These credits accounted for 28% of the regionโ€™s issuance through October 19, 2026, equivalent to 17.8 million credits. In 2025, they represented 11% of issuance, or 14.3 million credits for the full year.

The 2026 figure is already higher than the 2025 total, although the 2026 reporting period is not yet complete. CORSIA eligibility and alignment also do not mean every credit can automatically be used by every airline; applicable program and compliance rules still matter.

CORSIA-aligned credits make up 28% of APAC issuances in 2026
Source: AlliedOffsets

Can APAC Turn Rising Buyer Interest Into Lasting Demand?

AlliedOffsetsโ€™ findings show a shifting APAC carbon market. Although the regionโ€™s share of global issuance and retirements has fallen, new buyers, offtake deals, Article 6 cooperation, and aviation demand are creating opportunities.

Government policy will shape the next phase. Singaporeโ€™s eligible credit lists could direct demand toward selected projects, while Indonesiaโ€™s reopening of international trading has released new supply. Article 6 growth will depend on countries establishing systems to authorize, track, and transfer credits.

The key question is whether rising buyer interest will lead to sustained purchases and retirements. Developers must deliver credible, eligible credits, while buyers need to assess quality and actual delivery. How well APAC connects demand with reliable supply will determine its future role in global carbon markets.

Article 6 Carbon Market Deals Rise 14% as Countries Build Global Trading Network

International carbon market cooperation is gaining ground as more countries sign agreements to trade carbon credits under the Paris Agreement. However, a new report highlights a big challenge: turning agreements into verified emissions reductions. Countries need these reductions to reach their climate goals.

The 2026 Article 6 Implementation Status Report, released by the Paris Agreement Article 6 Implementation Partnership (A6IP), found that bilateral carbon market arrangements rose 14% in one year, reaching 113 by July 2026. These arrangements allow countries to work together on projects that reduce or remove greenhouse gas emissions.

The report also found that countries are making progress on approval rules, carbon registries, and emissions tracking. Yet, many governments still lack the systems needed to fully carry out international carbon trading.

For carbon project developers and investors, the findings point to a growing market opportunity. More countries are building the rules for cross-border carbon deals, but the pace of actual credit transfers will depend on how quickly they can put those systems into practice.

Article 6 Agreements Reach 113 as Global Cooperation Expands

The report recorded 113 bilateral arrangements in 2026, up from 99 in 2025. Of these:

  • 61 were memorandums of understanding (MoUs),
  • 44 were bilateral agreements, and
  • 8 fell into other categories, such as declarations or statements of intent.

These arrangements provide a starting point for countries to cooperate on emissions-cutting projects and the transfer of carbon credits. However, an MoU or other arrangement does not automatically authorize projects or allow credits to be transferred.

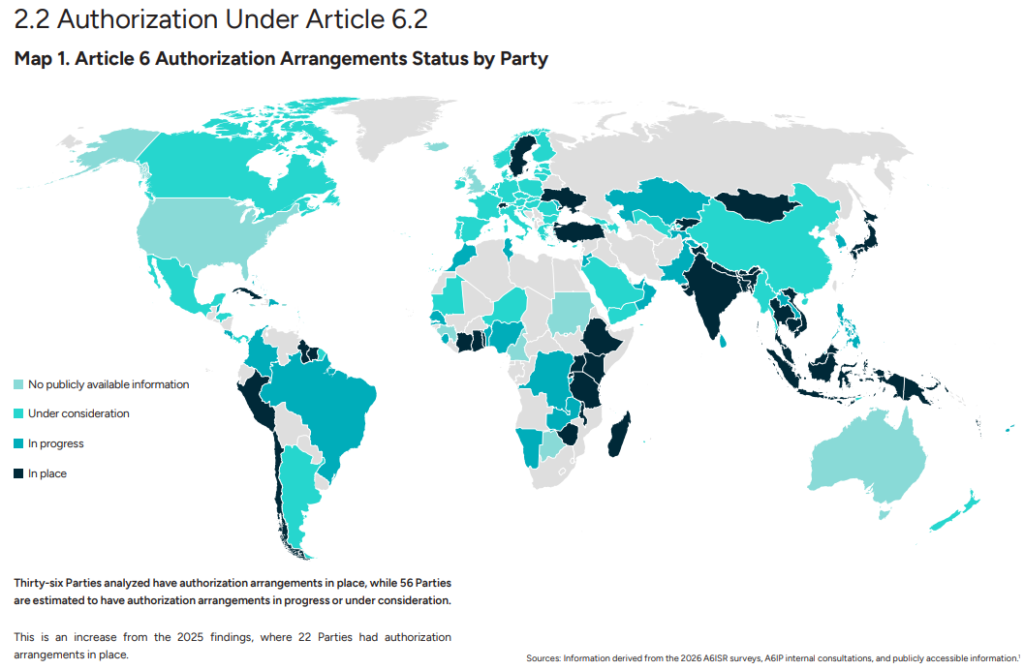
Article 6 Authorization Arrangements Status
Source: A6IP

The report identified 68 countries taking part in bilateral cooperation: 58 host countries and 10 countries seeking to acquire emissions reductions.
Japan remained the leading acquiring country, with 32 agreements. Singapore followed with 29, up from 24 in 2025. Switzerland increased its agreements from 17 to 20, while South Korea rose from 11 to 14.

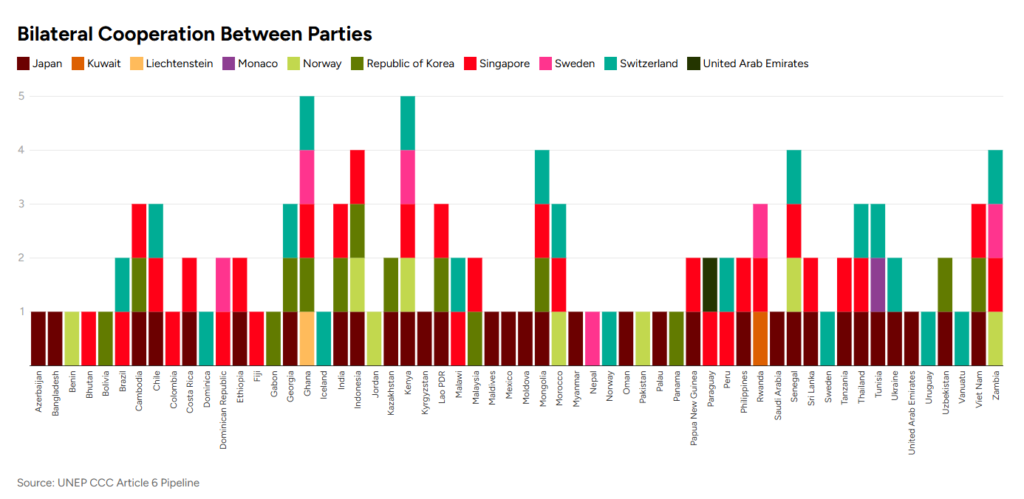
Among host countries, Ghana and Kenya had the highest engagement, each working with five acquiring countries. Indonesia, Mongolia, Senegal, and Zambia followed, each with four partners.

Acquiring Parties and Number of Partner Host Parties Agreements
Source: A6IP

These figures show that international carbon cooperation is spreading across regions. They also highlight the growing role of Asian countries in building cross-border carbon markets.

More Countries Are Preparing to Authorize Carbon Credits

Bilateral agreements are only one part of the process. Countries also need rules for deciding which projects can generate credits for international transfer.

Under Article 6.2 of the Paris Agreement, countries can cooperate by transferring internationally transferred mitigation outcomes, or ITMOs. These transfers need government approval and clear records. This stops the same emissions reduction from counting for more than one country’s climate goal.

The A6IP report found that 36 countries had authorization arrangements in place, compared with 22 in the 2025 report. Another 56 were developing or considering these arrangements.

Article 6 Bilateral Cooperation Between Parties
Source: A6IP

Tracking systems are also advancing. Sixteen countries had systems in place to track ITMOs, while many others were still developing or considering them.

However, only 15 of the 106 countries analyzed had both authorization and tracking arrangements in place. Just 23 had submitted initial reports to the United Nations Framework Convention on Climate Change (UNFCCC).

This gap matters. Countries must know who can approve credit, how to track it, and how to report transfers. This knowledge is key for confident international trading.

Actual Carbon Transfers Remain Small

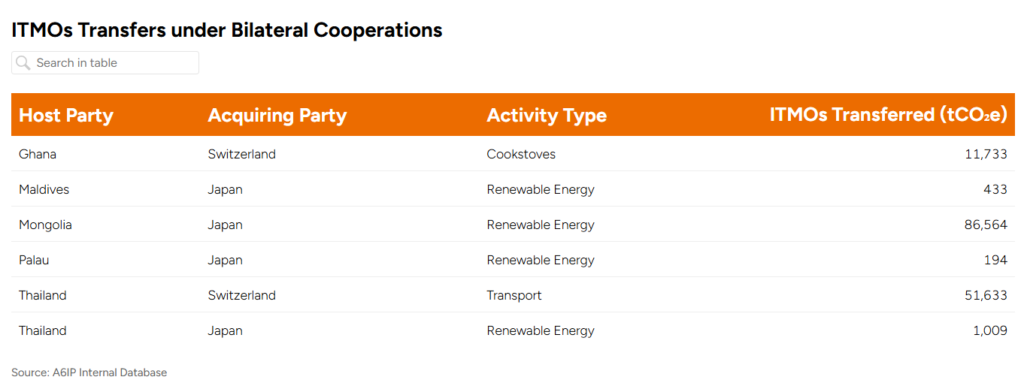
The report’s figures show why the growth in agreements should not be mistaken for a mature trading market. By July 2026, countries had transferred 151,566 tonnes of carbon dioxide equivalent (tCOโ‚‚e) in ITMOs under bilateral cooperation, according to the report.

ITMOs Transfers under Bilateral Cooperations
Source: A6IP

This is a small volume compared with the number of agreements and projects being developed. It shows that many countries are still building the systems needed to move from policy commitments to completed transactions.

The report also tracked progress under Article 6.4, which created the Paris Agreement Crediting Mechanism (PACM), a centralized United Nations system for issuing carbon credits.

By the report’s cutoff, host countries had approved 415 activities for transition from the earlier Clean Development Mechanism. Two transitioned programs of activities had generated about 1.11 million Article 6.4 emission reductions (A6.4ERs).

These developments show that different parts of the Paris Agreement carbon market are progressing at different speeds. The next challenge is to convert project pipelines and approvals into credits. These credits must follow the rules and be usable for their intended purposes.

Singapore and Southeast Asia Build New Opportunities

Recent developments in Southeast Asia offer a clear example of how Article 6 cooperation is moving forward.

Singapore and Laos signed an implementation agreement in September 2026 and agreed on 58 eligible carbon credit methodologies. The list covers areas such as forestry, agriculture, methane reduction, biochar, and renewable energy.

The agreement gives project developers a clearer starting point for preparing eligible projects in Laos. However, the 58 methodologies do not represent 58 approved projects. Individual projects must still meet the countries’ requirements before credits can be authorized for international transfer.

Singapore’s network of 29 bilateral arrangements also makes it one of the most active acquiring countries in the report. Its agreements aim to provide access to eligible international carbon credits as the country works toward its climate targets.

Indonesia is another important market to watch. Its government is developing the systems needed to participate in Article 6.2 cooperation, including preparation of its initial report. The Philippines is still working on its national carbon market framework. It is also assigning the relevant authorities, as noted in the A6IP report.

These examples show that countries are at different stages. Some are already transferring credits, while others are building national rules, registries, and project approval processes.

Carbon Project Developers Still Face Readiness Gaps

The report highlights a growing need for technical support as countries move toward implementation.

Governments need clear laws, trained officials, carbon registries, and systems to measure, report, and verify emissions reductions. They also need to decide which project types are eligible and how to protect their own climate targets when credits are transferred abroad.
For project developers, these rules affect how quickly projects can move from planning to approval and credit issuance. Unclear procedures can increase costs and delay investment.

The report identified 38 support programs focused on policies and frameworks, 34 focused on project development and methods, and 16 focused on registries and infrastructure. Another 54 programs covered knowledge-sharing and other forms of support.

These efforts are important because signing an agreement is only the first step. Countries must also show that projects deliver real emissions cuts or removals, avoid double counting, and meet the reporting requirements of the Paris Agreement.

For buyers and investors, the main opportunity is a growing pipeline of potential projects. The main risk is that delays in national systems may slow the supply of credits that are ready for transfer.

Can Article 6 Turn More Agreements Into Verified Carbon Credits?

The 2026 report points to clear progress in international carbon market cooperation. Bilateral arrangements are growing, more countries are preparing authorization systems, and new projects are moving through the Paris Agreement’s crediting mechanisms.

However, the gap between agreements and actual transfers remains wide. Countries still need stronger tracking, reporting, and approval systems to support a market that buyers and governments can trust.

For Asia, the growth of Singapore’s network and ongoing work in countries such as Laos, Indonesia, and the Philippines show how Article 6 could support investment in emissions-cutting projects.

The next stage will be measured not by the number of agreements signed, but by how many projects deliver verified emissions reductions and how effectively countries authorize, track, and transfer those results.

Terratonโ€™s First Biochar Credits Boost Carbon Removal Expansion Across Africa

Agricultural waste-to-biochar developer Terraton has received its first carbon removal credits from Isometric for its EcoFix Kenya facility, marking a milestone in its plans to expand biochar production across emerging markets. The company has also secured purchase agreements covering up to 97,240 tonnes of carbon removal and $1.5 million in debt financing from HSBC Ventures to develop additional facilities.

The first issuance provides independent verification of carbon removed and stored through the Kenyan project. Terraton aims to replicate its standardized facility model across agricultural supply chains, turning crop residues into biochar while creating a new revenue stream for agribusiness operators.

Its latest agreements include purchases, reserved volumes and marketing rights involving Climeworks Solutions, Climate Impact Partners, Carbonfuture, CUR8 and nonprofit climate fund Terraset. These arrangements provide potential routes to market as the company develops more production capacity.

Terraton Turns Nut Waste Into Carbon Removal Credits

Terraton made its final investment decision on EcoFix Kenya in August 2025 and began producing biochar in May 2026. Isometric issued the facilityโ€™s first credits in October, completing the process in roughly 14 months from the investment decision.

Based in Nanyuki, Kenya, EcoFix processes croton nut husks collected through existing agricultural operations. The biochar facility uses this waste stream without requiring major changes to the companyโ€™s core business.

The project converts the husks into biochar through thermochemical carbonization, a process that heats biomass under controlled conditions. The resulting material stores carbon in a stable form and can improve agricultural soils when used in compost.

  • Biochar can also help raise soil pH, making it relevant to farming regions affected by soil acidification. Its agricultural applications create a potential dual benefit: durable carbon removal and improved soil conditions.

Terraton designed and financed the facility, installed its equipment and sensors, and supplied its smart facility management software. The software sends production data to Offstreamโ€™s digital monitoring, reporting and verification (dMRV) platform, which performs accounting and quality checks before submitting production records to Isometric.

David Armstrong, Partnerships Manager at Isometric, said:

โ€œThis is a major milestone for the Terraton and EcoFix Kenya teams: their first certificates backed by independent verification. Itโ€™s a testament to the work that goes into developing a high-quality carbon removal project, and marks the start of regular issuances. Weโ€™re looking forward to working with Terraton on their second project, Tupande.โ€

Biochar Carbon Removal Market Attracts More Buyers

Terratonโ€™s first issuance comes as companies increase purchases of durable carbon removal credits. Biochar has established itself as a major pathway because producers can convert available biomass into carbon-storing material using commercially deployable technology.

According to CDR.fyi. The market has recorded 7.4 million tonnes of contracted removals and 1.3 million tonnes delivered to date.

Key market figures include:

  • 7.4 million tonnes: Total biochar removals contracted.
  • 1.3 million tonnes: Biochar removals delivered to date.
  • More than 3 million tonnes: Biochar removals contracted in 2026 as of the reportโ€™s publication.
  • 80%: Approximate share of durable carbon removal deliveries attributed to biochar.
  • Five of the top 10 suppliers: Based in the Global South, highlighting the role of emerging markets in expanding production.

Biochar ranks second in contracted volume behind bioenergy with carbon capture and storage (BECCS), which has 31 million tonnes contracted. This growth creates opportunities for Terraton to expand its facilities and supply verified carbon removal credits.

BIOCHAR CARBON REMOVAL

More recent market activity points to continued demand for carbon removal.

  • ClimeFi reported that corporate buyers committed to 2.1 million tonnes of carbon removal across all pathways in the second quarter of 2026, up 136% year over year.
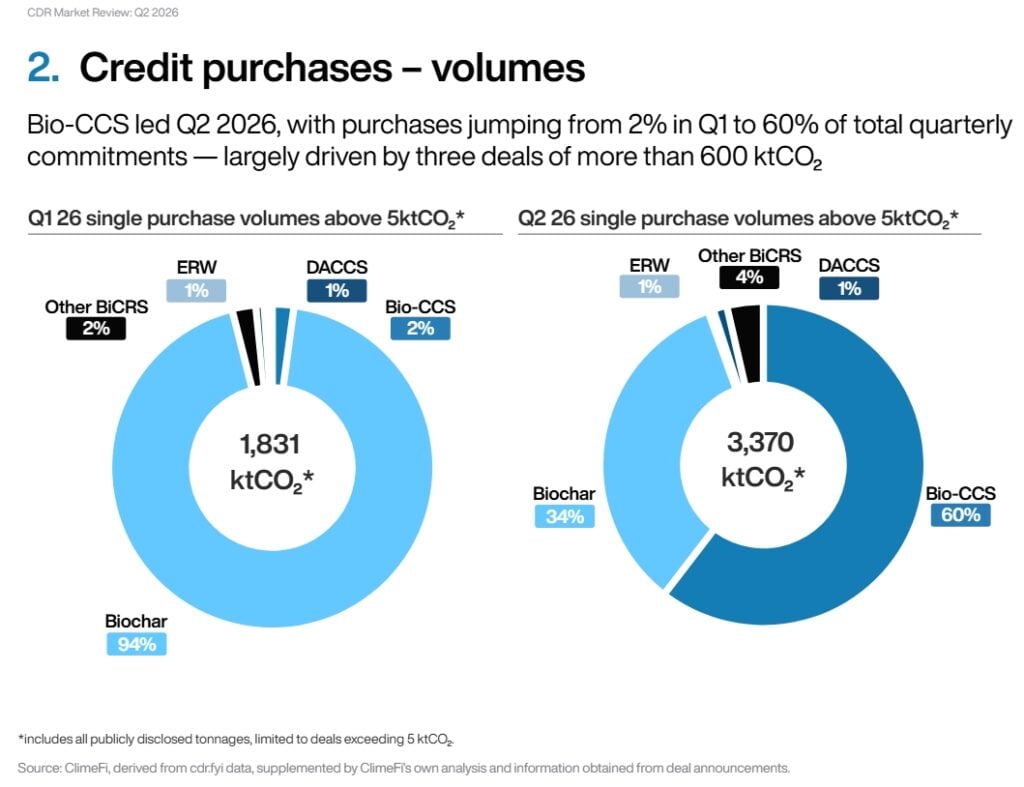
  • Biochar remains a major pathway for durable carbon removal, although other technologies are gaining ground. ClimeFiโ€™s Q1 2026 review found that biochar accounted for approximately 94% of new carbon removal purchase volumes that quarter, supported by three large deals totaling 1.505 million tonnes.

However, biochar no longer led all pathways by purchase volume in Q2 2026 as the market diversified. This highlighted increasing competition among removal technologies.

Fourteen deals were recorded, including seven from companies making their first major carbon removal commitments. Biochar did not lead purchase volumes in that quarter.

biochar carbon credit
Source: ClimeFi

For developers such as Terraton, the opportunity depends on converting demand into verified deliveries. Buyers increasingly use forward offtake agreements to secure future supply, while developers need financing to build facilities before issuing credits.

Offtake Agreements Support Terratonโ€™s Expansion

Terratonโ€™s commercial agreements cover several stages of its planned production:

  • Climeworks Solutions committed to purchasing 2,000 tonnes from EcoFix and reserved a further 14,000 tonnes from future Terraton facilities.
  • Climate Impact Partners agreed to purchase credits from EcoFix, the upcoming Tupande project and facilities still in development.
  • Terraset signed a seven-year offtake agreement covering up to 14,000 tonnes from future facilities, with annual purchase volumes confirmed in advance.
  • Carbonfuture will bring up to 32,500 tonnes of carbon removal to market through 2031 using its trust infrastructure.
  • CUR8 secured a purchase of 240 tonnes, extending Terratonโ€™s customer base to a leading global consumer brand.

These figures describe different types of arrangements and should not be treated as equivalent to credits already issued or delivered. The overall potential volume also includes future production that depends on facility development and performance.

Chris Walters, Sourcing Manager at Climate Impact Partners, said:

โ€œWe see growing demand from corporate buyers for tech-based carbon removals, but scaling supply remains a major challenge. Terraton’s approach combines project development, financing, operations and carbon markets to deliver new biochar projects efficiently and at scale, which presents a valuable addition to our portfolio of carbon removal projects.โ€

HSBC Financing Targets More Biochar Facilities

HSBC Venturesโ€™ $1.5 million debt financing will support facility development over the next two years. Terraton is also developing a $25 million pooled financing vehicle intended to fund approximately 20 additional biochar facilities.

The company plans to standardize equipment, facility design, operating procedures, and reporting across projects. This approach could make it easier to assess and finance multiple facilities as a portfolio rather than evaluating each site independently.

Terraton expects its next facilities to reach credit issuance faster than EcoFix, as the company can reuse the technical systems and operating experience developed at its first site. Its next project, built with Tupande, One Acre Fundโ€™s Kenyan brand, is already being commissioned in Sagana, Kenya.

  • It has also signed 28 additional memorandums of understanding and identified more than 30 other sites in its development pipeline across Africa, South America, South Asia and Southeast Asia.

Kevin Gibbs, CEO of Terraton, noted:

“The facility at EcoFix went from investment decision to issued credits in fourteen months, all while we were still building our software, structuring our credits, and learning the ins and outs of our equipment. Our next sites start with all of that experience in place, positioning us to deliver facilities and credits faster.”

Terratonโ€™s growth will depend on how quickly it can replicate its model. Standardized facilities could lower costs and attract financing, but future credit issuance will depend on reliable operations and independent verification. The company was also one of 10 winners of the World Economic Forumโ€™s UpLink Scaling Carbon Dioxide Removal Challenge for its approach to scaling biochar projects.

Sweden Awards โ‚ฌ840 Million to Three Carbon Capture Projects to Store 5.75 Million Tonnes of COโ‚‚

Sweden is committing โ‚ฌ840 million to three carbon capture projects that aim to permanently store millions of tonnes of carbon dioxide (COโ‚‚). The funding marks another step in the country’s plan to reach net-zero emissions by 2045 and achieve negative emissions after that.

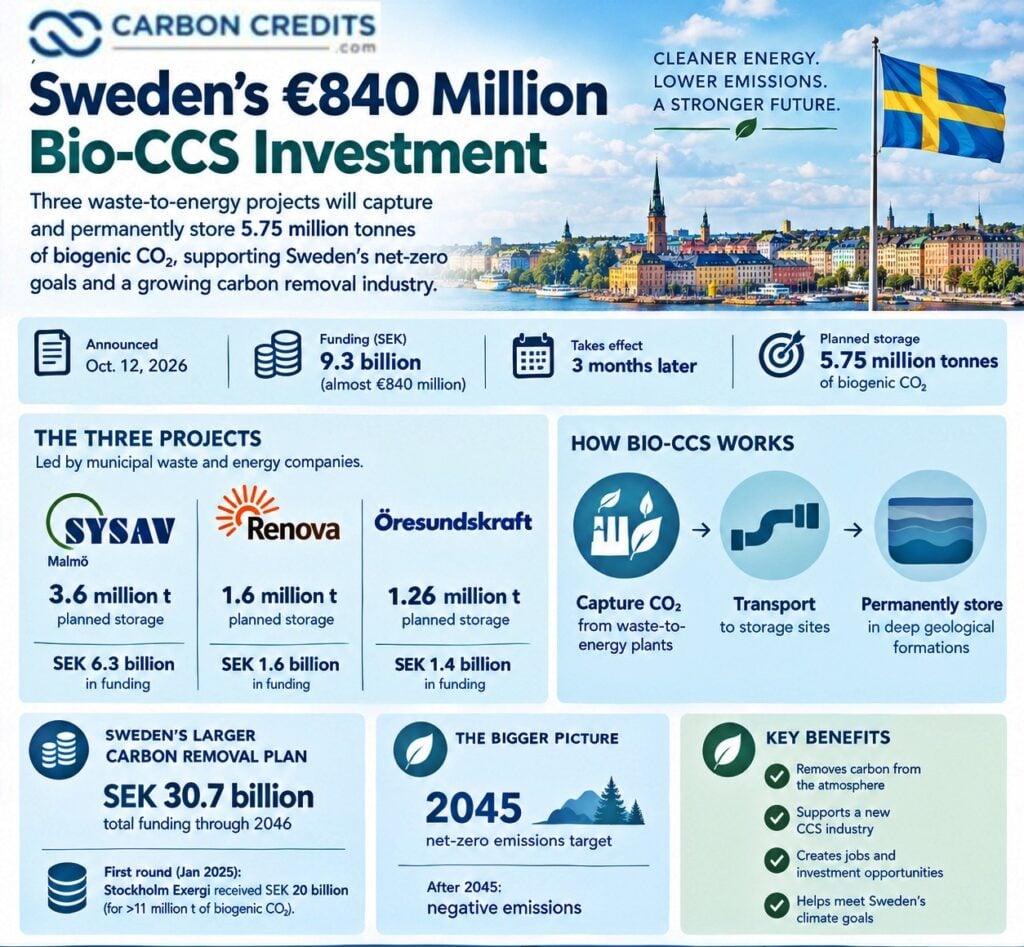
The Swedish Energy Agency awarded SEK 9.3 billion (almost $950 million) to three waste-to-energy operators: Renova, SYSAV, and ร–resundskraft. Together, their projects plan to capture and permanently store 5.75 million tonnes of biogenic COโ‚‚.

The funding comes through Sweden’s second government auction for bio-CCS, a technology that captures carbon dioxide from biological sources and stores it underground.

The projects could help Sweden remove more carbon from the atmosphere while building a new industry around carbon capture and storage. However, the planned storage volumes still need to be delivered. The funding will be paid out as storage begins, rather than as a single upfront payment.

Sweden Backs Three Carbon Capture Projects

The three projects are led by municipal waste and energy companies. Their facilities process waste and produce electricity and district heating. Adding carbon capture could allow them to store COโ‚‚ that would otherwise enter the atmosphere.

The Swedish Energy Agency divided the SEK 9.3 billion award among the projects as follows:

  • SYSAV: SEK 6.3 billion to develop its SkyZero carbon capture project in Malmรถ.
  • Renova: About SEK 1.6 billion for its carbon capture plans.
  • ร–resundskraft: About SEK 1.4 billion for its project.

The three companies plan to store 3.6 million tonnes, 890,000 tonnes, and 1.26 million tonnes of biogenic COโ‚‚, respectively, during their support periods. These amounts add up to 5.75 million tonnes.ย 

The projects must begin geological storage within four years of the funding decision. The government will release the support as storage activities begin. This structure links public funding to project delivery. It also gives the companies support for both construction costs and operating expenses.

How Bio-CCS Can Create Negative Emissions

Bio-CCS combines carbon capture and storage with COโ‚‚ from biological sources. Plants absorb COโ‚‚ as they grow. When biomass is used in industrial processes or burned for energy, that carbon can return to the atmosphere.

Bio-CCS captures the COโ‚‚ and stores it in deep geological formations instead. If the process meets the required conditions, it can remove carbon from the atmosphere and create negative emissions.

This differs from capturing fossil COโ‚‚. Fossil fuels release carbon that has been stored underground for millions of years. Capturing and storing those emissions can prevent additional COโ‚‚ from entering the atmosphere, but it does not automatically remove carbon that is already there.

The distinction matters for climate targets and carbon removal markets. Projects must show where the captured carbon comes from, how much is stored, and whether the storage remains secure.

The Swedish projects will capture COโ‚‚ from waste-to-energy plants. These facilities process mixed waste, which contains both biological materials and fossil-based materials such as plastics.

As a result, not all captured COโ‚‚ will count as biogenic carbon removal. The climate benefit depends on the amount of biogenic COโ‚‚ captured and permanently stored, along with the emissions produced across the process.

Swedenโ€™s โ‚ฌ840 Million Bio-CCS Investment

Sweden Uses Reverse Auctions to Allocate Carbon Removal Funding

Sweden uses reverse auctions to allocate support for bio-CCS projects. In a standard auction, buyers compete to pay the highest price. In a reverse auction, project developers compete to provide a service at the lowest required level of public support.

For Sweden’s program, applicants had to meet technical and other requirements and offer a credible plan for capturing, transporting, and permanently storing biogenic COโ‚‚. The agency then assessed the bids and awarded support to eligible projects.

The aim is to direct public money toward projects that can deliver negative emissions at a lower cost to taxpayers. The second auction closed in August 2026. Renova, SYSAV, and ร–resundskraft were the only three applicants, and all three received funding.

The award also shows that bio-CCS is still developing as a market. Large projects require significant investment in capture equipment, transport systems, and access to suitable geological storage. Government support can help cover these costs while the industry develops its business models.

Sweden’s Larger Carbon Removal Industry: SEK 30 Billion in Awards

The latest award is part of a wider Swedish program worth SEK 30.7 billion through 2046. In January 2025, Stockholm Exergi received SEK 20 billion in the first funding round. Its project plans to store more than 11 million tonnes of biogenic COโ‚‚ over the support period.

With the latest awards, about SEK 29.3 billion of the total funding budget has now been allocated to four companies: Stockholm Exergi, Renova, SYSAV, and ร–resundskraft. Together, their projects have the potential to store nearly 17 million tonnes of biogenic COโ‚‚ by 2046.

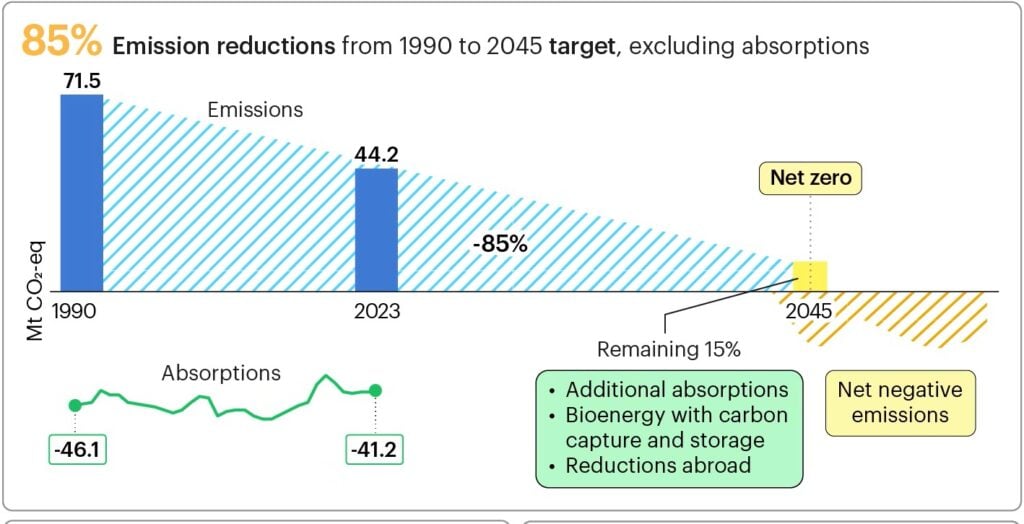
Sweden aims to reach net-zero greenhouse gas emissions by 2045 and achieve negative emissions afterward. Cutting emissions across the economy remains essential, while carbon removal can help address emissions that are difficult to eliminate.

Sweden net zero target
Source: IEA

The country has several potential advantages for bio-CCS, including its forest industry and facilities that produce biogenic COโ‚‚. However, turning this potential into real carbon removal will require reliable technology, transport and storage systems, and long-term monitoring.

Could Swedenโ€™s Bio-CCS Investment Help Scale Carbon Removal?

Sweden’s investment could help establish a stronger business case for engineered carbon removal in Europe. Bio-CCS projects need large amounts of capital before they can begin storing COโ‚‚. Government support reduces some of that financial risk and helps companies build the infrastructure needed to operate at scale.

The projects may also help develop expertise in carbon capture, transport, geological storage, and emissions measurement. These services could become important as more industries look for ways to reduce emissions and remove carbon.

However, public funding does not automatically mean that carbon credits will be issued or sold. Any credits linked to these projects would depend on the applicable rules, accounting methods, verification, and market arrangements.

Buyers and investors will also need clear evidence of how much COโ‚‚ is captured, how much is biogenic, and how much reaches permanent storage. Energy use, transport, and other project emissions must be considered when assessing the overall climate benefit.

The projects’ progress will therefore matter as much as the size of the funding award.

Can Sweden Turn Bio-CCS Funding Into Lasting Climate Gains?

Sweden’s โ‚ฌ840 million award gives three carbon capture projects a major boost. Together, they aim to store 5.75 million tonnes of biogenic COโ‚‚, while the wider government program seeks to build a larger industry for permanent carbon removal.

The reverse-auction model links support to planned storage and helps direct public funds toward eligible projects. But the expected climate benefits will depend on whether the companies build their facilities, start storage on time, and verify the amount of biogenic COโ‚‚ permanently stored.

For carbon markets, the key lesson is that public funding can help bring carbon removal projects closer to reality. Still, the lasting climate value will depend on measured, verified, and permanent storage.

Citiโ€™s $72 Million Carbon Removal Deal Bets on Biochar to Scale Climate Finance

Citi has closed a $72 million carbon removal-linked note to help expand a Texas project that turns farm waste into biochar. The deal links investor payments to the delivery of verified carbon removal credits, creating a new way to finance projects that take carbon dioxide out of the atmosphere.

The 3.5-year, principal-protected note supports Applied Carbonโ€™s mobile technology for processing agricultural waste. Nuveen, an investment firm, joined the deal. Microsoft supports long-term demand through its carbon credit purchase agreement with Applied Carbon.

The transaction highlights a growing challenge in the carbon removal market: projects need money to build and deploy equipment before they can produce credits. By linking finance to future carbon removal, Citi aims to help bridge that gap.

How Citi Links Investor Payments to Verified Carbon Removal

Citi structured the note so that investors give up traditional coupon payments in exchange for a different payment structure. An upfront amount goes toward financing Applied Carbonโ€™s project. Investors then receive payments linked to the issuance and delivery of carbon credits generated by the project.

Sonia Battikh, Global Head of Carbon Offsets Trading at Citi, remarked:

“This Carbon Removal-Linked Note builds on Citi’s pioneering work linking bond performance to environmental outcomes and marks our first outcome bond tied to verified carbon removals. By bringing together investors, project developers and long-term carbon demand, we are continuing to expand the range of opportunities through which capital markets can finance real-world outcomes.”

The note is described as principal-protected and runs for 3.5 years. However, Citi has not publicly disclosed the full payment formula, the expected investor return, or the number of carbon removal credits tied to the transaction. The $72 million is the size of the note, not a disclosed price per tonne of carbon removed.

Citi calls the deal its first outcome bond tied to verified carbon removal. In an outcome-linked structure, financial returns depend in part on a measurable result. Here, that result is the issuance and delivery of carbon credits. This structure connects three parts of the carbon removal market:

  • investors who provide capital,
  • a developer that builds and operates the project, and
  • buyers that create demand for the credits.

If it works as intended, the model could help other projects attract funding before they generate all their expected carbon removal.

Citiโ€™s $72M Carbon Removal Deal

Applied Carbon Turns Farm Waste Into Biochar

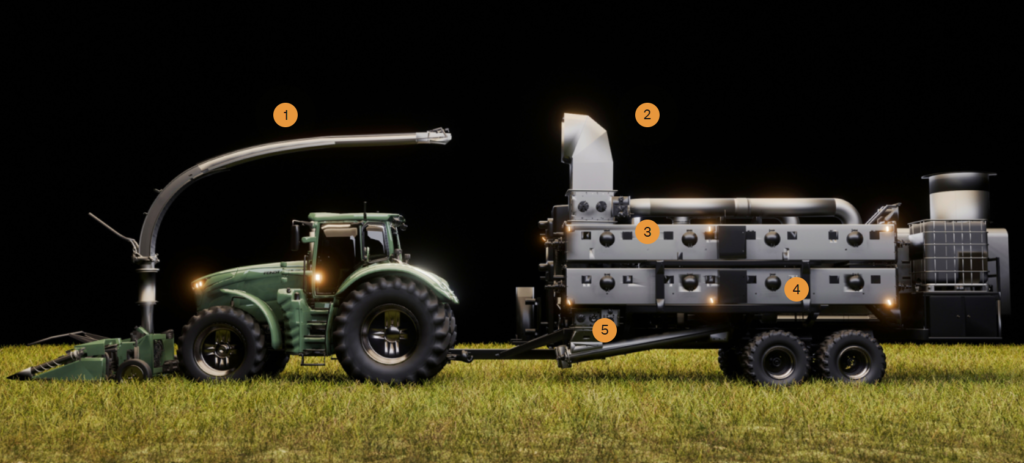
Applied Carbon uses mobile pyrolysis equipment to process crop residue into biochar. Pyrolysis heats organic material with little or no oxygen, turning it into a carbon-rich solid rather than allowing it to decompose or be burned in the open.

The companyโ€™s system can operate directly in fields or at field edges. It combines crop residue processing and biochar application in one pass, reducing the need to transport bulky agricultural waste to a separate facility. The company says this approach can make production more flexible across the farming cycle.

Biochar can store carbon in a relatively stable form when the material and its use meet the right conditions. Applying it to soil may also improve moisture retention and soil properties. But the amount of carbon stored for the long term depends on factors such as the feedstock, production process, biochar quality, and final use.

Applied Carbon biochar technology
Source: Applied Carbon

Applied Carbon announced a $21.5 million funding round in July 2024 to deploy its technology. The company has also been selected for U.S. Department of Energy carbon removal prize programs. The new Citi-linked note provides another financing route to support deployment.

Microsoftโ€™s Credit Deal Helps Support Future Demand

A key part of the financing is the projectโ€™s existing relationship with Microsoft. In March 2022, Applied Carbon announced that Microsoft had selected its biochar project for its carbon removal portfolio. Citi says Microsoft has an offtake agreement for a portion of the credits generated by the project.

An offtake agreement is a contract to buy future production. For carbon removal projects, it can give developers a clearer view of future revenue, helping them plan investment and operations. It may also help lenders and investors assess whether a project can generate enough income to support its financing.

However, the deal does not mean every tonne of expected removal has already been delivered. The Citi note links payments to the issuance and delivery of credits, while the full credit volume and delivery schedule have not been disclosed publicly.

Carbon Removal Demand Rises as Biochar Production Expands

The financing arrives as carbon removal demand and biochar production expand, although the market still faces challenges in scaling supply. A 2026 review by Climeworks notes that, based on market data from BloombergNEF, CDR.fyi, and AlliedOffsets, carbon removal offtakes hit 64 million metric tonnes in 2025. This is an increase from 30 million tonnes in 2024.

Durable carbon removal offtakes rose from 8 million tonnes to 29 million tonnes over the same period. The report valued the overall carbon removal market at about $8 billion in 2025. These figures refer to contracted offtakes, not carbon removals already delivered or credits retired.

Biochar is part of this wider growth. The International Biochar Initiativeโ€™s 2025 Global Biochar Market Report found that global biochar production hit 520,810 metric tonnes in 2025. This is a rise from 180,150 tonnes in 2023.

US biochar production
Source: International Biochar Initiative

The report drew on responses from 930 stakeholders across 96 countries. Survey respondents projected production could reach 3.5 million tonnes by 2027 and 9.3 million tonnes by 2030. These are industry projections, not guaranteed outcomes.

The market still needs more investment. The same report identified limited access to capital as a barrier for 35% of respondents. A separate Climeworks review noted that carbon removal projects often need funding before construction, while buyers may prefer credits delivered years later. That gap makes financing models tied to future credit delivery potentially important.

How the Deal Fits Citiโ€™s Wider Climate Finance Strategy

Citiโ€™s note fits within its wider sustainable finance strategy. The bank has a goal to support $1 trillion in sustainable finance by 2030. It has also committed to net zero greenhouse gas emissions from its own operations by 2030 and from its financing activities by 2050.

These commitments cover different parts of Citiโ€™s business. Financing a carbon removal project is not the same as cutting emissions from the bankโ€™s own offices or reducing emissions linked to its lending and investment activities. The note should therefore be viewed as a financial product that supports a carbon removal project, rather than proof that Citi has met its own emissions targets.

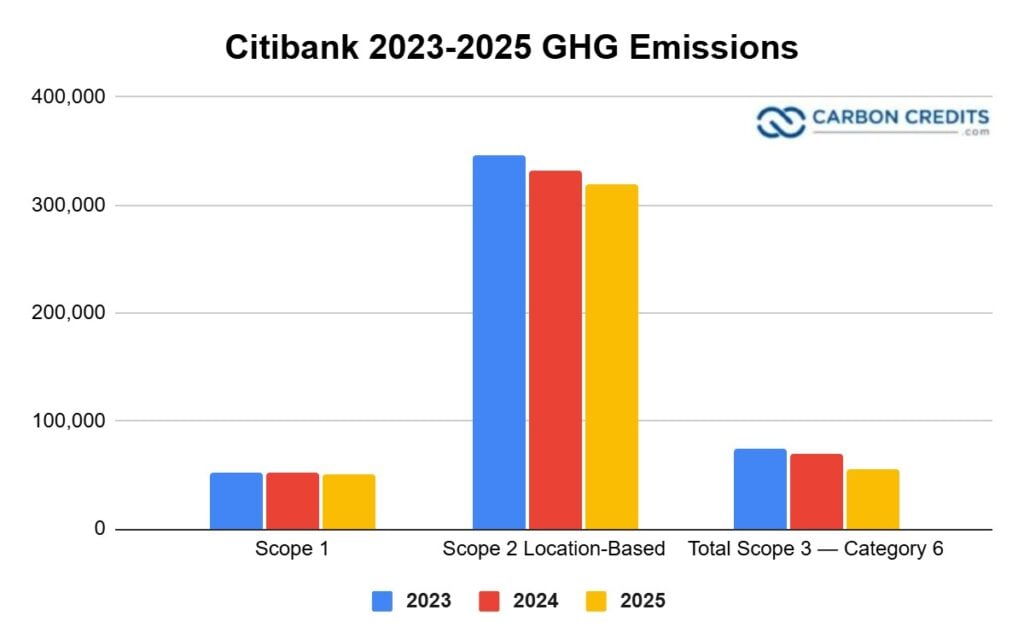
Yet, it is remarkable to note that Citiโ€™s location-based Scope 1 and 2 emissions fell 3.8% in 2025 to 370,030 metric tons of COโ‚‚e. The bank also reduced energy consumption by 43% from its 2010 baseline, surpassing its earlier 40% reduction target, while maintaining 100% renewable electricity sourcing in 2025. These results show progress in reducing emissions from its own operations, including buildings and electricity use.

Citibank GHG emissions 2025

Citi has previously structured sustainable finance products that link financial returns to environmental or social outcomes. The bank says this new note is its first outcome bond tied to verified carbon removals. The deal extends that approach into a market where developers often need large amounts of upfront capital, and buyers want confidence that credits will be delivered.

Verified Credits and Delivery Will Decide the Dealโ€™s Success

The projectโ€™s climate value will depend on more than the size of the note. Credible carbon removal requires accurate measurement of how much carbon is stored, accounting for emissions from collecting and processing feedstock, and checks that the carbon remains stored for the period claimed.

Biochar can offer durable storage, but results vary by production method, material, and application. Project monitoring also needs to guard against overestimating the climate benefit or counting the same removal more than once.

Investors face a separate question: whether the project generates and delivers enough eligible credits, on time, to support the noteโ€™s payment structure. Citi has not disclosed the expected credit volume, price per tonne or investor returns, so the financial and climate outcomes cannot yet be fully assessed from public details.

Even so, the transaction offers a clear example of how banks, institutional investors, technology developers and corporate buyers can work together to finance carbon removal. Its longer-term significance will depend on whether Applied Carbon can scale its equipment, deliver verified credits and show that the model can support more projects.

Tesla (TSLA) Q3 Earnings Shock: Carbon Credit Revenue Crashes 73%, Profits Sink 43%

Tesla (NASDAQ: TSLA) reported nearly flat third-quarter 2026 revenue as declining automotive regulatory credit sales and lower vehicle deliveries weighed on its financial performance. The electric vehicle (EV) maker generated $28.05 billion in revenue, while net income attributable to common stockholders fell 43% year over year to $787 million.

The results highlight Teslaโ€™s changing business model as it invests in artificial intelligence (AI), robotics and battery storage. While its energy storage deployments increased, revenue from automotive regulatory credits continued to decline, reducing a historically important source of high-margin income.

According to Teslaโ€™s Q3 2026 earnings update, the company generated $1.53 billion in free cash flow and ended the quarter with $45.45 billion in cash, cash equivalents and short-term investments.

Tesla Q3 2026 Earnings: Key Financial Results

Teslaโ€™s total revenue was broadly unchanged from $28.10 billion in Q3 2025. However, operating income fell 56% to $718 million as operating expenses increased and regulatory credit revenue declined.

Its adjusted earnings per share were $0.48, compared with $0.50 a year earlier.

Here’s the complete breakdown of the results:

tesla Q3
Source: Tesla

The company’s free cash flow was $1.53 billion, down 62%.

Operating expenses rose 39% to $4.78 billion, driven partly by research and development spending. Capital expenditure increased 110% to $4.73 billion as Tesla expanded its infrastructure and invested in future technologies.

Tesla Carbon Credit Revenue Drops to $113 Million

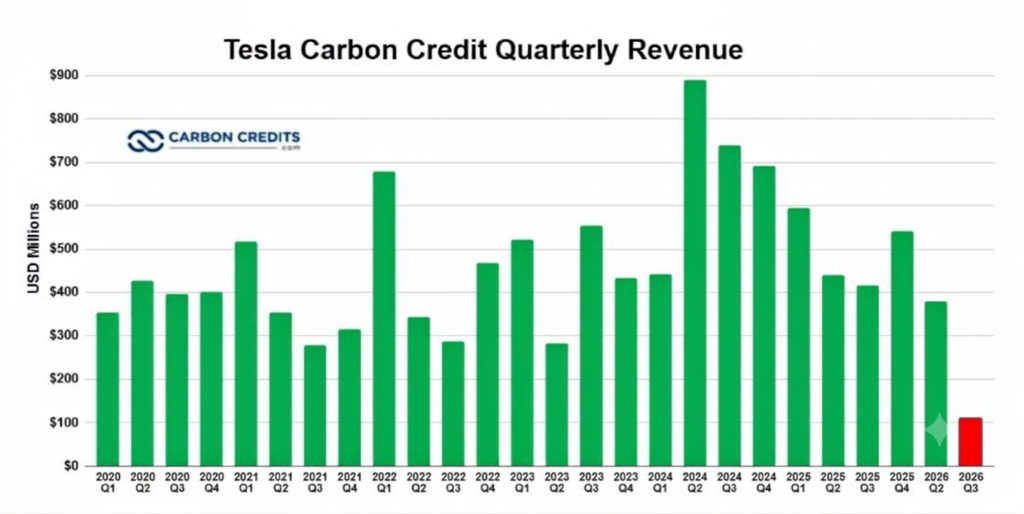
  • Teslaโ€™s automotive regulatory credit revenue fell to $113 million in Q3 2026, down 73% from $417 million in Q3 2025. Revenue also declined 23% from $146 million in Q2 2026.

The credits accounted for approximately 0.4% of Teslaโ€™s total quarterly revenue, compared with 1.5% a year earlier. Tesla cited lower regulatory credit revenue as a factor weighing on both revenue and operating income.

The decline follows a broader downturn in Teslaโ€™s credit business. In 2025, the company generated $2.76 billion from regulatory credits, a record high in 2024, before annual credit revenue fell 28% to approximately $2 billion in 2025. The quarterly figures show that the decline has continued into 2026.

tesla carbon credits
Data Source: Tesla

Tesla earns this revenue by selling surplus automotive regulatory credits to other automakers that need them to comply with emissions requirements. These credits have historically supported profitability because they provide revenue without the manufacturing costs associated with selling vehicles.

However, as more automakers expand their EV lineups, some need fewer credits from Tesla. Changes in emissions policies and compliance requirements can also affect demand. The latest results underline the financial impact of this shift as Tesla faces pressure to generate more earnings from its core businesses.

Vehicle Deliveries and Automotive Revenue Face Pressure

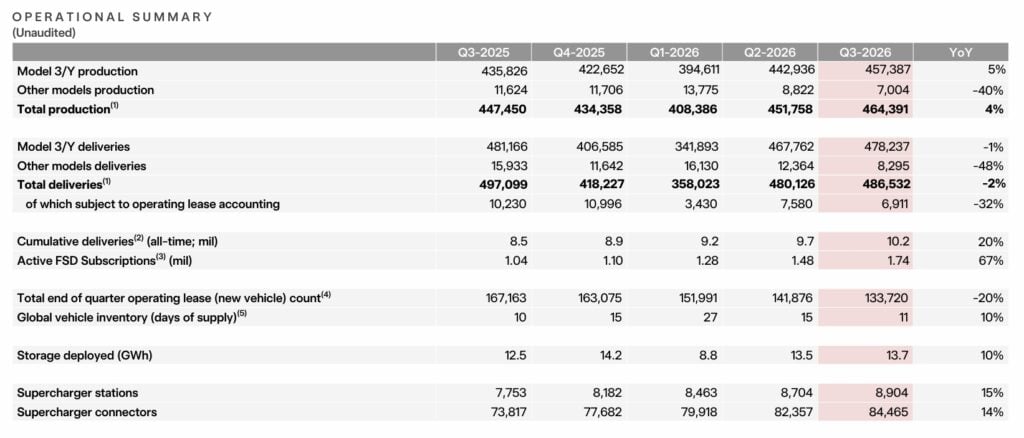
Tesla delivered 486,532 vehicles during the quarter, down 2% year over year, despite producing 464,391 vehicles, up 4%.

Automotive revenue reached $20.56 billion, down 3% from a year earlier. The company also cited lower average selling prices and fewer deliveries as factors affecting revenue.

Services and other revenue increased 33% to $4.61 billion, supported partly by growth in automotive ancillary sales and Full Self-Driving (Supervised) subscriptions. Active FSD subscriptions reached 1.74 million, up 67% year over year.

These businesses could help diversify Teslaโ€™s revenue as regulatory credit income becomes less significant. However, higher research and development costs and investments in AI and robotics continue to weigh on near-term profitability.

tesla automotive

Tesla Energy Storage Business Offers a Growth Opportunity

Teslaโ€™s energy generation and storage revenue declined 16% year over year to $2.88 billion. However, the company deployed 13.7 gigawatt-hours (GWh) of energy storage products, up 10% from Q3 2025.

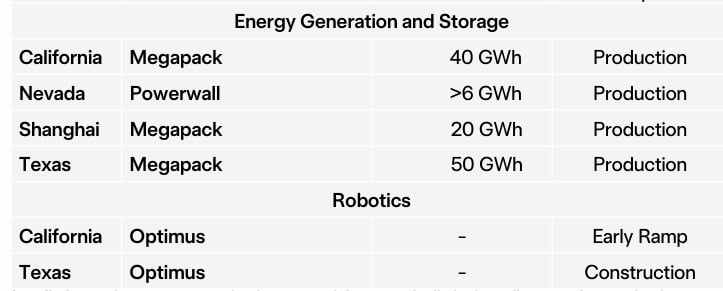
Tesla said demand remained strong, with its highest-ever quarterly order rate and backlog. Production also began at Megafactory Texas, which has a planned annual capacity of 50 GWh.

The energy storage business could benefit from rising electricity demand from data centers and the expansion of renewable energy. Grid-scale battery systems, including Teslaโ€™s Megapack, can store electricity and help manage fluctuations in demand, support grid reliability, and integrate variable renewable power.

tesla battery storage
Source: Tesla

Tesla expects data center demand to support future storage sales. Still, the latest revenue decline shows that strong orders and deployment growth do not always translate into higher quarterly revenue.

What Teslaโ€™s Earnings Mean for Investors

Teslaโ€™s Q3 2026 results show why investors are watching its transition beyond vehicle manufacturing. TSLA shares traded at $386.96 on October 21, 2026, gaining 3.55%.

tesla stock
Source: Tesla

The companyโ€™s $45.45 billion cash position provides financial flexibility to fund its expansion. However, Tesla will need stronger operating performance to offset the declining contribution from regulatory credits and support its investments in AI, robotics, and energy storage.

For the clean energy market, battery storage remains an important growth opportunity as power demand rises and electricity grids adapt to renewable energy. For Tesla (TSLA stock) investors, the challenge will be turning that opportunity into sustained revenue growth and stronger profitability as its traditional credit business loses importance.

Amazon (AMZN), American Electric Power (AEP), and X-energy (XE) Explore 960-MW SMR Nuclear Project in Indiana

American Electric Power (NASDAQ: AEP) is exploring a 960-megawatt (MW) nuclear power project in Indiana with Amazon (NASDAQ: AMZN) and advanced reactor developer X-energy (NASDAQ: XE). The proposed facility could help meet rising electricity demand from data centers and other energy-intensive industries while adding carbon-free power to the regional grid.

Announced on October 19, 2026, the project would use small modular reactors (SMRs) at the former Breed Generating Station site in Sullivan County. Amazon will support development funding and intends to purchase electricity under a long-term contract if the project advances.

The partnership highlights growing interest in nuclear energy as U.S. electricity demand increases. However, the project remains in the feasibility stage, and the companies have not made a final investment decision.

AEP Plans 960 MW of Advanced Nuclear Capacity

The proposed facility would include 12 Xe-100 reactors developed by X-energy. Each reactor would generate 80 MW, bringing the project’s planned capacity to 960 MW.

The companies are evaluating the former site of Indiana Michigan Power’s Breed Generating Station, a retired coal-fired power plant. The location could support a new generation project while creating economic opportunities in Sullivan County.

The partnership combines AEP’s power generation and nuclear operating expertise with X-energy’s reactor technology and Amazon’s financial support and planned electricity purchases.

Bill Fehrman, AEP chairman, president and chief executive officer, said:

“Advanced nuclear energy has the potential to provide dependable power for over half a century while supporting economic growth in our communities. With this development plan, we are working to bring together the resources to help meet unprecedented growth in energy demand with reliable baseload power while protecting affordability for existing customers,” said “Our agreements with Amazon and X-energy will provide all necessary capital protections and financial safeguards that we have said are essential for any potential nuclear project to move forward.”

Source: X-Energy

Amazon’s Long-Term Power Deal Could Protect AEP Customers

Amazon intends to buy power through a long-term agreement designed to cover the facility’s construction and operating costs for the contract period. This arrangement could give the project a more predictable revenue stream while helping protect AEP’s existing customers from its financial risks.

AEP has emphasized that any potential nuclear development must include appropriate capital protections and financial safeguards. The companies must assess feasibility, costs, and other development requirements before deciding whether to proceed with construction.

If completed, the facility could operate for more than 60 years, creating jobs, expanding the local tax base and strengthening Indiana’s electricity infrastructure.

Josh Weissman, VP of Data Center Infrastructure Capacity Delivery at Amazon, said:

“At Amazon, we are committed to serving the needs of our customers and achieving our Climate Pledge goal to be net-zero carbon across our operations by 2040. This collaboration with AEP and X-energy would enable us to make progress on both while ensuring that Indiana’s communities benefit. Together, we’re looking to develop nearly a gigawatt of carbon-free power for the regional grid and pay our full costs without passing them to others. This project would also create jobs and generate tax revenues to benefit Hoosier communities for decades to come.”

Amazon’s Growing Investment in Nuclear Power

Amazon’s involvement reflects the growing need for dependable electricity to support cloud computing and artificial intelligence (AI).

Data centers require substantial amounts of electricity to run servers, cooling systems, and networking equipment. As technology companies expand AI services, securing reliable power has become an increasingly important part of their growth strategies.

Nuclear power can generate electricity around the clock without direct carbon dioxide emissions during operation. It can therefore help meet continuous electricity demand while supporting corporate decarbonization goals.

Amazon aims to reach net-zero carbon emissions across its operations by 2040. The proposed Indiana facility could support that objective while supplying electricity to the wider regional grid.

  • The project also fits into Amazon’s broader collaboration with X-energy to deploy more than 5 gigawatts (GW) of new nuclear capacity in the United States by 2039.

However, the Indiana development remains subject to feasibility assessments, regulatory requirements, financing and construction decisions.

For Amazon investors, the potential benefit lies in securing long-term electricity supplies for its expanding cloud and AI infrastructure. The proposed facility could also support its efforts to reduce operational emissions. Neither benefit is guaranteed at this stage, as the project has yet to move into construction.

U.S. Nuclear Power Capacity Reaches Nearly 98.4 GW

The United States operates the world’s largest commercial nuclear power fleet. According to the U.S. Energy Information Administration (EIA), the country had 94 operating commercial nuclear reactors at 54 power plants across 28 states as of March 2026. Their combined net summer generating capacity was approximately 98.4 GW.

us nuclear

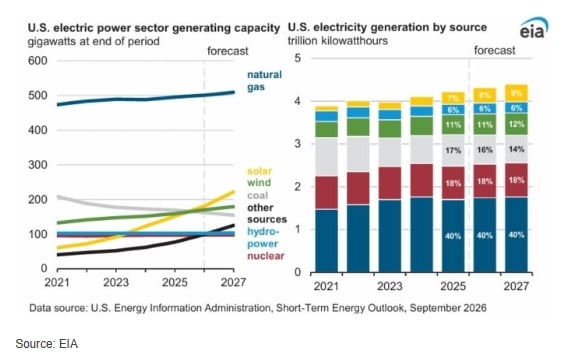
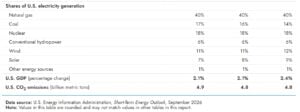
Nuclear energy remains an important part of the country’s electricity mix. The EIA reported that nuclear power supplied about 18% of U.S. utility-scale electricity generation in 2025. Its September 2026 outlook also projected nuclear power’s share would remain around 18% in 2026 and 2027.

US NUCLEAR CAPACIY

Electricity demand is rising as data centers and industrial facilities expand. The EIA also reported that total U.S. electricity generation reached a record 4,429 billion kilowatt-hours in 2025, up 2.8% from 2024. It expects generation to continue growing in 2026 and 2027.

The proposed Indiana project would add 0.96 GW of capacity, equivalent to roughly 1% of the existing U.S. nuclear fleet’s net summer capacity. Although relatively small compared with the national fleet, the project could contribute to efforts to expand dependable, low-carbon electricity supplies.

Small Modular Reactors Could Support Future Growth

Traditional nuclear power plants typically use large reactors, while SMRs are designed around smaller individual units that can be deployed together. The proposed Indiana facility would group its 12 reactors into sets of four.

This approach could offer flexibility when adding generating capacity, but SMRs still face challenges involving licensing, construction costs, financing and commercial deployment. The Indiana project must overcome these hurdles before it can supply electricity.

The broader nuclear industry is also exploring ways to increase output by extending existing plants’ operating lives, restarting retired reactors and developing new facilities. These options could help utilities respond to rising demand while reducing reliance on fossil-fuel generation.

What the Nuclear Project Means for AEP Stock

For AEP, the agreement offers an opportunity to evaluate additional generation capacity as electricity demand grows. The company plans to invest $78 billion from 2026 through 2030 to improve its electricity infrastructure and support customer needs.

Amazon’s proposed long-term power purchase could strengthen the project’s commercial case. Its development funding and planned electricity purchases are intended to help protect AEP customers from project costs.

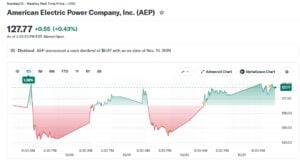
AEP stock
Source: Yahoo Finance

However, investors should distinguish between a development agreement and an operating power plant. The proposed facility will not immediately add to AEP’s generating capacity or earnings. Its eventual financial impact will depend on construction costs, contract terms, regulatory approvals, and operating performance.

For Amazon, the project could provide a long-term source of reliable electricity for data centers while supporting its climate ambitions.

The partnership illustrates how utilities and technology companies are exploring nuclear energy to meet growing power needs. Its progress will depend on whether the partners can turn the development agreement into a technically feasible and commercially viable project.

China Moves to Expand CCER Market With 11 New Carbon Credit Methods

China is proposing a major expansion of its domestic carbon credit market, with 11 new methods that could allow more industries to generate credits for cutting greenhouse gas emissions. The proposals cover clean fuels, battery storage, electric mining vehicles, plastic recycling, and food waste treatment. They could widen the range of projects eligible to earn credits under Chinaโ€™s national voluntary emissions reduction program.

Chinaโ€™s Ministry of Ecology and Environment (MEE) published two groups of draft methods: One contains five proposals, while the other contains six. The ministry is seeking public feedback until October 23. The methods have not yet been approved.

The move comes as China continues to develop its carbon market. If adopted, the new methods could open more ways for companies to earn carbon credits while supporting the countryโ€™s wider efforts to cut emissions.

11 New Methods Target Clean Fuels, Batteries and Waste

The proposed methods cover 11 activities across energy, transport, industry and waste management. Five drafts focus on renewable ammonia, electric mining haulage vehicles, pumped-storage hydropower, chemical recycling of low-value plastics, and biogas production from food waste.

The other six include:

  • Methanol from agricultural and forestry biomass.
  • Methanol from biomass mixed with green hydrogen.
  • Two types of biodiesel from waste oils and fats.
  • Energy storage with sodium-ion batteries.
  • Energy storage with all-vanadium flow batteries.

These activities target different sources of emissions. Some could replace fossil fuels with lower-carbon alternatives. Others could improve energy storage, reduce fuel use in mining, or turn waste into useful products.

The proposed methods would set rules for how eligible projects are designed, assessed, and monitored. They would also establish how projects calculate their emissions reductions and how those results are checked.

That standardization matters because carbon credits need a consistent way to measure the emissions avoided or reduced by a project. Without clear rules, it becomes harder to compare projects and judge whether their claimed climate benefits are real.

New CCER Methods Could Broaden China’s Carbon Credit Market

Chinaโ€™s voluntary carbon credit program is known as China Certified Emission Reduction, or CCER. It works with the countryโ€™s national emissions trading system (ETS). This system requires companies to manage and give up emissions allowances based on government rules.

The CCER program resumed trading in January 2024. It provides a route for eligible projects to generate credits under Chinaโ€™s domestic system. These credits can be used under applicable market rules, including to meet part of the compliance needs of covered companies.

Before this latest proposal, China approved 17 methods under the current CCER framework. This information comes from a June 2026 overview by Columbia Universityโ€™s Center on Global Energy Policy. The 11 new drafts would represent a substantial expansion if they are all approved.

The proposals also reflect a wider effort to bring more types of emissions-reduction projects into the system. Previous methods included:

  • Forest planting,
  • Mangrove restoration,
  • Offshore wind power,
  • Solar thermal power,
  • Energy-saving highway tunnel lighting, and
  • Using low-concentration coal mine gas.

The new proposals extend this approach into areas such as alternative fuels, industrial processes and energy storage. That could give more businesses a path to participate in carbon credit generation, although eligibility will depend on the final rules.

Chinaโ€™s Expanding Carbon Credit Market

RELATED: Chinaโ€™s Farmland Could Remove 350 Million Tonnes of COโ‚‚ a Year, Study Finds

Chinaโ€™s Wider Carbon Market Is Also Growing

China operates two connected but distinct systems: a national emissions trading system (ETS) for covered emitters and the China Certified Emission Reduction (CCER) program, which allows eligible projects to generate carbon credits.

The national ETS is Chinaโ€™s main compliance carbon market. Its trading activity has continued to grow. Cumulative allowance trading exceeded 930 million tonnes by the end of July 2026, according to figures reported by Xinhua and cited by Carbon Herald.

On October 21, Vice-Minister of Ecology and Environment Li Gao announced that cumulative trading had passed 1 billion tonnes. The system covers about 8.3 billion tonnes of COโ‚‚ emissions, representing more than 65% of Chinaโ€™s total carbon dioxide emissions.

China also plans to extend the ETS to major emitting industries, including petrochemicals and chemicals, by 2027. The government said its policies helped reduce emissions in the thermal power sector by about 530 million tonnes of COโ‚‚ during 2021โ€“2025.

china compliance carbon market ets
Source: WEF Asiaโ€™s Carbon Markets Strategic Imperatives for Corporations, 2025.

These developments provide important context for the 11 proposed CCER methods. While the ETS regulates emissions through allowance trading, the CCER program creates a route for eligible projects to earn credits. The proposed methods could expand the types of projects that qualify, but their impact will depend on final approval and the verified emissions reductions they deliver.

Carbon Credit Quality Will Depend on Strong Measurement Rules

More methods could create more routes for companies to seek carbon credits. But expanding the list of eligible activities does not guarantee that every project will deliver the emissions reductions it claims.

The final methods will need clear rules for setting emissions baselines, measuring results, and checking project performance. A baseline estimates what emissions would have occurred without the project. The difference between that baseline and the projectโ€™s actual emissions helps determine how many credits it may qualify to generate.

The rules also need to account for emissions created during production and operation. For example, a fuel made from waste or biomass is not automatically emissions-free. Its overall climate benefit depends on factors such as how the feedstock is sourced, how much energy production uses, and what emissions the new fuel replaces.

Energy storage projects also need sound accounting. Their climate benefits can depend on when and how the stored electricity is generated and used. If a battery charges with high-emissions electricity, its benefit may be smaller than if it stores power that would otherwise go unused from a lower-carbon source.

These issues make measurement, reporting, and verification essential. Strict rules can help ensure that credits reflect real emissions reductions rather than overstated estimates.

Public Consultation Is the Next Step

Chinaโ€™s consultation period for all 11 draft methods closes on October 23, 2026. The MEE will consider feedback before the proposals can move forward. The ministry has not yet confirmed that all 11 will be approved.

For project developers, approval could create new opportunities to seek crediting under the CCER program. For companies that buy credits to meet applicable obligations, the new methods could eventually broaden the range of available projects.

However, the number of proposed methods is only one measure of progress. The next milestones will be final approval, clear eligibility rules, project registration, and verified emissions reductions.
Chinaโ€™s proposal signals a wider scope for its domestic carbon credit system. Whether that expansion leads to a meaningful increase in high-quality credits will depend on how the methods are finalized and applied in practice.

Lithium Demand to Hit 4.8 Million Tonnes by 2050, BNEF Forecasts

Global demand for transition metals is expected to grow as electric vehicles (EVs), renewable energy, battery storage and electricity networks expand. However, supply risks vary across commodities, with some markets facing potential shortages while others could experience oversupply.

BloombergNEFโ€™s (BNEF) Transition Metals Outlook 2026 highlights these differences. Copper faces the biggest long-term supply challenge, while lithium demand could triple by 2050. However, new mining capacity could ease lithium shortages in the near term and put pressure on prices as supply expands.

The outlook presents both opportunities and risks for mining companies and investors. Demand for battery materials is growing, but rising consumption does not automatically guarantee higher prices or stronger returns for producers.

Transition Metals Demand Will Rise Through 2050

BNEFโ€™s report examines 10 materials: aluminum, cobalt, copper, graphite, lithium, manganese, nickel, palladium, platinum and steel. Under the report’s Economic Transition Scenario, demand for eight of these materials is expected to rise by 2050.

Copper presents the biggest long-term challenge. Demand could rise 61% between 2026 and 2050, reaching nearly 46 million metric tons annually. Without additional supply, the market could face a deficit of 20 million metric tons by 2050, equivalent to 44% of projected demand. BNEF estimates that bridging this gap could require $332 billion in new mine investment.

Graphite is another major growth market, with demand expected to more than double by 2050 as battery production expands. Meanwhile, changes in battery chemistry, particularly the growing adoption of lithium iron phosphate (LFP) batteries, have reduced BNEFโ€™s demand projections for cobalt and nickel compared with previous estimates.

lithium

Recycling Will Help Close Supply Gaps

China dominates the refining of several transition metals, leaving manufacturers in other regions exposed to trade restrictions and supply disruptions. Governments and companies will need to diversify sourcing and expand recycling to strengthen supply security.
BNEF expects recycling to become essential for six of the 10 materials by 2035 and eight by 2050. Battery recycling is projected to expand faster than primary production between 2026 and 2050.

Recycling could help companies:

  • Recover valuable metals from used batteries.
  • Reduce reliance on newly mined materials.
  • Diversify supply chains and limit exposure to trade disruptions.
  • Support demand growth as more EV batteries reach the end of their useful lives.

Lithium Demand Could Reach 4.8 Million Tonnes

Lithium is a key material in rechargeable batteries used in electric cars, consumer electronics and grid-scale energy storage. Demand is expected to increase as transport electrification accelerates and power systems require more storage to balance variable renewable electricity generation.

According to BNEF, global lithium demand is projected to rise from 1.6 million metric tons of lithium carbonate equivalent (LCE) in 2026 to 4.8 million metric tons in 2050. This represents a threefold increase over the period.

Lithium demand supply
Source: BNEF

EVs and Battery Storage Drive Growth

Electric vehicles remain a major source of lithium consumption, but stationary battery storage is becoming increasingly important. Utilities are installing batteries to balance electricity supply and demand, support grid reliability, and store excess solar and wind power. Rising electricity consumption from data centers could also strengthen the need for storage.

The main demand drivers include:

  • Electric vehicles: Automakers continue to expand their EV offerings and battery manufacturing capacity.
  • Grid-scale storage: Utilities use lithium-ion batteries to improve grid flexibility and integrate renewable power.
  • Renewable energy: Solar and wind projects need storage to help manage changes in electricity generation.
  • Battery technology: Advances in battery design could improve performance and change lithium requirements.

However, the pace of demand growth will depend on EV sales, energy storage investment, government policies and battery technology. Improvements in battery efficiency and the adoption of alternative chemistries could change how much lithium manufacturers need for each unit of storage capacity.

Lithium Production Expands as New Projects Advance

Despite strong long-term demand, lithium supply has expanded rapidly following earlier price increases. Producers developed new mines and processing capacity, contributing to oversupply and a sharp price correction in 2023โ€“2025.

The U.S. Geological Survey (USGS), in its Mineral Commodity Summaries 2026, estimated that global lithium mine production outside the United States rose 31% in 2025 to approximately 290,000 metric tons of lithium content, up from 222,000 tons in 2024. Global consumption reached an estimated 263,000 tons, a 20% increase from 220,000 tons in 2024.

These figures use lithium content rather than LCE, so they are not directly comparable with BNEFโ€™s demand forecast. They nevertheless illustrate the rapid expansion in mining output and consumption.

lithium supply data
Source: USGS

Which Countries Supply Lithium?

Australia, Chile, China and Argentina remain important lithium producers. New projects and capacity expansions in countries such as Brazil, Canada and Zimbabwe could add further supply. However, permitting, financing, infrastructure, and processing constraints can delay new production.

Producers face several challenges as they expand capacity:

  • Securing financing for new mines and processing facilities.
  • Managing production costs when lithium prices fall.
  • Obtaining permits and developing infrastructure.
  • Meeting environmental requirements and local community expectations.
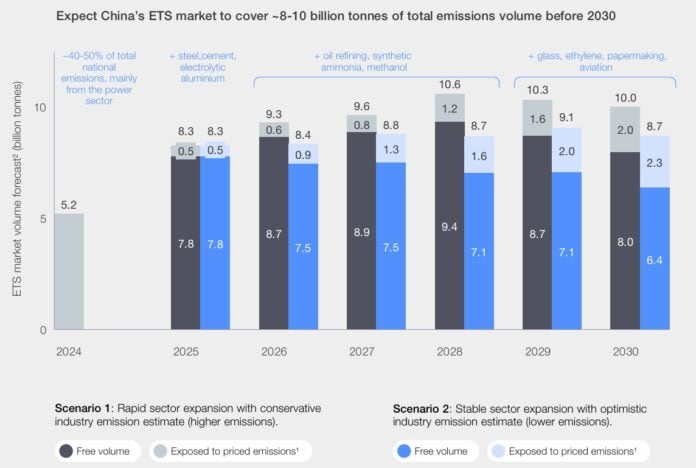
  • Bringing projects online before market conditions change.

A Near-Term Deficit Could Give Way to Surplus

BNEF expects the lithium market to face a near-term deficit in 2026. New supply capacity coming online in 2027 could help resolve the shortfall. Over the longer term, additional production could push the market toward surplus conditions.

For investors, the distinction between a temporary deficit and a structural shortage matters. Delayed projects or production cuts could tighten the market, while rapid capacity growth could limit producersโ€™ pricing power.
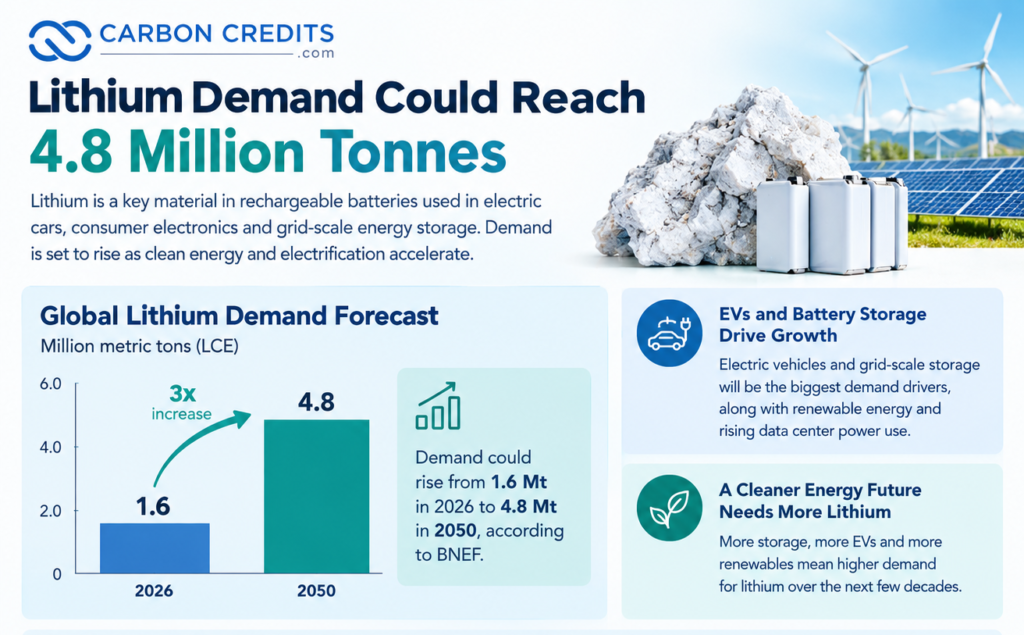
Lithium Prices Remain Under Pressure

Lithium prices have been volatile as the market responds to changes in production, demand, and inventory levels.

USGS estimated that the average US contract price for battery-grade lithium carbonate fell to $9,000 per metric ton in 2025, down 31% from $11,800 in 2024. Stronger EV sales in China and Europe, along with growing demand for battery storage, later helped support a market recovery.

Latest data for Lithium Carbonate pricing: LITHIUM CARBONATE PRICES

Recent Price Movements Signal Volatility

S&P Global reported recently that, in 2026, Chinese lithium carbonate prices had fallen 40.3% from their May peak by the end of the third quarter. It also assessed Australian spodumene at $1,695 per metric ton on October 9, down 28.5% from July 1.

The reseach firm expects additional shipments from Zimbabwe and the resumption of Australian production to improve feedstock availability, potentially putting further pressure on prices. Shipment delays and strong spot demand could still trigger renewed volatility.

BNEFโ€™s outlook also points to longer-term pricing pressure as supply capacity expands. Although the market could experience a deficit in 2026, additional production may ease supply conditions from 2027 onward.

For mining companies, this means that controlling costs and managing expansion plans will remain critical, even as long-term demand grows.

Lithium Prices Outlook summarized:ย 

lithium prices

What Could Change the Lithium Outlook?

Several factors will influence the balance between lithium demand and supply.

  • Faster battery storage growth: More grid-scale projects could increase demand beyond current expectations.
  • Mine delays or closures: Supply disruptions could tighten the market and support prices.
  • Faster capacity expansion: New mines could create surplus supply and limit price recovery.
  • Battery innovation: Alternative chemistries and more efficient designs could change lithium consumption.
  • Recycling growth: Recovering lithium from used batteries could reduce reliance on primary production over time.

What the Outlook Means for Investors

Lithium offers long-term demand growth but also significant price risk. Producers with competitive costs, reliable processing capacity and strong balance sheets may be better positioned to withstand market downturns.

The broader transition metals outlook reinforces an important point: growing demand does not automatically lead to sustained shortages or higher prices. Copper faces a potentially widening structural supply gap, while lithium could move from a near-term deficit toward a more balanced or oversupplied market.

Investors should therefore monitor production costs, project timelines, recycling capacity and battery storage deployment alongside demand forecasts. These factors will help determine which companies can turn the energy transitionโ€™s growing need for metals into sustainable returns.