Australia is closing one of its best-known carbon offset programs. The federal government has announced that it will shut down Climate Active, the voluntary certification program that allowed businesses, products, buildings, and events to claim they were carbon neutral.
The move follows years of criticism over the program’s credibility. It also comes as governments, investors, and regulators demand stronger proof behind corporate climate claims.
The decision marks a major change for Australia’s voluntary carbon market, but it does not mean carbon offsets are disappearing. Instead, it shows how the market is shifting toward higher standards and greater transparency.
The End of Australia’s Carbon Neutral Label
Climate Active launched in 2019, replacing the National Carbon Offset Standard (NCOS). The Department of Climate Change, Energy, the Environment and Water (DCCEEW) managed the program.
To earn certification, organizations had to measure their greenhouse gas emissions, reduce them where possible, and offset the rest using approved carbon credits. These included Australian Carbon Credit Units (ACCUs) and some international credits.
Over the years, Climate Active certified more than:
620 businesses and organizations,
More than 1,000 products and services,
More than 100 buildings and precincts, and
Dozens of events and public institutions.
The program attracted companies from many industries, including finance, retail, property, tourism, manufacturing, and professional services.
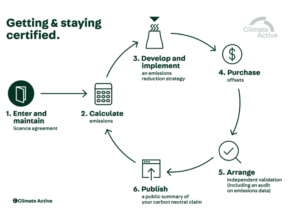
Source: Climate Active
The government has now stopped accepting new applications. Existing certifications will stay in place during a transition period while officials decide what comes next. Climate Active wrote:
“The Australian Government has introduced a comprehensive suite of energy and climate policies that are helping businesses reduce their emissions, guided by a legislated target of net zero emissions by 2050. Climate Active helped fill a gap in the domestic market. But there is now less need for government certification to incentivise voluntary climate action.”
The government hasn’t announced a replacement program yet. However, future policy will focus more on cutting emissions directly and improving climate reporting.
Why the Program Faced Growing Criticism
Climate Active helped many companies begin measuring and managing their emissions. But over time, critics argued that it relied too heavily on carbon offsets.
One of the strongest critics has been the Climate Council, which welcomed the decision to close the program. The group argued that some companies were able to promote themselves as “carbon neutral” even while their operations still produced large amounts of emissions.
Climate Council Senior Advisor Ben McLeod remarked:
“…Climate Active gave the green tick of approval to everything from polluting gas corporations to petrol at the bowser. It was always a distraction from the real job: cutting climate pollution at the source. With Climate Active headed to the scrap heap, it’s time for the Albanese Government to strengthen the Safeguard Mechanism and end the free ride for Australia’s biggest polluters.”
Around the world, regulators are taking a closer look at climate claims. In Australia, both the Australian Securities and Investments Commission (ASIC) and the Australian Competition and Consumer Commission (ACCC) have increased actions against greenwashing.
Companies need to clearly explain how they measure emissions. They should also detail how they use offsets and support their net-zero targets.
The end of Climate Active does not mean Australia’s carbon market is slowing down. Instead, it marks a shift from voluntary carbon-neutral claims to a market driven more by regulation, compliance, and higher-quality carbon credits.
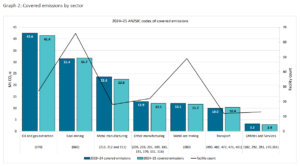
The biggest force behind that change is Australia’s Safeguard Mechanism, the country’s main industrial carbon policy. It covers about 220 of Australia’s largest industrial facilities, including mines, oil and gas operations, manufacturers, and heavy industries. Together, these facilities produce nearly 30% of Australia’s greenhouse gas emissions.
Source: Clean Energy Regulator
Under the policy, emissions limits become stricter each year. Companies that exceed their limits must either reduce emissions or buy Australian Carbon Credit Units to comply.
This has created a much stronger source of demand for carbon credits than voluntary carbon-neutral programs alone.
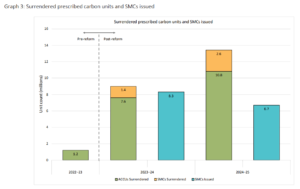
The market’s growth reflects that shift. The Clean Energy Regulator reports that 18.9 million ACCUs were issued in the 2024–25 financial year. This is the highest annual total since the scheme started. More than 41 million ACCUs were traded during the same period, showing strong liquidity and active participation across the market.
Source: Clean Energy Regulator
Australia’s supply pipeline is also expanding. The regulator oversees over 300 carbon projects, including:
Australia’s broader climate policy remains firmly focused on cutting emissions. Under the Climate Change Act, the country aims to reduce greenhouse gas emissions by 43% below 2005 levels by 2030 and reach net zero by 2050.
The Safeguard Mechanism is central to that plan. It sets declining emissions limits for Australia’s largest industrial facilities.
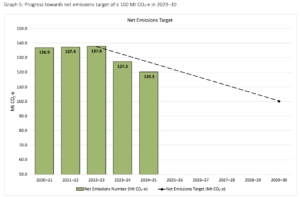
The latest data show the policy is making progress. During 2024–25, net emissions from safeguard facilities fell 5.5% year over year to 120.3 MtCO₂-e, while gross covered emissions declined 2.3% to 132.8 MtCO₂-e.
Source: Clean Energy Regulator
These results suggest Australia’s biggest industrial emitters are beginning to move in line with the country’s long-term climate goals.
Climate Active may be ending, but the market itself continues to grow under a more robust framework.
Higher Standards Are Becoming the New Normal
Australia is not the only country raising the bar for carbon markets. Around the world, governments and businesses are putting more focus on credit quality rather than credit volume.
Global standards are also becoming stricter.
The Science Based Targets initiative (SBTi) says companies should first reduce emissions across their operations and supply chains. Carbon credits should only be used for emissions that cannot yet be avoided.
At the same time, the Integrity Council for the Voluntary Carbon Market (ICVCM) has introduced the Core Carbon Principles (CCPs) to improve credit quality. Recent market data show that 13% to 15% of new carbon credits now have the CCP label. This share is growing as buyers seek higher-quality credits.
Credits that meet high-quality standards are also selling at a premium. According to the MSCI Global CCP Carbon Credit Price Index, CCP-labelled credits have traded at an average 19% price premium over the broader voluntary carbon market since mid-2024.
Together, these changes have raised the bar for corporate climate action. Buying offsets alone is no longer enough. Companies are increasingly expected to cut emissions first and back up any climate claims with clear, transparent reporting.
Trust Will Shape the Next Carbon Market
Climate Active helped introduce many Australian businesses to carbon accounting and carbon offsets. For years, it gave companies a simple way to measure emissions and communicate their climate efforts.
Today, expectations are much higher. And Australia’s carbon market is adapting to that new reality.
The end of Climate Active does not signal the end of carbon offsets. Instead, it reflects a broader shift toward stronger standards, better oversight, and higher-quality credits.
As compliance demand grows and international integrity standards continue to develop, Australia’s carbon market looks set to become more mature, more transparent, and more trusted than before.
Europe reaches a key milestone in carbon removal. Puro.earth has certified the first permanent carbon removal project. This project captures biogenic carbon dioxide (CO₂) from biogas and stores it underground.
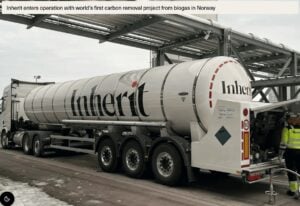
Developed by Inherit Carbon Solutions at Norway’s VEAS wastewater treatment plant, this project is the first biogas-based bioenergy with carbon capture and storage (BECCS) to earn CO₂ Removal Certificates (CORCs). It’s also Puro.earth’s first certified BECCS project in Europe.
This achievement highlights how wastewater treatment plants can aid in permanent carbon removal and support Europe’s climate goals.
First Certified BECCS Project for Biogas in Europe
Puro.earth validated the VEAS project after a third-party audit. This certification follows its Geologically Stored Carbon methodology, ensuring that captured carbon is permanently removed from the atmosphere.
In its first four months of operation, from February to May 2026, the project earned over 700 CO₂ Removal Certificates (CORCs). More certificates will follow as monitoring continues.
Unlike traditional carbon capture projects, this one captures biogenic CO₂ released during biogas production. Since this carbon comes from organic waste, storing it creates negative emissions, effectively removing carbon from the natural cycle.
This project is a key example of engineered carbon dioxide removal (CDR), an industry expected to grow for global net-zero targets.
“Inherit’s issuance shows what’s possible when biogas infrastructure and carbon storage infrastructure are combined through one succinct process. Biogenic CO2 that would otherwise have been released is instead captured and permanently stored. This is exactly the kind of innovative approach to BECCS that the Puro Standard and Registry was built for. Inherit is a true pioneer in this field, and we’re proud to certify the world’s first project of its kind. With the scale of biogas production across Norway, the Nordics and more widely across Europe, the potential for BECCS regionally is significant.”
Turning Wastewater Into Permanent Carbon Removal
The project operates at the VEAS wastewater treatment plant in Slemmestad, Norway, serving over 800,000 residents in Oslo, Bærum, and Asker.
As wastewater is processed, organic material breaks down, producing biogas. This process releases biogenic CO₂. Instead of letting that CO₂ escape, project partners capture and permanently store it.
Three companies work together on this project, each handling a different stage:
Inherit Carbon Solutions develops and manages the carbon removal project.
HoopCO2 captures and liquefies biogenic CO₂.
Northern Lights transports and stores the CO₂ beneath the North Sea.
Once captured, the liquefied CO₂ is trucked to Northern Lights’ terminal in Øygarden, west of Bergen. From there, it moves through pipelines to a geological storage site about 2,600 meters below the seabed, where it remains trapped.
Northern Lights began commercial offshore CO₂ storage in 2025, mainly for fossil-based emissions. The VEAS project is its first operation for biogenic CO₂, marking a shift towards permanent carbon removal.
Under the current agreement, Northern Lights will store up to 7,000 metric tons of biogenic CO₂ each year from the VEAS facility.
On this development, Kaja Voss, CEO, Inherit Carbon Solutions, added,
“Working with Puro.earth through this certification has given us a clear and credible pathway to bring these credits to market. This project shows just how much potential there is across the biogas supply chain for capturing and permanently storing biogenic CO2. The collaboration with HoopCO2 and Northern Lights has been strong, and we’re excited about what this pilot means for scaling biogenic CO2 removal from biogas facilities more broadly.”
Source: Inherit
A Model That Can Scale Across the Biogas Industry
This project stands out because it uses existing infrastructure.
Many wastewater treatment plants and biogas facilities produce biogenic CO₂. By adding capture equipment and connecting to transport and storage networks, they can turn routine waste processing into permanent carbon removal.
This approach avoids building new systems from scratch. Instead, it upgrades existing facilities to provide real climate benefits. Since wastewater plants and biogas facilities operate in many countries, this model could spread across Europe and beyond.
Smaller BECCS projects like VEAS also need lower upfront investments and shorter development times than large carbon capture facilities. This allows developers to launch projects faster while proving commercial viability.
For companies buying durable carbon removal credits, projects like VEAS offer verified removals backed by strict monitoring and permanent geological storage.
Bioenergy with carbon capture and storage is vital for Europe’s climate strategy.
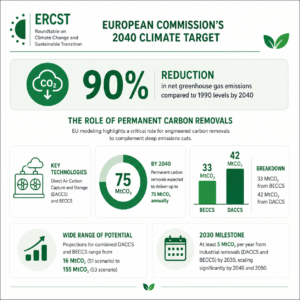
The European Commission’s proposed 2040 climate target aims for a 90% reduction in net greenhouse gas emissions compared to 1990 levels. To reach that goal, emissions cuts alone won’t suffice. Europe expects engineered carbon removal technologies to eliminate millions of tons of CO₂ from the atmosphere each year.
BECCS could remove around 33 million metric tons of CO₂ annually.
Direct Air Carbon Capture and Storage (DACCS) could add another 42 million metric tons.
Together, these technologies could remove up to 75 million metric tons of CO₂ each year.
Some climate scenarios estimate that combined BECCS and DACCS could range from 16 million to 155 million metric tons annually, depending on technology growth and policy support.
The Commission expects industrial carbon removal to reach at least 5 million metric tons per year by 2030, with significant growth in the following decade.
Europe Has Much Greater BECCS Potential
Recent analysis shows Europe could remove even more carbon than current targets require.
As per Bioenergy Europe data, adding carbon capture to 38% of Europe’s biomass facilities could yield about 80 million metric tons of CO₂ removals annually—enough to meet the EU’s projected 2040 needs.
If carbon capture expands to half of existing biomass plants, annual removals could reach about 105 million metric tons.
Europe produces around 220 million metric tons of biogenic CO₂ yearly from bioenergy facilities. Capturing and storing half of that would surpass many climate projections.
The biggest opportunities lie in:
Combined heat and power (CHP) plants
Pulp and paper mills
Waste-to-energy facilities
Biogas production plants
Countries like Sweden, Germany, Finland, and the UK have strong potential due to their large bioenergy sectors. France, Italy, and Austria also have significant untapped opportunities.
Policy Support Will Determine Future Growth
While the technology is available, experts believe that policy support will dictate how quickly BECCS grows in Europe.
Developers are urging stronger demand for durable carbon removals through climate laws, financial incentives, and carbon credit markets. And so investing in CO₂ transport pipelines, shipping terminals, and storage sites will be crucial as more projects begin.
Clear permitting guidelines and stable regulations could lower project risks and attract private investment.
Projects like VEAS show that permanent carbon removal is moving from pilot stages to commercial use. As governments and companies invest in engineered carbon removal, similar BECCS facilities may play a vital role in Europe’s net-zero and net-negative goals. They will also boost the clean energy economy.
The race to build the future of transportation has reached a new city. Tesla and Waymo are both expanding their robotaxi services into Tampa, Florida, bringing two very different self-driving technologies into direct competition.
The move marks another milestone for autonomous vehicles as companies race to make driverless ride-hailing a mainstream business. This expansion comes at a time when interest in robotaxis is growing quickly.
Artificial intelligence (AI) is improving, electric vehicles (EVs) are becoming more common, and cities are looking for cleaner and safer ways to move people. For Tesla and Waymo, Tampa is both a new market and another test of which of them has the stronger path toward large-scale autonomous transportation.
Two Companies, Two Different Roads to Autonomy
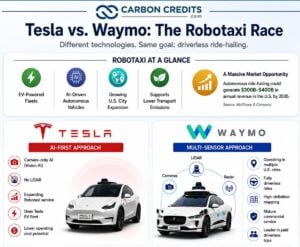
Although Tesla and Waymo share the same goal, they have taken very different approaches.
Waymo, owned by Alphabet, relies on a mix of cameras, radar, and LiDAR sensors. Its robotaxis operate only in carefully mapped areas, known as geofenced service zones. This allows the company to offer fully driverless rides while keeping operations within areas it has already tested extensively.
Tesla has chosen a different strategy. Its Full Self-Driving (FSD) system depends mainly on cameras powered by artificial intelligence. Instead of mapping every street in advance, Tesla trains its AI using data collected from millions of customer vehicles around the world. Chief Executive Elon Musk believes this approach will make it easier and cheaper to expand robotaxi services globally.
The difference also affects costs. Industry analysts estimate that a LiDAR system can add thousands of dollars to the cost of an autonomous vehicle.
Tesla claims its camera-based system can achieve similar results with cheaper hardware. This could make large-scale deployment more affordable if the technology works well.
Source: Tesla; Waymo company reports
Tesla Is Scaling Its AI-First Robotaxi Vision
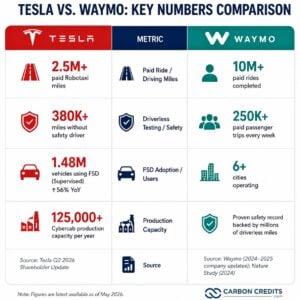
Tesla’s robotaxi business has grown rapidly over the past year. According to the company’s second-quarter 2026 shareholder update, its paid robotaxi service now operates in seven U.S. metro areas. Customers have driven over 2.5 million paid Robotaxi miles.
Tesla’s cars have also recorded more than 380,000 miles without a safety driver during testing and operations.
The EV giant is also expanding the technology behind its robotaxis. The company says 1.48 million vehicles now use its Full Self-Driving (Supervised) software, up 56% from a year earlier. Every mile driven helps train Tesla’s AI system, giving it one of the world’s largest real-world driving datasets.
The company is also preparing for the next stage of growth.
The automaker says its new Cybercab production line is capable of building more than 125,000 vehicles per year. Unlike today’s Model Y robotaxis, Cybercab is designed from the ground up as a fully autonomous vehicle without a steering wheel or pedals.
For Tesla, robotaxis are becoming much more than another vehicle program. They are central to the company’s long-term growth strategy as EV sales slow and competition increases.
Tesla may be expanding quickly, but Waymo remains the industry’s most experienced robotaxi operator. The company now provides more than 250,000 paid passenger trips every week, according to its report.
Since launching commercial service, it has completed over 10 million paid rides, making it the largest fully driverless ride-hailing network in the world.
The company runs robotaxi services in several cities. These include Phoenix, San Francisco, Los Angeles, Austin, Atlanta, and Washington, D.C. Tampa is one of its latest expansion plans.
Waymo’s safety record has also helped build confidence. A study in Nature showed that Waymo’s self-driving cars had far fewer, 68%, injury crashes than human drivers. This was observed over millions of miles. That growing body of real-world evidence has made Waymo the benchmark for commercial robotaxi services today.
Yet, the race is far from over.
Tesla is betting that artificial intelligence and manufacturing scale will allow it to expand much faster than competitors. Waymo, meanwhile, continues to focus on safety, reliability, and steady deployment.
The next few years will show which strategy proves more successful—not only in Tampa, but across the global robotaxi market.
The robotaxi race is about much more than technology. It could also reshape how people travel and how cities cut emissions.
Transportation is the biggest source of greenhouse gas emissions in the U.S. In 2025, it makes up about 28% of all emissions, according to the U.S. Environmental Protection Agency (EPA). Switching from gasoline cars to electric robotaxis can cut emissions. This is true, especially if cleaner electricity is used to charge them.
Robotaxis can also make vehicles more efficient.
Most privately owned cars sit parked for about 95% of the day, according to research from the U.S. Department of Energy. A shared autonomous vehicle can stay on the road much longer, serving multiple passengers instead of remaining idle. Higher vehicle use could reduce the number of cars needed in cities over time while lowering the cost of each trip.
The International Energy Agency (IEA) also sees shared electric mobility as an important tool for reducing oil demand and cutting transport emissions, particularly as electricity grids become cleaner.
A $400 Billion Opportunity Is Fueling the AI Mobility Race
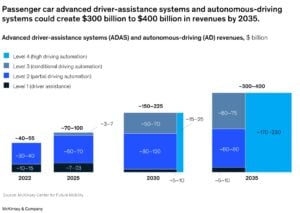
The business opportunity is enormous. According to McKinsey & Company, autonomous ride-hailing services could generate between $300 billion and $400 billion in annual revenue by 2035 in the United States alone.
Lower operating costs, combined with growing demand for convenient transportation, could make robotaxis one of the fastest-growing mobility businesses over the next decade.
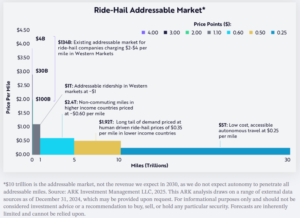
ARK Invest is even more optimistic. It estimates that autonomous ride-hailing could become a multi-trillion-dollar global market in the long term if self-driving technology reaches widespread adoption.
That potential explains why competition is growing. Traditional automakers, technology companies, ride-hailing firms, and semiconductor companies are all investing billions of dollars in autonomous driving.
Source: ARK Invest
The Race Is Bigger Than Tampa
The expansion into Tampa is only the latest chapter in a much larger competition. Tesla brings manufacturing scale, artificial intelligence expertise, and one of the world’s largest connected EV fleets.
Waymo brings years of commercial experience and a proven record of fully driverless operations. Both companies are trying to solve the same challenge, but in different ways.
There may not be a single winner.
Different cities may adopt different technologies, while several companies could succeed by serving different markets. What is already clear, however, is that autonomous electric vehicles are moving from pilot projects to commercial services.
For investors, the robotaxi race could become one of the most important growth stories of the next decade. For consumers, it could change how people think about owning a car. And for the clean energy transition, it shows that the future of transportation will depend not only on electrification, but also on AI and shared mobility working together.
Paid Advertisement – Disseminated on behalf of Alaska Energy Metals Corporation.
Alaska Energy Metals Corporation (AEMC) is moving into a more decisive phase. The company is no longer just an exploration story. Instead, it is building a case around scale, technical validation, and future economics. Yet, despite this progress, its valuation still reflects early-stage risk.
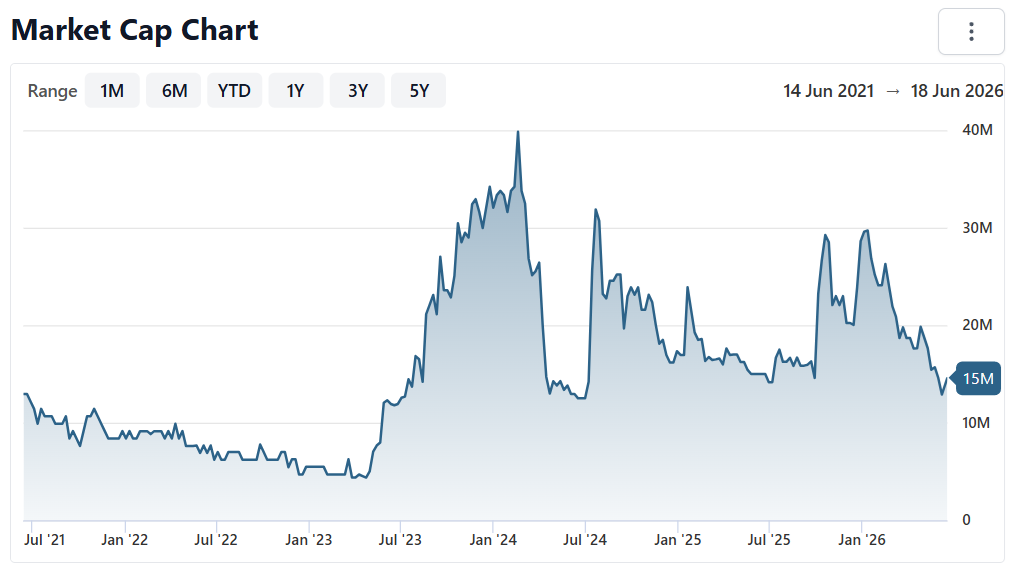
As of June 22, 2026, Alaska Energy Metals holds a market capitalization of CAD 14.56 million, with its shares trading on the TSXV at CAD 0.06. This lean valuation provides a compelling baseline entry point for investors eyeing the critical minerals sector. The current stock consolidation establishes a strong foundation just ahead of key upcoming company catalysts, positioning the company perfectly to leverage the structurally favorable and expanding long-term market for domestic energy metals.
Alaska Energy Metals Market Cap
Source: stockanalysis.com
And this growth story makes it interesting to investors seeking early-stage upside.
Scale First: A Resource That Commands Attention
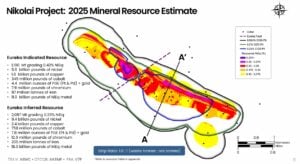
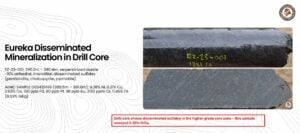
AEMC’s flagship Nikolai project hosts the Eureka deposit, which is already considered one of the largest undeveloped nickel resources in the United States. In a market increasingly shaped by supply security, scale matters more than ever.
The U.S. currently relies heavily on imports for critical minerals like nickel. At the same time, global demand is rising fast due to electric vehicles and energy storage systems. According to industry estimates, nickel demand could double by 2030, driven largely by battery applications.
Against this backdrop, a large domestic resource carries strategic weight. AEMC is not just exploring for metals – it is positioning itself within a supply chain that policymakers now consider critical.
This combination of size and location creates a strong foundation. However, investors will want more than just potential. They need proof that the asset can grow, perform, and eventually generate returns.
Angliers Could Be Alaska Energy Metals’ Next Growth Driver
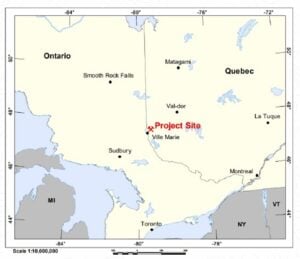
The Angliers Project is a nickel exploration property owned by Alaska Energy Metals in western Quebec, Canada. The project covers more than 26,000 hectares in the Témiscamingue region near the Ontario border. Good road access helps keep exploration costs low.
Location and Access
Source: AEMC
Promising Geology and Nickel Targets
Angliers sits within the Belleterre-Angliers Greenstone Belt, a region known for mineral deposits. The property contains ultramafic rocks, which often host nickel sulfide deposits. Its geology is similar to Australia’s Kambalda district, a major nickel-producing area.
The project targets nickel, copper, cobalt, and platinum-group metals (PGMs), all of which are important for EV batteries and clean energy technologies.
Using machine learning and historical data, the company identified four priority targets. Among them, Area 4 stands out.
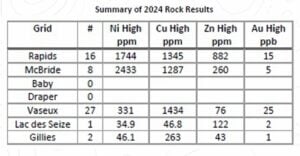
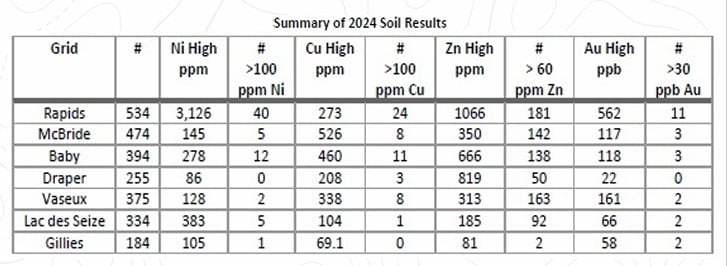
It hosts a six-kilometer nickel trend, and surface samples returned nickel grades of up to 2,290 ppm.
Meanwhile, prior exploration and government surveys have identified nickel-rich rocks and nearby nickel-copper occurrences. Notably, results from the 2024 VTEM survey revealed several undrilled areas with signs that could point to valuable mineral deposits.
Check out below:
Source: AEMC
August Drilling Could Add Value
As per company sources, AEMC plans to begin drilling at Angliers in August. These results could help confirm the project’s mineral potential.
For investors, the drill program will be an important milestone. Strong results can increase confidence in the resource, reduce uncertainty, and support future development studies. As a result, the project could attract greater market attention.
Although Angliers is still in the early exploration stage, it combines strong geology, encouraging early results, and near-term drilling catalysts. If drilling confirms significant nickel mineralization, the project could become an important source of critical minerals for the growing battery and clean energy markets.
Metallurgy: The Hidden Driver of Value
A large deposit only matters if the metal can be extracted efficiently. This is where metallurgical studies come into play.
AEMC is advancing test work to demonstrate that nickel and cobalt can be recovered at commercially viable rates. Early-stage metallurgy often determines whether a project remains theoretical or becomes investable.
If recovery rates are strong and processing methods remain practical, the implications are significant. Better metallurgy improves project economics by increasing output while controlling costs. It also makes the asset more attractive to strategic partners who prioritize operational simplicity.
In many cases, positive metallurgical results act as a turning point. They shift investor perception from “resource potential” to “recoverable value.”
One of the most important upcoming milestones is the company’s internal Preliminary Economic Assessment (PEA). This study will translate years of exploration into a financial framework.
The PEA will outline expected production levels, capital requirements, operating costs, and potential returns. For investors, this is where the story becomes tangible.
Markets tend to respond strongly to credible economic data. A solid PEA can anchor valuation and provide a clearer benchmark for comparison with peers. It also opens the door to financing discussions, offtake agreements, and strategic partnerships.
For AEMC, this step represents a shift from exploration-driven narratives to numbers-driven analysis.
Source: AEMC
Funding and Policy Support Could Accelerate Growth
Funding remains a key challenge for junior mining companies. However, AEMC operates in a sector that is increasingly supported by government policy.
The United States has prioritized domestic critical mineral supply chains. Programs under frameworks like the Defense Production Act, Project Vault, and other federal initiatives aim to reduce reliance on foreign sources.
AEMC has already engaged with these pathways. Its earlier submission for development funding – reportedly around $56 million – received a “Met” determination, indicating eligibility under government criteria. While this does not guarantee funding, it signals alignment with national priorities.
This alignment matters. Government backing, even partial, can significantly reduce financial risk. It also attracts institutional investors and strategic partners who prefer projects with policy support.
If AEMC secures funding or forms partnerships, it could change the company’s trajectory quickly. In many cases, funding announcements serve as major re-rating events.
High-Grade Potential Adds Another Layer of Upside
Beyond scale, AEMC is also targeting higher-grade mineralization within its broader resource.
High-grade zones can improve project economics by increasing the amount of metal produced per tonne of ore. This can lower processing costs and enhance early-stage cash flow.
Even limited success in identifying such zones can reshape mine planning. Companies often prioritize higher-grade areas in initial production phases to improve project returns.
For investors, this creates an additional layer of optionality. The project is not just large—it also has the potential to become more efficient and profitable over time.
Looking ahead, AEMC’s timeline includes several key inflection points:
Expected drilling results at Angliers may refine scale and confidence this year.
At the same time, the internal PEA will introduce economic clarity. Progress on permitting and infrastructure—such as access routes and site development—will signal movement toward production readiness.
Overlaying all of this is the policy environment. Any announcements related to grants, incentives, or strategic investments could amplify the company’s narrative.
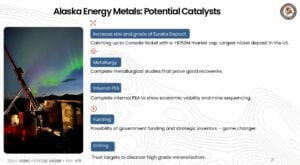
Individually, each catalyst matters. Together, they create a pathway for a broader market re-evaluation.
Source: AEMC
Valuation Gap: The Core Investment Thesis
Perhaps the most compelling part of the story lies in valuation.
Companies like Canada Nickel, which operate in a similar thematic space, command market capitalizations exceeding $150 million. In contrast, AEMC trades at a fraction of that level despite having a large and growing resource base.
This gap reflects risk, but it also highlights opportunity. As AEMC advances through key milestones, that risk profile could change. When it does, the market may begin to close the valuation gap.
Re-ratings in the mining sector often happen in stages. Early gains come from exploration success. Larger moves typically follow economic validation and funding support.
AEMC appears to be approaching this transition point.
Can Nickel Market Rebalancing Boost Alaska Energy Metals’ Growth Story?
The nickel market is finally showing signs of recovery after years of oversupply, creating a more favorable backdrop for companies like Alaska Energy Metals.
AEMC appears to be approaching this transition point.
Shrinking Indonesian Output
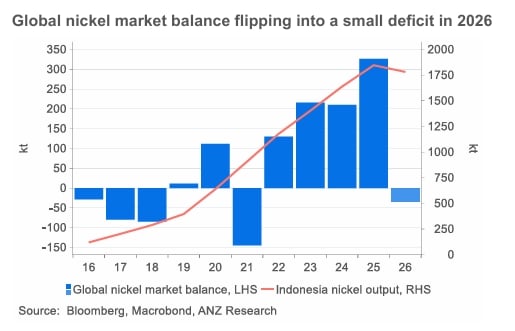
ANZ Research expects the global nickel market to shift from surplus to a small deficit by 2026. This change comes as Indonesia tightens its supply. Indonesia produces 60-70% of the world’s nickel.
They have cut mining quotas, reinstated annual production approvals, and raised costs for producers by changing ore pricing. Disruptions in sulfur and sulfuric acid supplies are also affecting Indonesian processing operations.
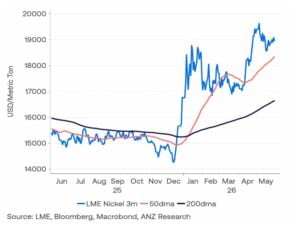
These actions could reduce Indonesia’s nickel output by over 60,000 tonnes this year. This may help rebalance the market and support a price floor above $17,000 per tonne. Nickel prices have already risen above $19,000 per tonne due to supply concerns.
This shift is timely for Alaska Energy Metals. The recent downturn saw abundant Indonesian supply lower nickel prices and dampen investor interest in exploration. A tighter market could change that.
Rising Prices Strengthen the Investment Case
Higher nickel prices often improve project economics. They also increase the value investors place on large undeveloped resources. Concerns about supply concentration in Indonesia point to the need for new nickel sources in North America.
Nickel Prices
As Alaska Energy Metals advances its Angliers Project, better market conditions could attract more interest. Resource growth, technical studies, and development milestones will be key in a market seeking new nickel supplies.
In summary, ANZ’s outlook suggests the nickel sector is entering a healthier phase. If the expected supply deficit happens, companies with large-scale nickel assets outside Indonesia may benefit the most.
AEMC is evolving from a speculative explorer into a company with defined growth drivers. Its large-scale resource, ongoing drilling, advancing metallurgy, and upcoming economic studies create a clear roadmap.
At the same time, its alignment with U.S. critical mineral policy adds a strategic dimension that many junior miners lack.
The opportunity for investors lies in execution. If AEMC delivers consistent drilling results, demonstrates strong metallurgy, and advances its economic case, the current valuation may not hold.
In that scenario, the company could shift from being overlooked to being recognized as a meaningful player in the North American nickel supply chain.
For now, the market is waiting. But with multiple catalysts lined up through 2026 and 2027, that wait may not last long.
Qualified Person. Mr. Gregory Beischer, President & CEO of Alaska Energy Metals Corporation, has reviewed and approved the technical content of this document.
Mr. Beischer is a professional geologist (American Institute of Professional Geologists #10505) and is a qualified person under NI43-101.
DISCLAIMER
New Era Publishing Inc. and/or CarbonCredits.com (“We” or “Us”) are not securities dealers or brokers, investment advisers, or financial advisers, and you should not rely on the information herein as investment advice. Alaska Energy Metals. (“Company”) made a one-time payment of $90,000 to provide marketing services for a term of three months. None of the owners, members, directors, or employees of New Era Publishing Inc. and/or CarbonCredits.com currently hold, or have any beneficial ownership in, any shares, stocks, or options of the companies mentioned.
This article is informational only and is solely for use by prospective investors in determining whether to seek additional information. It does not constitute an offer to sell or a solicitation of an offer to buy any securities. Examples that we provide of share price increases pertaining to a particular issuer from one referenced date to another represent arbitrarily chosen time periods and are no indication whatsoever of future stock prices for that issuer and are of no predictive value.
Our stock profiles are intended to highlight certain companies for your further investigation; they are not stock recommendations or an offer or sale of the referenced securities. The securities issued by the companies we profile should be considered high-risk; if you do invest despite these warnings, you may lose your entire investment. Please do your own research before investing, including reviewing the companies’ SEDAR+ and SEC filings, press releases, and risk disclosures.
It is our policy that information contained in this profile was provided by the company, extracted from SEDAR+ and SEC filings, company websites, and other publicly available sources. We believe the sources and information are accurate and reliable but we cannot guarantee them.
CAUTIONARY STATEMENT AND FORWARD-LOOKING INFORMATION
Certain statements contained in this news release may constitute “forward-looking information” within the meaning of applicable securities laws. Forward-looking information generally can be identified by words such as “anticipate,” “expect,” “estimate,” “forecast,” “plan,” and similar expressions suggesting future outcomes or events. Forward-looking information is based on current expectations of management; however, it is subject to known and unknown risks, uncertainties, and other factors that may cause actual results to differ materially from those anticipated.
These factors include, without limitation, statements relating to the Company’s exploration and development plans, the potential of its mineral projects, financing activities, regulatory approvals, market conditions, and future objectives. Forward-looking information involves numerous risks and uncertainties and actual results might differ materially from results suggested in any forward-looking information. These risks and uncertainties include, among other things, market volatility, the state of financial markets for the Company’s securities, fluctuations in commodity prices, operational challenges, and changes in business plans.
Forward-looking information is based on several key expectations and assumptions, including, without limitation, that the Company will continue with its stated business objectives and will be able to raise additional capital as required. Although management of the Company has attempted to identify important factors that could cause actual results to differ materially, there may be other factors that cause results not to be as anticipated, estimated, or intended.
There can be no assurance that such forward-looking information will prove to be accurate, as actual results and future events could differ materially. Accordingly, readers should not place undue reliance on forward-looking information. Additional information about risks and uncertainties is contained in the Company’s management’s discussion and analysis and annual information form for the year ended December 31, 2025, copies of which are available on SEDAR+ at www.sedarplus.ca.
The forward-looking information contained herein is expressly qualified in its entirety by this cautionary statement. Forward-looking information reflects management’s current beliefs and is based on information currently available to the Company. The forward-looking information is made as of the date of this news release, and the Company assumes no obligation to update or revise such information to reflect new events or circumstances except as may be required by applicable law.
Disclosure: Owners, members, directors, and employees of carboncredits.com have/may have stock or option positions in any of the companies mentioned: None.
Carboncredits.com receives compensation for this publication and has a business relationship with any company whose stock(s) is/are mentioned in this article.
Additional disclosure: This communication serves the sole purpose of adding value to the research process and is for information only. Please do your own due diligence. Every investment in securities mentioned in publications of carboncredits.com involves risks that could lead to a total loss of the invested capital.
The DOE announced on 22nd July that the United States and Saudi Arabia have signed a significant civil nuclear cooperation agreement. This deal could change Saudi Arabia’s energy future and raise questions about nuclear non-proliferation.
U.S. Energy Secretary Chris Wright and Saudi Energy Minister Prince Abdulaziz bin Salman signed the agreement, known as a 123 Agreement. This agreement, under the U.S. Atomic Energy Act of 1954, sets up a legal framework for decades of peaceful nuclear energy cooperation. It also includes a bilateral safeguards agreement governing the transfer of U.S. nuclear technology and expertise.
Countries around the world are trying to secure reliable, low-carbon electricity. This demand is driven by needs for artificial intelligence (AI), data centers, electric vehicles, and industrial growth. Nuclear energy, once in decline, is now seeing a global revival.
Why the 123 Agreement Matters
A 123 Agreement is essential for the U.S. to export nuclear reactors and related technologies. The Department of Energy calls this a foundation for a “decades-long, multi-billion-dollar partnership.” It aims to expand U.S. involvement in Saudi Arabia’s civilian nuclear program while promoting safety and non-proliferation.
Saudi Arabia states that the agreement will boost cooperation in peaceful nuclear energy use, enhance technology exchanges, and support sustainable development under international safety standards.
For the U.S., the deal opens up commercial opportunities for companies involved in advanced nuclear technologies. It also strengthens its position in the competitive global nuclear market.
Uranium Enrichment Raises Concerns
While both governments frame this as a peaceful partnership, one issue has drawn significant attention.
Reports suggest this agreement might allow Saudi Arabia to enrich uranium for civilian nuclear fuel under specific conditions. Enrichment of 3-5% uranium-235 is typical for reactors, but the same technology could be used for higher levels suitable for nuclear weapons. This possibility raises concerns among non-proliferation experts.
Past U.S. agreements have generally had stricter rules. For example, the 2009 U.S.-UAE agreement, known as the “gold standard,” required the UAE to permanently give up domestic uranium enrichment.
Critics worry that allowing enrichment could weaken U.S. non-proliferation policy. Supporters argue the agreement has safeguards and keeps Saudi Arabia aligned with U.S. technology and oversight.
The agreement still needs U.S. Congress approval before it can take effect.
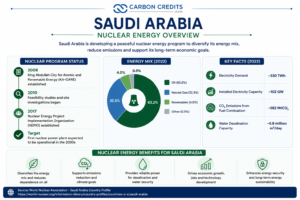
Saudi Arabia views nuclear energy as key to its Vision 2030 economic diversification plan.
The Kingdom currently relies on oil and gas for electricity. Developing nuclear power could cut domestic oil use, lower emissions, and improve energy security. It would also support electricity for industries and seawater desalination.
Over the last decade, Saudi Arabia has signed nuclear cooperation agreements with countries like France, South Korea, and China. The U.S. agreement could give American vendors access to a large nuclear market.
Nuclear Is Becoming Essential for Net Zero
This agreement comes as nuclear energy sees a global resurgence.
The World Nuclear Association reports over 440 nuclear reactors worldwide, generating nearly 400 gigawatts (GW). More than 70 reactors are under construction, with many more planned as countries seek reliable, carbon-free electricity.
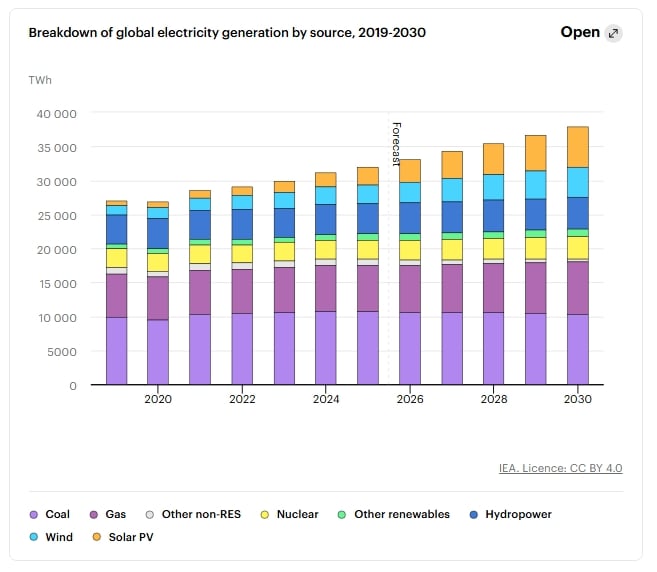
The renewed focus on nuclear energy links closely to rising electricity demand. The IEA forecasts global electricity use to grow by about 3.6% annually through 2030. This growth is driven by electrification, industrial expansion, air conditioning, electric vehicles, and the rapid rise of AI and data centers.
The IEA also predicts that renewables and nuclear will together generate about half of global electricity by 2030. This shows nuclear’s growing role in achieving net-zero emissions while ensuring grid reliability.
Source: IEA
Nuclear power currently generates about 9% of global electricity and nearly a quarter of low-carbon electricity, making it a major clean power source along with renewables.
Countries like China, India, and the U.S. are investing in both large reactors and next-generation small modular reactors (SMRs) to enhance energy security and cut emissions.
Global uranium use is expected to rise as new reactors come online and existing ones are extended. Analysts predict tighter uranium supplies in the next decade as countries prioritize energy security alongside climate goals.
Strategically, if Saudi Arabia builds commercial reactors, it will join other countries expanding nuclear power, creating more demand for uranium. For U.S. companies, this agreement offers more than just reactor exports. It can create opportunities in engineering, fuel services, maintenance, training, and advanced technologies, solidifying America’s role in a changing global market.
A Strategic Energy Partnership
The U.S.-Saudi nuclear agreement is more than a simple deal. It highlights how energy security, climate goals, and geopolitical strategy are increasingly interconnected.
Saudi Arabia sees nuclear energy as a way to diversify its electricity mix and support long-term economic growth. The United States gains stronger commercial ties while expanding its influence in one of the world’s most important energy regions.
However, the debate over uranium enrichment means the agreement is likely to face close scrutiny. As Congress reviews the deal, policymakers must balance economic opportunities with the need to prevent the spread of sensitive nuclear technologies.
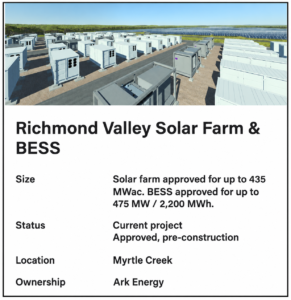
Australia is enhancing its renewable energy framework with a major project. Ark Energy has approved the final investment decision (FID) for its AUD$1.3 billion Richmond Valley Solar Farm and Battery Energy Storage System (BESS) in New South Wales (NSW). This marks a key step in the shift to a cleaner, more reliable electricity grid.
The hybrid project combines large-scale solar power with long-duration battery storage. It aims to provide renewable electricity, improve grid stability, create hundreds of jobs, and support Australia’s growing energy storage market.
Ark Energy Receives Final Investment Approval
Ark Energy, a renewable energy developer in Australia, announced that its parent company, Korea Zinc Co. Ltd., approved the financial investment decision at an Extraordinary Board Meeting in Seoul on July 21, 2026.
This approval unlocks a financing package of AUD$1.3 billion, which includes:
AUD$586 million in equity funding
AUD$716 million in debt financing
This is Ark Energy’s first build-to-own renewable energy project to secure a final investment decision, marking a major milestone for the company.
Ark Energy focuses on utility-scale solar farms, wind projects, battery storage systems, and renewable hydrogen facilities across Australia. It is a subsidiary of Korea Zinc, a leading non-ferrous metals producer with over 25 years of operation in Australia through Sun Metals Corporation.
Up to 475 MW of lithium iron phosphate (LFP) battery capacity
Moving on, construction will occur in multiple phases. The first stage, starting in 2026, will include: a 200 MWac solar farm and a 275 MW battery with 2,200 MWh of energy storage
Source: Ark Energy
This long-duration battery will store excess solar energy during the day and release it during peak demand. This improves grid reliability and allows more renewable energy to replace fossil fuels.
Four Years of Development Leads to FID
Achieving the investment decision required years of planning and regulatory efforts.
Over the past four years, Ark Energy secured planning approvals, environmental clearances, grid connection rights, and government support through New South Wales’ Long-Term Energy Service Agreement (LTESA) program.
The company received:
NSW Government planning approval in October 2025
Federal environmental approval in December 2025
Grid connection approval in June 2026
The project also gained support through the NSW Electricity Infrastructure Roadmap by securing an LTESA. This provides long-term revenue certainty, reducing investment risk. It is also included on the Australian Government’s National Renewable Energy Priority List.
Ark Energy’s CEO, Michael Choi, stated that the investment decision shows Korea Zinc’s confidence in both the project and the company’s long-term growth strategy. He added that this approval is strong support from the parent company, moving Richmond Valley into its next financing and construction phase.
Financial close is expected in September 2026, with construction starting in October. Commercial operations are targeted for January 2029.
Beyond Clean Power: Economic and Environmental Benefits
The Richmond Valley project is set to deliver substantial economic benefits to the region.
During peak construction, it can support over 850 direct and indirect jobs. Local spending may reach around AUD$180 million, benefiting regional businesses, contractors, and suppliers.
The project also includes long-term community investment. Ark Energy will provide annual community funding of AUD$850 for every installed megawatt of solar capacity throughout the project’s life.
Environmental commitments are also essential. Plans include a new 30-meter-wide biodiversity corridor and planting native vegetation to enhance wildlife connectivity between the nearby Ellangowan and Bungawalbin State Forests.
The Richmond Valley project highlights the growing role of battery storage in modern electricity systems. Solar and wind generation is rising, but their output can vary with weather. Battery systems help balance supply and demand by storing renewable energy when production is high and releasing it during peak demand.
Lithium iron phosphate (LFP) batteries are the preferred choice for many utility-scale storage projects due to their long life, safety, and competitive costs.
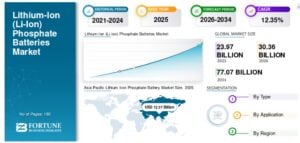
According to Fortune Business Insights, the global lithium iron phosphate (LFP) battery market was valued at $23.97 billion in 2025.
The firm expects the market to grow to $30.36 billion in 2026 and reach $77.07 billion by 2034, expanding at a compound annual growth rate (CAGR) of 12.35%.
Asia-Pacific accounted for over half of the global market in 2025, driven by strong manufacturing capacity and rising regional demand.
Australia Emerges as a Battery Storage Leader
Australia is quickly becoming a leading market for battery storage outside China and the United States.
The International Energy Agency (IEA) reported that China made up around 60% of global battery deployments in 2025, followed by the United States and Europe. However, battery installations are rapidly increasing in Australia and parts of the Middle East. These regions need storage to enhance electricity security and integrate more renewable energy.
Australia’s battery market reflects this trend.
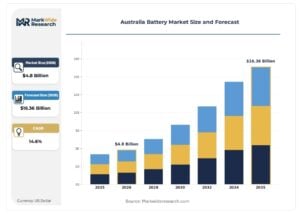
Industry forecasts predict the Australian battery market will grow from $4.8 billion in 2026 to $16.36 billion by 2035, with a CAGR of 14.6%.
Government support has accelerated investment. Programs from the Clean Energy Finance Corporation (CEFC) and the Australian Renewable Energy Agency (ARENA) are lowering financing costs for large battery projects, making them more appealing.
States like New South Wales and Victoria are expanding grid-scale battery procurement. Also, Queensland is seeing strong demand for co-located solar and storage projects that capture higher electricity prices during evening peak demand.
Large-scale batteries are becoming vital because they enhance flexibility, reduce renewable power curtailment, and help maintain reliable electricity supplies during peak demand.
Richmond Valley will combine a 500 MW solar farm with a large long-duration battery system. This will provide clean electricity and support the grid. The project will create local jobs, enhance the environment, and invest in the community long-term.
As battery costs go down and renewable energy increases, hybrid projects that mix solar power with energy storage will be key. They will help Australia create a lower-carbon and more resilient electricity system.
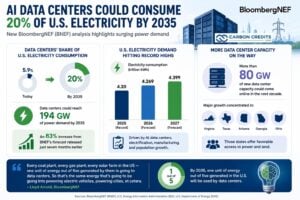
Artificial intelligence (AI) is creating a new challenge for the United States power sector. A new BloombergNEF (BNEF) analysis shows just how fast that demand is growing. It projects that data centers could consume about 20% of all U.S. electricity by 2035, up from 5.9% today.
The power demand of these facilities could reach 194 gigawatts (GW), an 83% increase from BNEF’s forecast released just seven months earlier. Lloyd Arnold, one of the report authors at BNEF, remarked:
“Every coal plant, every gas plant, every solar farm in the US — one unit of energy out of five generated by them is going to data centers. So that’s the same energy that’s going to be going into powering electric vehicles, powering cities, et cetera.”
The forecast signals more than an AI boom. It highlights a major change in the U.S. electricity system. Utilities, tech firms, and policymakers should now rethink how America generates, delivers, and decarbonizes power.
America’s Power Demand Is Surging Again
The U.S. power market has entered a new growth cycle. For nearly two decades, electricity demand in the country changed very little as homes, businesses, and appliances became more energy efficient. That trend has now ended.
AI, data centers, electric vehicles, new factories, and the wider shift toward electrification are pushing electricity demand to record highs.
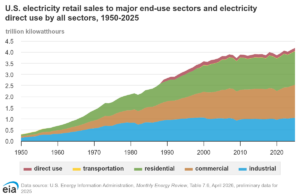
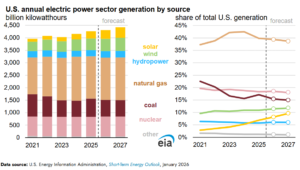
According to the U.S. Energy Information Administration (EIA), electricity consumption reached a record 4.20 trillion kilowatt-hours (kWh) in 2025. The agency forecasts another record of 4,269 billion kWh in 2026, followed by 4,399 billion kWh in 2027. The increase comes from expanding AI data centers, electrification, manufacturing, and population growth.
That marks a sharp change from the previous two decades, when electricity demand remained largely flat despite economic growth.
AI is becoming one of the biggest drivers behind this turnaround. Training large language models and running AI applications require thousands of advanced chips operating around the clock. Those servers also need large cooling systems that consume significant amounts of electricity.
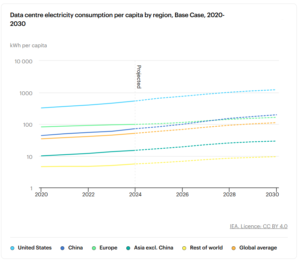
The International Energy Agency (IEA) says the United States leads the world in data center electricity use per person. In 2024, it is around 540 kilowatt-hours per capita. By the end of this decade, that figure could exceed 1,200 kWh per person, highlighting how quickly AI is reshaping electricity demand.
Clean Energy Must Keep Pace
Meeting that demand is not simply about generating more electricity. The United States is also working to reduce emissions from its power sector.
According to the EIA, renewable energy continues to expand rapidly while coal generation keeps falling. Renewables like wind, solar, and hydropower are providing more U.S. electricity. This growth is backed by record investments in battery storage and improved transmission.
Natural gas remains the country’s largest electricity source. Meanwhile, nuclear power continues to provide the biggest source of emissions-free baseload generation.
The challenge is that AI is arriving just as the country is trying to modernize its electricity system. The U.S. Department of Energy (DOE) says no single technology can meet future demand alone. Instead, the country will need a balanced mix of:
Moreover, major investments in transmission infrastructure are crucial to maintain reliability while lowering emissions. That shift is already underway.
Utilities and Tech Giants Are Racing to Secure Power
Microsoft has signed agreements to support new nuclear generation and geothermal projects. Google, Amazon, and Meta are investing billions in renewable energy, battery storage, and advanced nuclear technologies to power future AI operations.
According to BloombergNEF, corporate clean energy procurement reached record levels globally in 2024 (62 GW) before declining to 55.9 GW in 2025, with technology companies remaining among the largest buyers. Many tech firms are also looking beyond solar and wind.
Microsoft recently signed an agreement supporting the restart of the Three Mile Island nuclear plant. Amazon and Google have also invested in advanced nuclear and small modular reactor (SMR) projects. These investments reflect a growing need for around-the-clock electricity that can complement intermittent renewable energy.
These investments reflect a growing reality: electricity is becoming a competitive advantage in the AI race.
The scale of future electricity demand is already changing how utilities and technology companies plan for growth.
According to the U.S. DOE, more than 80 gigawatts (GW) of new data center capacity could come online in the next decade. Many of these facilities are being built in states such as Virginia, Texas, Arizona, Georgia, and Ohio, where access to power and land remains relatively favorable.
Utilities are responding by accelerating investments in generation, transmission, and grid upgrades.
But The Grid May Be AI’s Biggest Bottleneck
Generating electricity is only part of the challenge. The United States must also deliver that power to where it is needed.
According to the DOE, transmission expansion has not kept pace with rising demand. Long permitting timelines and aging infrastructure continue to slow the connection of new power projects. Meanwhile, large data centers often require power levels comparable to those of small cities.
The IEA estimates that global investment in electricity grids must roughly double by 2030, US$600–750 billion, to support growing electrification and clean energy deployment. Electricity must move efficiently from generators to consumers, including the rapidly growing network of AI data centers.
A Test for America’s Climate Goals
The rapid growth of AI also raises an important climate question: If new electricity comes mainly from fossil fuels, emissions could rise even as other sectors become cleaner.
However, if the United States expands clean power fast enough, AI could accelerate investment in renewable energy, nuclear power, batteries, and grid modernization.
The IEA estimates that data centers worldwide will account for nearly one-tenth of all electricity demand growth through 2030. For the U.S., that share could more than double by the same period, according to S&P Global. But AI can also help cut emissions by:
Improving power grid operations,
Increasing industrial efficiency,
Forecasting renewable energy output, and
Optimizing transport systems.
That means the success of America’s clean energy shift relies on two things: how much electricity AI uses and how that electricity is made.
The country’s next challenge is not only generating more power but also building enough clean, reliable, and affordable electricity to support both economic growth and long-term climate goals.
AI Could Become Clean Energy’s Biggest Growth Driver
The growing electricity needs of AI present both risks and opportunities.
If utilities rely heavily on fossil fuels to meet new demand, emissions could rise. But if investment flows into renewables, nuclear power, battery storage, and grid modernization, AI could help drive the next phase of clean energy growth.
As data centers move toward consuming one-fifth of U.S. electricity by 2035, the country’s ability to build clean, reliable power at scale will play a major role in determining both its AI leadership and its long-term climate progress.
The carbon market has reached another major milestone. Carbon Trade Exchange (CTX) has now traded more than 1 billion tonnes of carbon dioxide equivalent (CO₂e) since launching in 2008. The company has spent nearly two decades building one of the world’s largest electronic marketplaces for carbon credits and other environmental products.
That number is significant. One carbon credit equals one tonne of CO₂e that has been avoided, reduced, or removed from the atmosphere. Together, those trades have helped direct funding to climate projects such as renewable energy, forest protection, methane capture, and clean cooking programs.
The milestone also comes as global demand for carbon credits continues to change. Buyers are looking for higher-quality credits. Governments are expanding carbon pricing. More companies are using carbon markets as part of their net-zero strategies.
How CTX Became a Global Carbon Trading Hub
CTX was founded in Australia in 2008 to make carbon trading more open and accessible.
Today, the company operates an online exchange where businesses, governments, brokers, and project developers can buy and sell environmental products. These include voluntary carbon credits, compliance credits, renewable energy certificates, and biodiversity credits.
According to CTX, its marketplace now serves participants in more than 100 countries, has 2,000+ climate projects listed, and has 50+ project countries. Over the years, it has become one of the world’s largest spot exchanges for environmental commodities.
Unlike private carbon deals, exchange trading offers several advantages:
Better access for smaller buyers and project developers.
These features help improve transparency while making it easier for climate projects to find investors.
CTX says that trading one billion tonnes shows how carbon markets have grown. They have moved from a niche industry to a vital source of climate finance. Wayne Sharpe, CEO & Founder of CTX, remarked:
“There is no Planet B – we need to save this one. This milestone represents businesses choosing to put capital behind climate action. The work now is to make access to quality carbon credits more transparent, practical and scalable worldwide.”
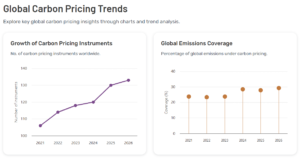
Together, they cover about 29% of global greenhouse gas emissions.
Source: World Bank
Carbon pricing also generated a record $107 billion in government revenue during 2024. More than half of that money was used to support climate and nature projects, according to the World Bank.
Voluntary carbon markets (VCMs) are much smaller than compliance markets, but they continue to play an important role. Many projects supported by voluntary carbon finance are located in developing countries.
Carbon credit sales help fund activities such as protecting forests, restoring mangroves, building renewable energy projects, capturing methane from landfills, and distributing cleaner cookstoves. These projects reduce emissions while creating jobs and supporting local communities.
The OECD says global climate finance hit $136.7 billion in 2024. It is more than the developed countries’ goal of $100 billion a year for developing nations.
Even so, the United Nations says developing countries will need trillions of dollars annually this decade to meet climate and development goals. Private investment, including carbon markets, will play an important role in closing that gap.
Why Transparent Carbon Exchanges Matter More Today
As carbon markets grow, exchanges are becoming more important. Many carbon credits are still bought through private negotiations, but:
Organized exchanges offer greater transparency by publishing market prices and using standard trading rules. That helps buyers compare credits more easily.
It also gives project developers access to more potential investors.
More trading also improves market liquidity. Buyers can find credits more easily, while project developers gain greater confidence that they can sell future credits.
This matters because demand is shifting toward higher-quality carbon credits. Companies increasingly want credits that meet stronger environmental standards and provide clear climate benefits.
CTX’s one-billion-tonne milestone shows how much carbon markets have grown over the past 18 years. More importantly, it shows that exchanges are becoming key financial infrastructure for the global carbon market, helping move private capital toward projects that reduce emissions and support the transition to a lower-carbon economy.
Digital Exchanges Can Help Scale Climate Finance
The need for climate finance continues to grow.
According to the United Nations Framework Convention on Climate Change (UNFCCC), developing countries will require $5.1 trillion to $6.8 trillion by 2030 to deliver their national climate plans. Public funding alone will not be enough to meet that need.
Private capital will play a much bigger role.
Carbon markets are one way to direct that investment toward projects that reduce emissions or remove carbon from the atmosphere. These include reforestation, mangrove restoration, biochar, methane capture, and carbon removal technologies.
Digital exchanges help this process by making carbon trading faster, more transparent, and easier to access. Instead of relying on private negotiations, buyers can compare prices, review available credits, and complete transactions through a centralized marketplace.
CTX is not alone. Other exchanges are also growing rapidly as demand for environmental commodities increases.
Xpansiv’s CBL, the world’s largest spot marketplace for environmental commodities, has facilitated trading of more than 330 million carbon credits since 2020. The platform also serves more than 1,500 active participants across carbon, renewable energy, clean fuels, and water markets. It has over $2 billion in cumulative notional trading value.
Meanwhile, the Intercontinental Exchange (ICE) reported another record year in 2025. More than 20.9 million environmental futures and options contracts traded on ICE. This is a 4% increase from the previous record.
ICE has now recorded the equivalent of more than $1 trillion in annual notional environmental trading for five consecutive years. This suggests a growing role of carbon markets in global finance.
As more countries build carbon markets under Article 6 of the Paris Agreement, exchanges can connect buyers and sellers internationally. This connection helps improve transparency and price discovery.
One Billion Tonnes, and the Beginning of a Bigger Market
CTX’s one-billion-tonne milestone is about more than trading volume. It shows how much carbon markets have evolved over the past 18 years. What started as a niche market has become an important tool for mobilizing private climate finance.
For CTX, reaching one billion tonnes traded confirms its role as one of the industry’s longest-running carbon exchanges. For the wider market, it signals that carbon trading is becoming more organized, more transparent, and increasingly focused on quality.
As countries and companies work toward net-zero emissions, carbon exchanges like CTX are likely to play an even larger role. By connecting global buyers with climate projects, they help move private capital where it is needed most—supporting emissions reductions while expanding access to climate finance around the world.
The voluntary carbon market (VCM) shows mixed signals in 2026. Fewer carbon credits are being retired and issued compared to last year. However, buyers are paying more for the credits they choose. Higher-quality projects are earning larger price premiums, indicating a more selective market.
A new study from MIT Sloan School of Management highlights a key challenge. It reveals that carbon credit prices are influenced more by who buys the credits than by their actual climate impact.
Sylvera’s Carbon Market Data Snapshot Q2 2026 and the MIT study reflect a market improving in quality but needing better transparency and efficient pricing.
Carbon Credit Volumes Drop While Market Value Grows
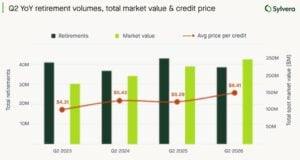
According to Sylvera, carbon credit retirements reached 38.55 million in Q2 2026, a 10% drop from 42.9 million in the same quarter of 2025. In the first half of the year, retirements totaled 89.27 million credits, down 9% from 98.27 million in H1 2025.
Despite fewer credits, market value increased. The total value of retired credits reached $247 million in Q2 2026, up from $227 million a year earlier. For the first half of 2026, retirement value rose to $548 million, compared to $524.2 million in H1 2025.
This trend shows buyers are purchasing fewer credits but paying higher prices.
The average retirement price climbed to $6.41 per credit in Q2 2026, up from $5.29 in Q2 2025. Over the first six months, the average price rose to $6.13, compared to $5.33 a year earlier.
Higher-Quality Credits Continue to Command Premium Prices
Sylvera’s data indicates buyers value independently rated, high-quality carbon credits more highly.
Credits rated BBB or higher made up only 27% of rated retirement volume in Q2 2026 but generated 51% of the rated market value. This shows buyers are willing to pay more for projects with stronger quality ratings.
The premium is especially evident in Afforestation, Reforestation, and Revegetation (ARR) projects. BBB+ rated ARR credits averaged $28.55 during H1 2026, compared to $9.12 for lower-rated ARR credits.
Improved Forest Management (IFM)
IFM projects also experienced a growing quality gap. BBB+ IFM credits rose from $16.34 to $18.65, while lower-rated IFM credits fell from $15.02 to $13.06, widening the premium to $5.59.
REDD+ Projects
They also followed a similar trend. Higher-rated REDD+ credits climbed 71% year over year to $8.40, while lower-rated credits dropped 26% to $1.82. The price difference between high- and low-quality REDD+ projects expanded from $2.47 to $6.58, showing buyers are becoming more selective.
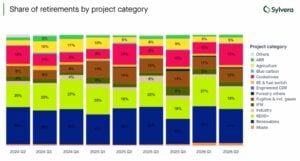
The quality of newly issued credits is also improving. Investment-grade issuances rose from 13- 16% between 2022 and 2024 to 25% in 2025 and 29% in the first half of the year. Meanwhile, the share of the lowest-rated C and D credits dropped sharply from 43% to 22%, indicating stronger project development.
While Sylvera’s report suggests quality is gaining importance, the MIT study argues that buyer identity is the main driver of carbon credit prices.
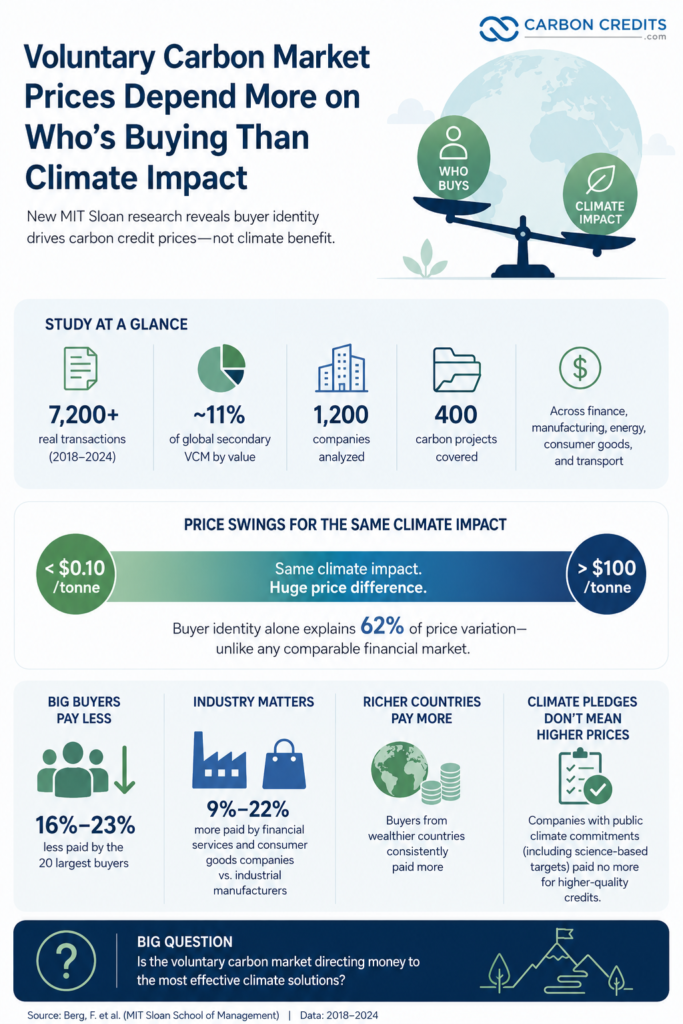
Researchers analyzed over 7,200 voluntary carbon market transactions from 2018 to 2024, covering about 11% of the global secondary market by value. The study included purchases by 1,200 companies across 400 carbon projects.
Instead of acting like a typical commodity market, where similar products have similar prices, the researchers found huge price differences. Credits with the same emissions reductions sold for a few cents to over $100 per tonne.
The study found that buyer identity explained 62% of the price variation.
The top 20 buyers paid 16% to 23% less than others, while financial services and consumer goods companies typically paid 9% to 22% more than industrial manufacturers. Companies in wealthier countries also consistently paid higher prices.
Surprisingly, companies with public climate commitments—including science-based targets—did not always pay more for higher-quality credits.
The researchers also noted that some lower-rated project types, like forest protection and cookstove projects, often sold for 2 or 4x more than industrial efficiency and waste management projects, which many consider more reliable for emissions reductions.
MIT researchers argue that the market needs better transparency, including public price benchmarks, to ensure funding goes to projects that provide the greatest climate benefits.
The summary of the MIT study is in the infographic below:
Source: MIT
MSCI Carbon Credit Prices Analysis
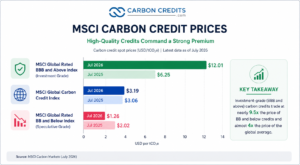
MSCI’s latest carbon market analysis shows the voluntary carbon market (VCM) is becoming increasingly selective. While overall carbon credit prices remain relatively low, buyers are paying significantly more for credits with stronger quality ratings, creating a widening gap between premium and lower-quality projects.
Key Takeaways
MSCI Global Carbon Credit Price Index averaged $3.5/tCO₂e in 2025, reflecting continued weakness in the broader market.
In contrast, the MSCI Rated BBB and Above Index rose from $5.6 to $6.8/tCO₂e, an increase of more than 20%, showing buyers are increasingly willing to pay for higher-integrity credits.
The price gap between high-quality (BBB+) and lower-quality (BB and below) credits widened significantly. The average spread increased from $2.9 in 2024 to $5.1 in 2025 and exceeded $7/tCO₂e by the end of the year—equivalent to roughly a 360% premium for higher-quality credits.
Rewarding Quality Over Volume
MSCI expects this quality-focused trend to continue as voluntary carbon markets mature. The firm projects the market could grow from roughly $1.4 billion today to $5–20 billion by 2030, and eventually reach $60–270 billion by 2050, if demand for credible, high-integrity carbon credits continues to strengthen.
The Bottom Line: Sylvera, MSCI, and MIT Offer Three Views of Carbon Credit Pricing
Insights from Sylvera, MSCI, and MIT show both progress and challenges in today’s voluntary carbon market. Sylvera’s data reveals that buyers are investing more in higher-quality carbon credits. Investment-grade projects are increasing their market share, even with lower trading volumes.
MSCI’s carbon credit indexes support this, showing that BBB-rated and higher credits trade at a notable premium compared to lower-rated ones. This indicates a growing demand for projects with better environmental integrity.
However, MIT’s research reveals the market is not fully efficient. The study found that carbon credit prices depend more on buyer traits, like company size, industry, and location, rather than just climate performance. So, while quality is becoming important for pricing, it isn’t the main factor yet.
These findings show the voluntary carbon market is improving, but there’s more to do. To align prices with real climate impact, we should increase price transparency. We also need to expand independent quality ratings and use standardized pricing benchmarks. This approach would build market confidence and direct more funds to projects with the greatest environmental benefits.
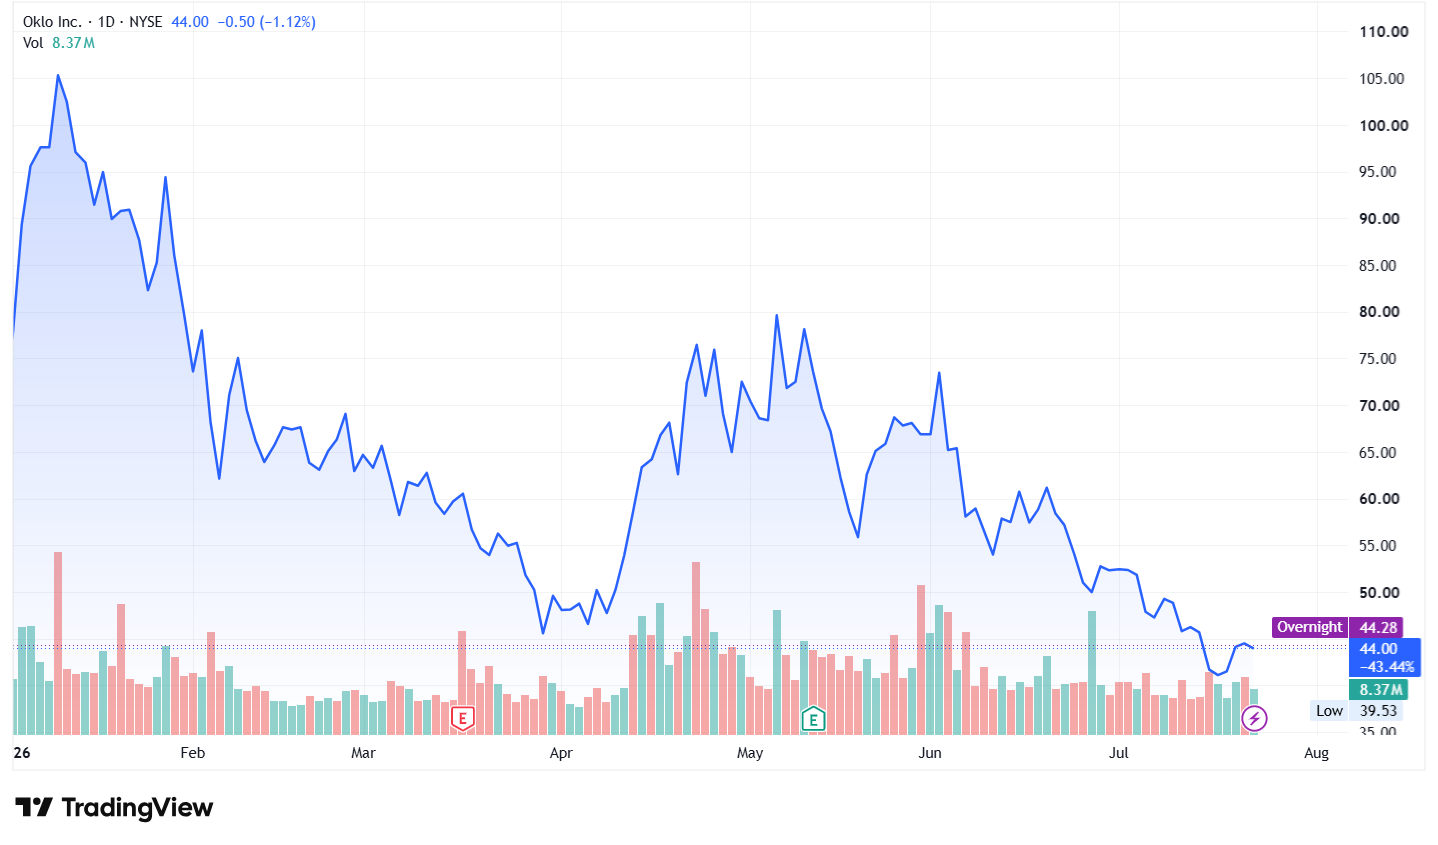
The race to power artificial intelligence (AI) has entered a new stage, and nuclear energy is moving to the center of it. Shares of Oklo (NYSE: OKLO) rose sharply. This came after news that the company was chosen for a $200 million U.S. government program.
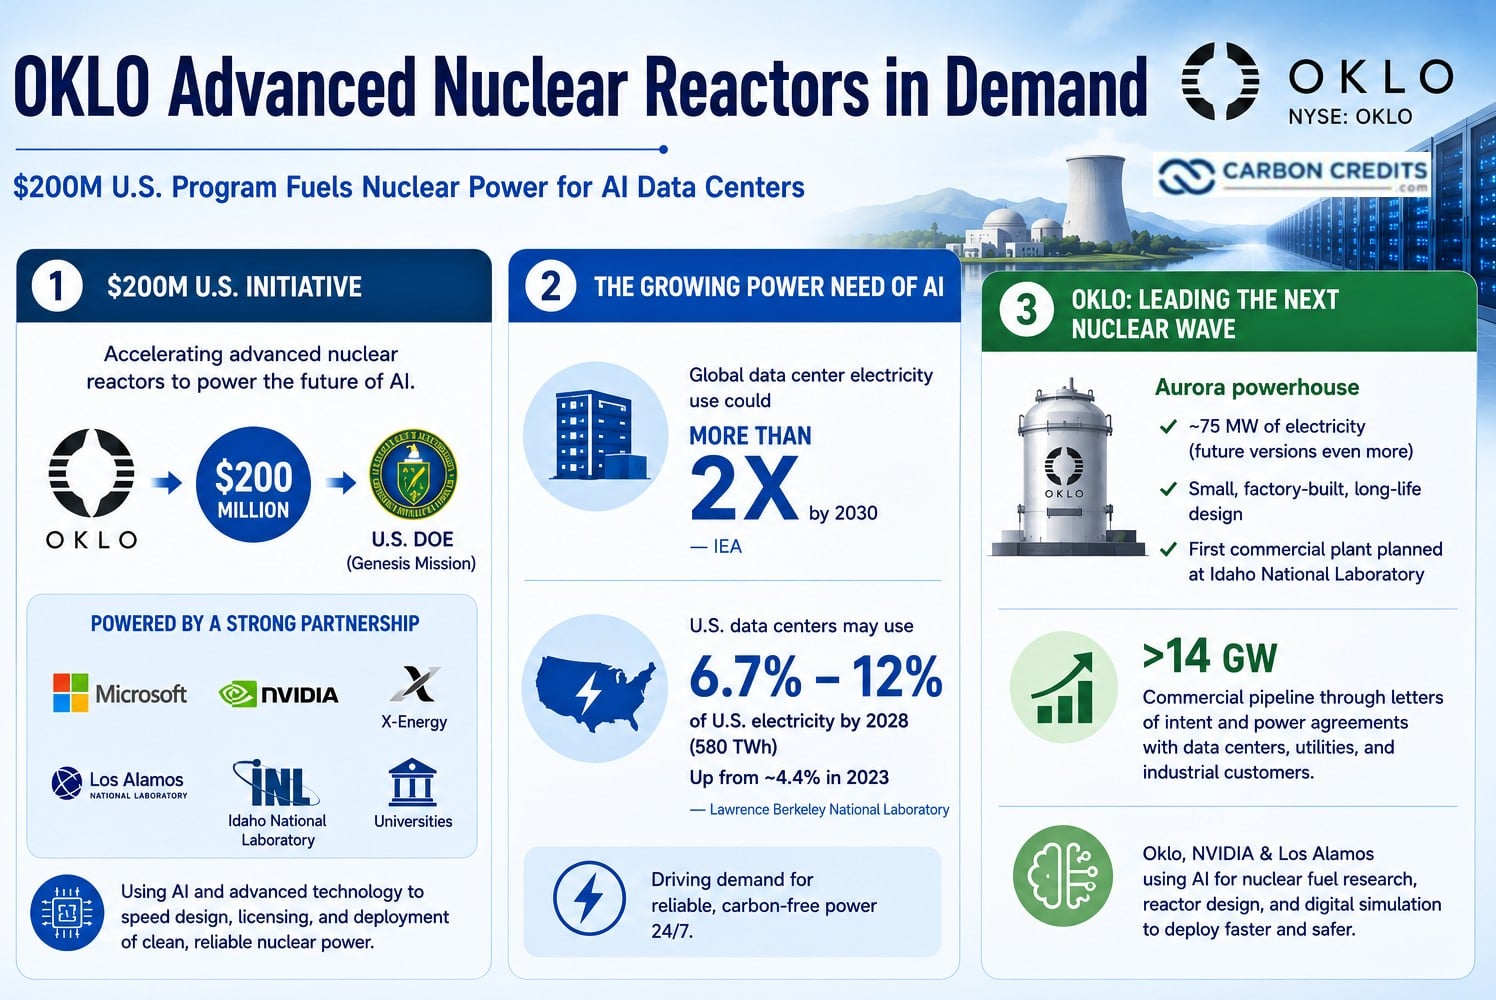
The initiative aims to speed up the use of advanced nuclear reactors for AI data centers. The program unites Oklo, Microsoft, Nvidia, X-Energy, national labs, universities, and the U.S. Department of Energy (DOE). Their goal is to create cleaner and more reliable power for future AI infrastructure.
Why Washington Is Investing $200M in AI-Powered Nuclear
The news highlights a growing shift in the energy sector. AI companies are no longer looking only for faster chips. They also need reliable electricity that runs around the clock without producing large amounts of carbon emissions.
For Oklo, the announcement strengthens its position as one of the leading developers of advanced nuclear reactors. For investors, it signals growing government and industry support for small modular reactors (SMRs), which many see as a key source of clean, reliable power.
The new initiative is part of the Trump administration’s broader effort to strengthen U.S. leadership in both AI and advanced energy.
The $200 million public-private program will help speed the design, licensing, construction, and operation of advanced nuclear reactors using AI tools. It also supports research on nuclear fuels and digital technologies that can lower costs and shorten development times.
The program brings together over $200 million from the industry and federal support that comes through the DOE’s Genesis Mission. This national effort uses AI to speed up scientific discovery and develop critical infrastructure.
Microsoft and Nvidia excel in cloud computing and AI. Oklo and X-energy add cutting-edge nuclear technologies. Los Alamos National Laboratory and Idaho National Laboratory are among several DOE national laboratories joining in.
The partnership sends a clear message: advanced nuclear energy is becoming part of America’s long-term AI strategy.
One Growing Challenge: Finding Enough Clean Power
The move also reflects a broader energy trend. According to the International Energy Agency (IEA), electricity use from data centers worldwide could more than double by 2030 as AI adoption accelerates.
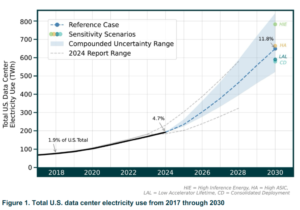
The Lawrence Berkeley National Laboratory estimates that U.S. data centers may use 6.7% to 12% of the country’s electricity by 2028, hitting 580 TWh. This is a big jump from around 4.4% in 2023. Those forecasts are driving interest in reliable, carbon-free power sources that can operate day and night.
Source: Lawrence Berkeley National Laboratory
Inside Oklo’s Fast-Rising Nuclear Growth Story
Oklo has become one of the best-known companies developing advanced nuclear reactors in the United States. Its flagship Aurora powerhouse produces around 75 megawatts of electricity. Future versions may generate even more.
Unlike traditional nuclear plants, Aurora is much smaller, factory-built, and designed to operate for years before needing refueling. The company plans to build its first commercial plant at the Idaho National Laboratory, one of the country’s leading nuclear research sites.
Demand is also growing.
Oklo reports it has created a commercial pipeline exceeding 14 gigawatts (GW). This was achieved through letters of intent and power agreements with various customers. These customers include data centers, utilities, and industrial companies.
That represents a sharp increase from just a few years ago and suggests that interest in advanced nuclear power continues to grow.
The company has also expanded its work with Nvidia beyond electricity supply. Earlier this year, Oklo, Nvidia, and Los Alamos National Laboratory announced a collaboration to use AI for nuclear fuel research, reactor design, and digital simulation. The goal is to speed reactor deployment while improving safety and efficiency.
Together, these developments show that Oklo is becoming more than a nuclear startup. It is increasingly at the crossroads of clean energy and artificial intelligence. These two sectors are set to drive economic growth in the next decade.
The program reflects a broader trend. AI is pushing electricity demand sharply higher as companies build larger data centers. The IEA projects global data center electricity use will more than double by 2030. That is increasing interest in reliable, carbon-free power sources such as advanced nuclear, alongside renewables and battery storage.
Small Nuclear Reactors Are Gaining the Spotlight
Oklo is part of a growing industry focused on small modular reactors, or SMRs.
Unlike traditional nuclear plants, SMRs are smaller, faster to build, and designed to be manufactured in factories before being assembled on site. Supporters say this can lower construction costs and shorten project timelines.
Governments around the world are increasing support for the technology.
The International Atomic Energy Agency (IAEA) states that nuclear power supplies around 9% of the world’s electricity. It also accounts for nearly one-quarter of global low-carbon electricity.
More than 440 nuclear reactors operate worldwide, while more than 60 reactors are under construction.
The International Energy Agency reports that nuclear generation grew by 1.2% year-on-year. The active reactors produce about 10% of the world’s electricity.
The agency further predicts that global nuclear electricity generation will hit a new record soon. This growth comes as countries focus on energy security and clean power.
Right now, countries are building a massive pipeline of new plants. Over 70 gigawatts of new nuclear capacity is currently under construction. This is the highest level of development the world has seen in 40 years.
SMRs could play an important role because they can be built near industrial sites, factories, and large data centers that require reliable electricity. And tech giants will greatly benefit from this.
Big Tech’s Nuclear Bet Gets Bigger
For Microsoft, the partnership fits into a much bigger climate strategy.
The company has pledged to become carbon negative by 2030 and remove all the carbon it has emitted since it was founded by 2050. But reaching those goals is becoming harder as AI data centers use more electricity.
That is why Microsoft is investing in several types of clean energy, including wind, solar, battery storage, geothermal, and nuclear power.
Last year, Microsoft signed a landmark agreement with Constellation Energy to help restart Unit 1 of the Three Mile Island nuclear plant in Pennsylvania. The plant is expected to supply carbon-free electricity to Microsoft’s operations for 20 years once it returns to service.
Joining the new AI-nuclear initiative adds another piece to that strategy. It allows Microsoft to help develop the next generation of advanced reactors that could power future AI data centers.
Although the company does not operate data centers itself, its AI chips power many of the world’s largest AI systems. As demand for those chips grows, so does the need for reliable electricity.
Nvidia has committed to achieving 100% renewable electricity for its offices and data centers by the end of fiscal 2025 where possible. The company also aims to reach net-zero greenhouse gas emissions across its value chain by 2050.
Supporting advanced nuclear research gives Nvidia another way to help build the clean energy infrastructure that future AI systems will need.
Could Nuclear Become AI’s Most Valuable Power Source?
The latest announcement is about more than one company’s share price. Governments, tech companies, and energy developers are teaming up. They aim to tackle one of AI’s biggest challenges: securing enough clean electricity.
For years, most clean energy investment focused on solar panels, wind farms, and electric vehicles. Those technologies remain essential. However, the rapid growth of AI is creating demand for reliable, 24-hour electricity that renewable energy alone cannot always provide.
Advanced nuclear is now entering that conversation.
If companies like Oklo can successfully bring small modular reactors to market, they could help power the next generation of AI while supporting global climate goals. That would make nuclear energy not only a source of clean electricity but also a key part of the digital economy’s future.
To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behavior or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.
Functional
Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes.The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.