Microsoft and Aker Solutions Join Forces to Accelerate Carbon Removal Projects

Aker Solutions and Microsoft (MSFT) are joining forces to help move carbon capture and storage (CCS) and carbon dioxide removal (CDR) projects from early-stage concepts to construction and operations.

The companies signed an agreement at ONS 2026 in Stavanger, Norway, as the carbon management industry faces a familiar challenge: plenty of proposed projects, but not enough financing, firm buyers and execution-ready developments.

Aker Solutions Targets Faster, More Bankable CCS and CDR Projects

Under the agreement, Aker Solutions will work with project developers, industrial emitters, transport and storage companies, governments and other stakeholders. The goal is to improve project economics, reduce execution risks and make projects more attractive to investors.

The partnership also aims to help projects reach final investment decisions (FID) faster.

Microsoft brings digital technology, artificial intelligence (AI), data, carbon markets and monitoring, reporting and verification (MRV) expertise. Aker Solutions brings techno-economic advisory services and engineering, procurement and construction capabilities.

Together, the companies intend to create a more integrated path from feasibility studies to project delivery and operations.

Kjetel Digre, CEO at Aker Solutions, said,

โ€œMany carbon capture and removal projects face similar challenges as they move from concept to reality. As the market matures, success will depend on strong collaboration across the value chain. Joining forces with Microsoft, we aim to help project developers navigate complexity, strengthen business cases, and support the next wave of CCS and CDR projects.โ€ย 

Microsoftโ€™s Carbon Challenge Is Growing

The partnership comes as Microsoft faces a tougher emissions challenge from the rapid expansion of artificial intelligence and cloud infrastructure.

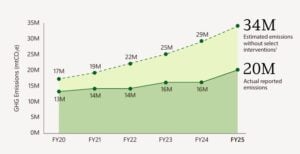
  • Microsoftโ€™s latest Environmental Sustainability Report shows that its total Scope 1, 2 and 3 emissions rose 25% year over year in fiscal 2025.
  • The company reported about 20.3 million metric tons of CO2 equivalent in FY25, up from roughly 16.2 million tons in FY24.

The increase was primarily due to the expansion of its data center infrastructure and a change in its use of non-additional, unbundled renewable energy certificates.

Scope 3 emissions remain the largest part of Microsoftโ€™s footprint. At the same time, Scope 2 emissions increased sharply as the company expanded its electricity demand. Scope 2 accounted for about 13% of total emissions in FY25, compared with nearly 2% in the previous year.
microsoft emissions
Source: Microsoft

Microsoft said it matched 100% of its annual global electricity consumption with renewable energy in FY25. However, the company is increasingly focused on adding new carbon-free electricity to grids rather than relying on unbundled certificates alone.

The rise in emissions makes carbon removal an increasingly important part of Microsoftโ€™s strategy. Itย has committed to becoming carbon negative by 2030 and removing the equivalent of all its historical emissions by 2050. But the company has also stressed that removals cannot replace direct emissions reductions.

That puts pressure on Microsoft to expand both its clean-energy investments and its carbon removal portfolio.

Darryl Willis, corporate vice president, energy and resources at Microsoft, said:

โ€œMicrosoft supports collaborations that look holistically across the entire value chain, connecting physical infrastructure with trusted data, AI and digital MRV to help projects reduce risk, and move from ambition to execution. We are working with Aker Solutions to bring these complementary capabilities together and help accelerate credible CCS and carbon removal projects globally.”

Microsoft Has Become the Biggest CDR Buyer

Microsoft has played an outsized role in building the market for durable carbon removal.

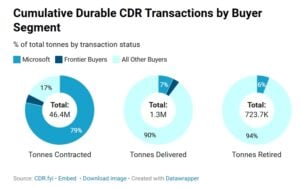
CDR.fyi estimates that Microsoft had contracted 36.4 million tonnes of durable carbon removal by April 2026. That represented 78.5% of all disclosed durable CDR tonnes contracted at the time.

Frontier-linked buyers accounted for another 4%, while all other buyers represented 17.5%.
microsoft CDR

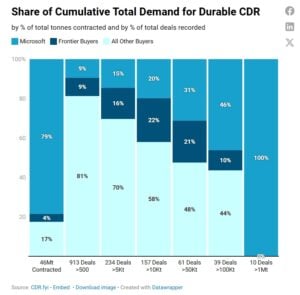
Its position is even more significant when looking at large-scale deals. CDR.fyi says Microsoft is the only buyer to have signed disclosed purchase agreements exceeding 1 million tonnes.

Its portfolio is also heavily concentrated in bioenergy with carbon capture and storage, or BECCS, which represented about 76% of its disclosed durable CDR volume as of April.

Microsoft continued buying carbon removal in 2026. In the first quarter, it signed a 1-million-tonne agreement that helped push total durable CDR contracting to 2.3 million tonnes, the largest first quarter on record. Microsoft accounted for about 43% of Q1 contracted volume.

The company has also expanded into other removal approaches. In January 2026, Microsoft signed a 12-year agreement to purchase 2.85 million soil carbon removal credits from Indigo Ag. The deal was described as the largest voluntary soil carbon transaction to date.

CDR Supply Still Faces a Financing Gap

The growing number of purchases does not mean enough carbon removal capacity is ready to meet future demand.

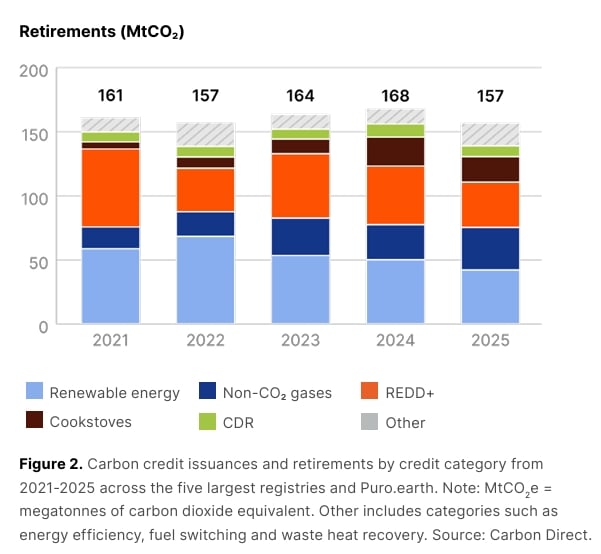
Carbon Directโ€™s 2026 State of the Voluntary Carbon Market report analyzed 288 million tonnes of credits and found that more than 80% of high-durability CDR supply planned for 2030 is at risk of not being realized without additional offtake commitments and financing.

The report also identified an estimated $18 billion financing gap across CDR pathways.
microsoft cdr
Source: Carbon Direct

That creates a major bottleneck for technologies such as direct air capture, BECCS and other forms of durable carbon removal. Developers need long-term buyers before they can secure financing, while buyers need confidence that projects will actually be built and deliver verified removals.

This is where the Microsoft-Aker Solutions agreement could become important.

From Carbon Credits to Bankable Projects

Aker Solutions will help developers improve project maturity and bankability before construction begins.

That could include assessing project economics, engineering requirements, infrastructure needs and execution risks. Microsoft can complement this work with digital tools, AI, data systems, carbon-market knowledge and MRV capabilities.

The companies will also work across the wider CCS and CDR value chain.

That matters because carbon management projects are not standalone facilities. A CCS project needs an emitter, capture technology, transportation infrastructure, a storage site and a system for measuring and verifying the captured CO2.

CDR projects face similar challenges. Developers need reliable technology, financing, monitoring systems, storage or durable carbon sinks, and buyers willing to sign long-term contracts.

Aker Solutions and Microsoft aim to connect these pieces earlier in the development process.

If projects move successfully through FID, the companies plan to provide integrated engineering and execution support through construction and into operations.

A Critical Test for the CDR Market

The partnership arrives at a turning point for carbon removal.

CDR demand is growing, but the market remains heavily concentrated among a small number of buyers. CDR.fyi found that buyers other than Microsoft and Frontier accounted for 90% of delivered and 94% of retired durable CDR tonnes, despite representing a much smaller share of contracted volume.
demand of CDR credits

That highlights the marketโ€™s central challenge: large future purchase agreements do not automatically translate into delivered removals. And for the wider industry, the partnership reflects a shift in focus from announcing carbon removal projects to making them financeable, buildable and operational.

The next phase of the CDR market will depend less on ambitious targets and more on whether developers can secure capital, buyers and infrastructure to deliver real, verified removals at scale.

Nvidia Earns $96B in Q2 FY2027 as AI Demand Surges, But Emissions Keep Rising

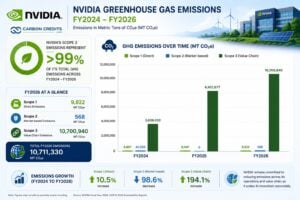
Nvidia’s latest results show that the artificial intelligence boom is still accelerating, with revenue more than doubling from a year earlier. But the company’s rapid growth also highlights a growing climate challenge: Nvidia’s Scope 3 emissions reached 10.7 million metric tons of CO2e in fiscal 2026, driven largely by its expanding supply chain.

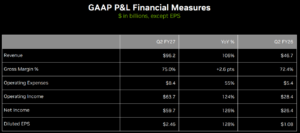
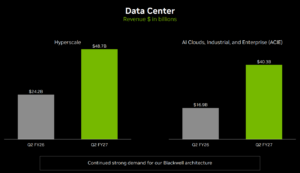
Nvidia reported its second-quarter fiscal 2027 results on August 26, 2026, with revenue of $96.2 billion, up 106% year-on-year. Data Center revenue reached $89.0 billion, up 117%, as demand for AI computing continued to drive sales.

Jensen Huang, founder and CEO of Nvidia, remarked during the earnings call:

“AI has reached its inflection point. Itโ€™s doing useful work. Its tokens are productive and profitable. Now, compute is revenue. And demand is accelerating. This time last year, one lab alone was driving the buildout; today, we have a golden age of new AI labs and startups, multiple frontier labs scaling in parallel, a thriving open-model ecosystem and physical AI coming online โ€” with strong momentum across the U.S. and around the world. The AI infrastructure buildout is at full steam. Vera Rubin, now in full production, was built to power exactly this moment.”
The results show the strength of Nvidia’s business. Yet, they also raise a bigger question for the clean energy market: can AI infrastructure grow this quickly while companies reduce the emissions tied to that growth?

Nvidia’s AI Engine Blasts Past $96 Billion

Nvidia’s Q2 revenue jumped to $96.221 billion, compared with $46.743 billion a year earlier. Net income rose 126% to $59.688 billion, while diluted earnings per share climbed 128% to $2.46.

The Data Center business remains the main growth engine. Revenue from the segment reached $89.0 billion, up 117% from a year earlier and 18% from the previous quarter. That means Data Center sales accounted for about 92% of Nvidia’s total quarterly revenue.

Nvidia data center revenue Q2 2027
Source: Nvidia

Nvidia also maintained a 75% gross margin in the quarter. The tech giant expects the momentum to continue. It forecasts $108 billion in revenue for the third quarter, plus or minus 2%. Nvidia does not include any Data Center computing revenue from China in that forecast.

The company also returned about $26 billion to shareholders through share buybacks and dividends during the quarter.

Nvidia financial results q2 2027
Source: Nvidia

The AI Boom Is Also an Energy Boom

Nvidia’s earnings matter to the carbon market because its chips sit at the center of the expanding AI infrastructure system. AI data centers need large amounts of electricity to run and cool servers. Nvidia’s own latest sustainability report acknowledges that AI demand will increase energy use and says energy is the foundation of the AI infrastructure stack.

The company is trying to address part of this problem through more efficient computing.

The chipmaker says its Vera Rubin NVL72 platform can deliver up to 10 times the energy efficiency of its previous Blackwell architecture. Its Vera CPU can also run up to 50% faster with twice the energy efficiency of traditional CPU infrastructure.

Nvidia also says its Groq 3 LPX combined with Vera Rubin NVL72 can deliver up to 35 times more inference performance per watt than the Blackwell GB200 NVL72 for trillion-parameter models.

These improvements matter because higher performance per watt can reduce the electricity needed for a given amount of computing. But efficiency gains do not automatically reduce total emissions if companies deploy far more AI computing.

Scope 3 Emissions Hit 10.7 Million Tons

This is where Nvidia’s latest sustainability data becomes important. Its FY2026 Sustainability Report shows Scope 3 emissions of 10,700,940 metric tons of CO2e, up from 6,912,577 tons in FY2025 and 3,638,432 tons in FY2024.

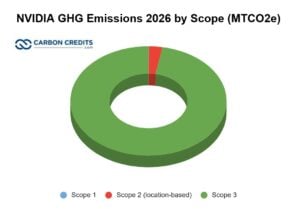
That means Scope 3 emissions increased about 55% in one year and almost threefold in two years. Scope 3 covers indirect emissions across a company’s value chain. For Nvidia, the largest source comes from purchased goods and services.

Category 1 emissions reached 9,301,735 metric tons of CO2e in FY2026. That represented about 87% of Nvidia’s reported Scope 3 emissions.

NVIDIA GHG emissions 2026

The increase reflects the scale of Nvidia’s hardware business and the emissions linked to manufacturing the components and systems needed for its products.

This is important because Nvidia operates mainly as a fabless semiconductor company. Much of the physical manufacturing takes place through suppliers rather than inside Nvidia-owned factories.

Direct Emissions Are Much Smaller

Nvidia’s direct operational emissions remain far below its Scope 3 footprint, as shown in the chart above.

In FY2026, the company reported 9,822 metric tons of Scope 1 emissions. Its market-based Scope 2 emissions were 568 tons. Together, Scope 1 and market-based Scope 2 emissions totaled 10,390 tons. Nvidia also reported 308,891 tons of location-based Scope 2 emissions.

The difference comes from the way the company accounts for purchased electricity. Nvidia says it matched 100% of its global electricity use with clean electricity in FY2026 through sources including on-site solar, long-term power purchase agreements, renewable electricity tariffs and energy attribute certificates.

That helped reduce its market-based Scope 2 figure. But it does not remove the much larger emissions connected to its supply chain. The data shows why Nvidia’s biggest climate challenge sits outside its own offices and facilities.

Nvidia Sets 2030 Climate Targets as Emissions Keep Climbing

The world’s most valuable company does have science-based emissions targets.

From a FY2023 base year, the company aims to cut absolute Scope 1 and Scope 2 market-based emissions by 50% by FY2030. It also aims to reduce Scope 3 emissions intensity from the use of sold GPU products by 75% per petaFLOP by FY2030. The Science Based Targets initiative has validated both targets.

The Scope 3 goal is an intensity target, not an absolute emissions target. This distinction matters.

Nvidia can reduce emissions per unit of computing performance while its total emissions continue to rise if it sells enough additional GPUs and systems. The FY2026 figures show why that issue is important.

Nvidia’s Scope 3 emissions rose from 6.91 million tons to 10.70 million tons in one year, even as the company continued to improve the efficiency of its products.

Nvidia GHG emissions 2026 by scope
Data source: Nvidia

Nvidia Pushes Clean Power and Grid Flexibility

Nvidia says it has matched 100% of its global electricity use with clean electricity for two consecutive years. However, its biggest emissions source remains its supply chain, so the company is using more supplier-specific data to better track Scope 3 emissions and identify areas for cuts.

Nvidia is collaborating with Emerald AI, the Electric Power Research Institute (EPRI), and energy firms. They aim to create AI data centers that adjust power use according to grid conditions.

The company says this approach could help unlock up to 100 gigawatts of U.S. power capacity by using existing infrastructure more efficiently. Nvidia is also exploring onsite power generation and energy storage to help data centers connect faster and reduce grid pressure.

For the clean energy market, the strategy shows how AI companies are moving beyond clean electricity purchases toward more flexible power systems.

Nvidia (NVDA) Stock Jumps After Earnings, but Expectations Remain High

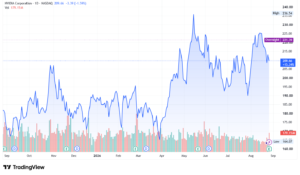
Nvidia stock initially dipped after its earnings release before jumping 4.2% in heavy after-hours trading, with more than 50 million shares changing hands, according to LSEG data. Investors responded to Nvidia’s stronger-than-expected results and its forecast for 70% revenue growth in fiscal 2028.

The company also expects $108 billion in third-quarter revenue, while Data Center revenue rose 117% to $89 billion in the latest quarter.

Nvidia NVDA stock

Despite the rebound, Nvidia stock remain up only more than 12% this year, compared with a more than 60% gain for the Philadelphia Semiconductor Index. Reuters noted that investor expectations have become so high that simply beating forecasts may no longer be enough to drive the stock higher.

AI’s Carbon Challenge Is Moving Upstream

Nvidia’s latest earnings make the AI boom look stronger than ever. But its latest sustainability report tells another part of the story.

The company is improving energy efficiency, matching its electricity use with clean power, and working on grid-friendly AI infrastructure. It also has science-based 2030 emissions targets. Still, the rapid rise in Scope 3 emissions shows the scale of the challenge.

Nvidia’s next sustainability test will not simply be whether each new GPU uses less energy. It will be whether the company can make its fast-growing AI supply chain cleaner as demand for computing continues to surge.

Japan Advances Maritime CCS Hub to Ship 3.43M Tons of CO2 a Year

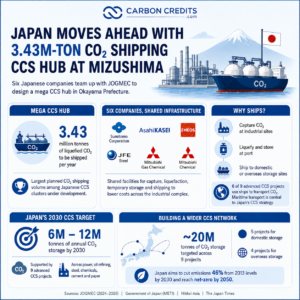
Japan is moving ahead with plans for a major carbon capture and storage (CCS) hub at the Mizushima Industrial Complex in Okayama Prefecture. Six Japanese companies have signed a contract with the Japan Organization for Metals and Energy Security (JOGMEC) to design facilities that will capture, liquefy, temporarily store and ship carbon dioxide. The planned hub could ship about 3.43 million tonnes of liquefied CO2 a year.

The project is part of Japan’s wider push to build a commercial CCS industry by 2030. It also shows how Japan plans to use ships to connect industrial areas with underground CO2 storage sites.

Six Companies Team Up on a Mega CCS Hub

The project brings together Sumitomo Corporation, Asahi Kasei, ENEOS, JFE Steel, Mitsubishi Gas Chemical and Mitsubishi Chemical. They will design facilities for CO2 capture, liquefaction, temporary storage and shipping.

The project covers the Mizushima industrial area in Kurashiki City, a major industrial center in western Japan. The companies plan to share infrastructure across the industrial area instead of having each company build its own system.

That could help lower costs and make CCS more practical for several industrial facilities at once.

The planned hub would ship about 3.43 million tonnes of liquefied CO2 per year when shipping starts. The companies say this would be the largest planned CO2 shipping volume among Japanese CCS clusters currently under development.

Why Japan Is Putting CO2 on Ships

CCS involves more than capturing carbon.

Companies must move the captured CO2 to a site where they can store it underground. But many of Japan’s large industrial centers do not sit close to suitable storage sites. Ships can solve part of this problem.

Captured CO2 can be turned into a liquid, stored at a port, and loaded onto specialized ships. The ships can then move the CO2 to domestic or overseas storage sites.

JOGMEC selected nine advanced CCS projects in 2024. Together, they aim to store about 20 million tonnes of CO2 a year. Six of the nine projects use ships to transport liquefied CO2, while three use pipelines. This makes maritime transport a key part of Japan’s CCS strategy.

Japan Targets 6M to 12M Tons of CO2 Storage by 2030

Japan wants to start commercial CCS operations by 2030.

JOGMEC’s nine advanced projects support a government target of 6 million to 12 million tonnes of annual CO2 storage by 2030. The nine projects cover industries such as power generation, oil refining, steel, chemicals, cement and paper.

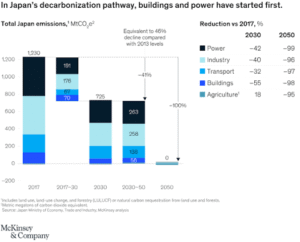
Japan also aims to reach net-zero greenhouse gas emissions by 2050. It has set a 2030 target of cutting emissions by 46% from fiscal 2013 levels. McKinsey & Company shows below how the country could reach its climate goals.ย 

Japan carbon neutrality 2050 McKinsey
Source: McKinsey & Company

The Mizushima project could make a large contribution to the country’s CCS infrastructure if it reaches its planned shipping volume.

However, 3.43 million tonnes refers to CO2 shipped, not CO2 permanently stored. The climate benefit will depend on how much captured CO2 ultimately reaches approved storage sites and remains underground.

Shared Infrastructure Could Bring CCS Costs Down

Cost is one of the biggest challenges for maritime CCS. Ship-based systems require extra equipment to liquefy and temporarily store CO2 before shipping. JOGMEC says these steps can add costs compared with pipeline systems. Ship transport can also be more expensive.

Japan is therefore trying to build larger hubs.

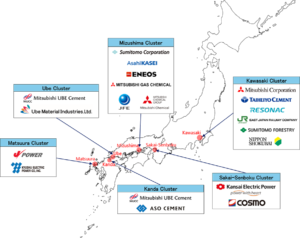
In June 2026, JOGMEC selected six emitter clusters to study shared facilities for CO2 capture, liquefaction, temporary storage and shipping. The goal is to collect CO2 from several nearby facilities and share infrastructure.

JOGMEC six selected CCS hub clusters
Source: JOGMEC

Mizushima follows this same approach. A shared hub could spread the cost of expensive equipment across several companies. It could also make it easier to add new emitters later.

Mizushima Aims Hard-to-Cut Emissions

The Mizushima industrial area includes companies from sectors such as chemicals, steel and energy. These industries face a difficult emissions challenge. Some emissions come directly from industrial processes and cannot be eliminated simply by switching to renewable electricity.

CCS can provide another tool.

Companies can capture CO2 at industrial facilities, transport it and store it underground. This could help reduce emissions from operations that are difficult to fully electrify.

The six companies say the project will also support the green transformation of the Mizushima industrial complex. For Japan, that links CCS with both climate policy and industrial competitiveness.

Japan Is Building a Wider CCS Network

Mizushima is only one part of Japan’s developing CCS system. JOGMEC began supporting advanced CCS projects in 2023. The first seven projects aimed to store about 13 million tonnes of CO2 per year.

The agency later expanded the program to nine projects with a combined target of about 20 million tonnes a year. The projects cover several regions and industries.

Some plan to store CO2 in Japan. Others will ship captured CO2 to storage sites elsewhere in the Asia-Pacific region. Four of the nine 2024 projects target overseas storage.

This approach could eventually create a regional CO2 transport network linking Japan with storage resources in other countries.

Japan Has Already Tested CCS

Japan has experience with both carbon storage and CO2 transport. At the Tomakomai CCS demonstration project in Hokkaido, the country injected about 300,000 tonnes of CO2 underground between 2016 and 2019. The government continues to monitor the stored CO2.

Japan has also tested technologies for transporting liquefied CO2 by ship. These projects have helped the nation develop experience with the equipment and processes needed for a larger CCS industry. The government is now moving from demonstration projects toward commercial-scale systems.

Japan CCS hub carbon shipping

A New Legal Framework Supports CCSย 

Japan also created a legal framework for the industry. In May 2024, the country’s parliament passed the Act on Carbon Dioxide Storage Business. The law created a licensing system for companies that want to operate CO2 storage businesses. That framework is important because CCS projects require large investments and long operating periods.

Companies need clear rules covering storage rights, monitoring, safety, and responsibility for stored CO2. Government support also remains important as companies develop the first commercial projects.

JOGMEC is supporting the full CCS chain, from capture and transport to underground storage.

CCS Must Move Beyond Capture

The Mizushima project still has several steps to complete. The current agreement covers design work, so the 3.43-million-tonne figure is a planned shipping volume rather than operating capacity. The companies still need to complete engineering work, develop the business model and make further investment decisions.

The storage side is also critical. Capturing millions of tonnes of CO2 has little climate value if companies cannot transport and permanently store the gas safely.

Japan’s long-term goal shows the scale of the challenge. JOGMEC estimates that Japan could need 120 million to 240 million tonnes of annual CO2 storage by 2050 to support its net-zero goal. That means Mizushima would be an important step, but only one part of a much larger system.

Mizushima Could Set the Course for Asian CCS

Japan’s planned 3.43-million-tonne annual CO2 shipping hub shows how quickly the country is trying to build a commercial CCS network. The project combines several large industrial companies, shared infrastructure and maritime CO2 transport. That model could help lower costs and connect industrial regions with storage sites that are far away.

The key test will be whether Japan can move from design to investment and then to reliable, large-scale CO2 storage. And if it succeeds, Mizushima could become an important model for hub-based maritime CCS in Japan and across Asia.

For now, the project is another sign that Japan sees carbon capture and storage as a major tool for cutting emissions from heavy industry while building a new carbon-management infrastructure.

Carbon Credit Prices Explained: What Determines the Value of a Carbon Credit?

Carbon credits do not have one fixed price. Their value can range from less than $1 to hundreds or even thousands of dollars per metric ton of carbon dioxide equivalent (tCOโ‚‚e), depending on the type of credit, its quality, and market demand.

This wide price range can make carbon credits difficult for newcomers to understand. Why does one credit cost a few dollars while another can cost hundreds?

The answer is that carbon credits are not interchangeable products. They can represent different types of emissions reductions or carbon removals, come from different locations and years, and have different levels of environmental integrity.

Understanding these factors is important for companies, investors, and other buyers looking to purchase carbon credits.

What Is the Average Price of a Carbon Credit?

There is no single global carbon credit price because the voluntary carbon market (VCM) includes credits from thousands of different projects.

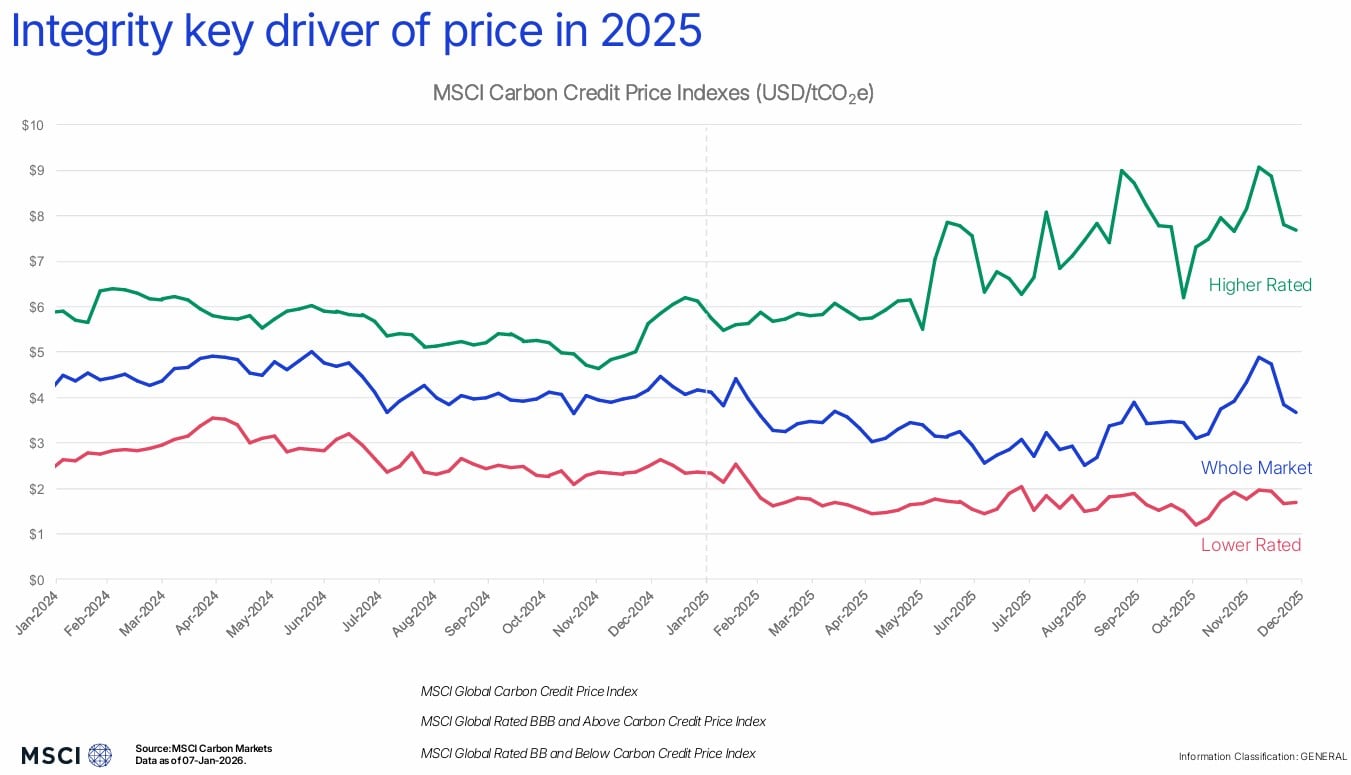
In 2025, the MSCI Global Carbon Credit Price Index averaged $3.50 per tCOโ‚‚e, down from $4.30 in 2024. However, credits rated BBB or above averaged $6.80/tCOโ‚‚e, showing the premium buyers can pay for credits with stronger quality characteristics.

Prices can vary even more by project type. MSCI’s data showed many voluntary carbon credits trading from below $1/tCOโ‚‚e to nearly $50/tCOโ‚‚e. Engineered carbon removal credits can cost far more, with some selling for more than $1,000/tCOโ‚‚e.

carbon credit price 2025 MSCI

These figures show why an “average carbon credit price” can be misleading. The type and quality of the credit matter greatly.

What Determines the Price of a Carbon Credit?

Several factors influence how much buyers are willing to pay.

Project Type

The type of project generating the credit is one of the biggest pricing factors.

Some projects focus on avoiding or reducing emissions. Examples include methane capture, renewable energy, and clean-cooking projects. Others remove carbon dioxide from the atmosphere, such as reforestation, biochar, direct air capture, and other carbon removal technologies.

Removal credits can command higher prices because they physically remove carbon from the atmosphere. Some removal methods also require significant investment, energy, or specialized technology.

Credit Quality

Quality is becoming one of the most important factors in carbon credit pricing.

Buyers increasingly assess whether a project creates a real, measurable, and additional climate benefit. They may also consider how long the carbon remains stored, how accurately the emissions reduction or removal is measured, and whether the project creates risks of leakage or double counting.

Credits that perform better on these factors can command a premium.

Market data found that the price gap between higher- and lower-rated carbon credits widened significantly in 2025. This suggests that buyers are becoming less willing to treat all carbon credits as equivalent.

Why Do Carbon Removal Credits Cost More?

Carbon removal is particularly important to the future of the carbon market, but removing carbon from the atmosphere is often more expensive than avoiding or reducing emissions.

For example, a forest restoration project may remove carbon through natural growth, while direct air capture uses specialized equipment to extract carbon dioxide directly from the atmosphere.

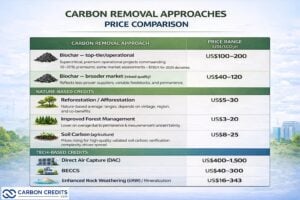
These approaches have very different costs and technical requirements. As a result, some engineered carbon removal credits can cost more than $1,000/tCOโ‚‚e, compared with less than $1 for some conventional carbon credits.

biochar price omparison carbon removal methods

However, higher prices do not automatically mean a project is better. Buyers still need to examine the project’s methodology, measurement, permanence, verification, and other quality factors.

Does Location Affect Carbon Credit Prices?

Yes. The location of a project can influence its price because different regions have different project costs, risks, regulations, supply levels, and buyer preferences.

Projects can also generate additional environmental or social benefits. For example, a forest project may protect biodiversity and support local communities in addition to reducing or removing emissions.

These benefits can make certain credits more attractive to buyers, particularly companies looking to support broader environmental or social goals.

However, a credit should not command a higher price simply because it comes from a particular country or region. Buyers should assess the actual quality and impact of the project.

Does the Vintage of a Credit Matter?

The vintage refers to the year in which the underlying emissions reduction or carbon removal occurred.

Vintage can affect price because buyers may prefer newer credits or credits from particular years. Older credits may trade at discounts depending on the project type, market demand, and buyer requirements.

However, newer does not automatically mean better. The quality of the underlying project remains more important than the vintage alone.

How Does Supply and Demand Affect Carbon Prices?

Like other markets, carbon credit prices are influenced by supply and demand.

If many buyers want a limited supply of credits from a particular project type, prices can rise. Conversely, credits with abundant supply and limited demand may trade at lower prices.

Demand is also becoming more selective. Rather than simply looking for the cheapest available credit, some companies are seeking higher-quality credits and durable carbon removals.

This is contributing to a more differentiated market in which credits with different characteristics can command very different prices.

Are VCM Prices Higher or Lower Than Compliance Carbon Prices?

Voluntary carbon credit prices should not be directly compared with compliance market prices because the two markets use different instruments and operate under different rules.

The VCM is largely driven by voluntary corporate and institutional demand. Compliance markets, such as emissions trading systems (ETSs), create demand through legal emissions obligations.

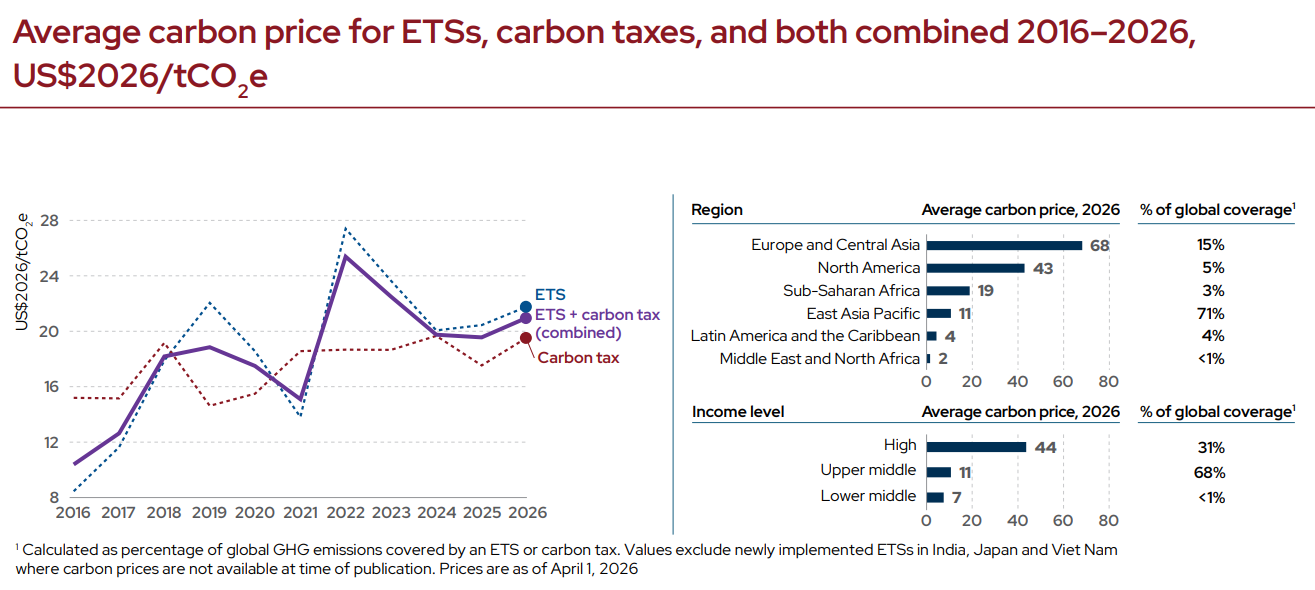
The World Bank reported an average direct carbon price of nearly $21/tCOโ‚‚e in 2026 across implemented carbon taxes and ETSs. But individual compliance markets can be significantly higher or lower than this average.

carbon price average ets carbon tax World Bank 2026
Source: World Bank

This means it is incorrect to say that compliance carbon is always more expensive than voluntary carbon, or vice versa.

Does a Higher Price Mean a Better Carbon Credit?

Not necessarily.

Price can provide a useful signal, but it should not be the only factor buyers consider. A more expensive credit may represent a high-quality removal project, but buyers still need to examine the evidence behind its claimed climate benefit.

Before purchasing a credit, buyers should consider:

  • Additionality: Would the emissions reduction or removal have happened without carbon-credit revenue?
  • Permanence: How long will the carbon remain stored?
  • Measurement: How accurately are emissions reductions or removals quantified?
  • Verification: Has an independent body assessed the project’s reported results?
  • Leakage: Could emissions simply shift elsewhere because of the project?
  • Double counting: Is the same emissions reduction or removal being claimed more than once?

These factors help buyers understand what they are actually purchasing rather than relying on price alone.

The Bottom Line

Carbon credit prices vary because carbon credits are not all the same. Project type, quality, location, vintage, supply and demand, and the durability of carbon removal can all affect value.

In 2025, the average price across the MSCI Global Carbon Credit Price Index was $3.50/tCOโ‚‚e, but higher-quality credits averaged $6.80, while some engineered carbon removal credits cost more than $1,000/tCOโ‚‚e.

As the carbon market develops, buyers are increasingly looking beyond the cheapest available credits. Quality, transparency, and the strength of the underlying climate benefit are becoming increasingly important factors in determining what a carbon credit is worth.

Microsoft Taps Qcells to Power AI Growth as Data Centers Stress the Grid

Microsoft is expanding its partnership with solar manufacturer and clean energy company Qcells to explore a new way of powering the growing (artificial intelligence) AI infrastructure boom.

The companies announced that they will work on ways to pair Microsoft’s expanding data center footprint with new energy generation and flexible energy resources. The goal is to add power capacity alongside AI infrastructure instead of simply placing more demand on existing local grids.

Andy Park, CEO of Qcells, remarked:

“Our relationship with Microsoft began with American-made solar manufacturing and construction. Now weโ€™re exploring how we can build the energy capacity needed for AI while creating lasting value for the communities that share the grid.”ย 

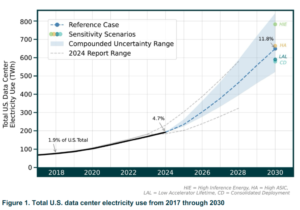
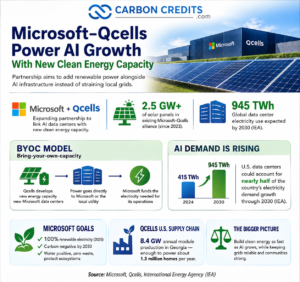
The partnership comes as AI pushes electricity demand higher. The International Energy Agency (IEA) expects global data center electricity use to more than double to about 945 terawatt-hours (TWh) by 2030. AI is the main driver of that growth.

For Microsoft, the deal also fits into a wider effort to expand AI while meeting its climate goals.

BYOC: New Power Model Could Take Pressure Off Local Grids

Microsoft and Qcells teamed up in 2023. Their alliance includes over 2.5 gigawatts (GW) of solar panels. It also covers engineering, procurement, and construction services for solar projects.

The new agreement goes beyond solar equipment. The companies now want to explore a model that links AI data centers with new energy capacity.

Instead of simply adding AI-related electricity demand to the grid, the companies want to develop new generation and flexible energy resources at the same time. They say this could support grid reliability while allowing AI infrastructure to grow.

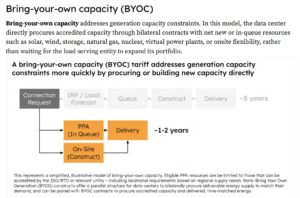
The companies are exploring a โ€œbring-your-own-capacityโ€ (BYOC) model. Under the plan, Qcells could develop and build new energy capacity near Microsoft’s data centers. The power could go directly to Microsoft or to the local utility, with Microsoft funding the electricity needed for its operations.

The partnership will also explore virtual power plants (VPPs) that connect thousands of residential and commercial batteries into one flexible grid resource. The batteries could support the grid during peak demand while customers continue using them normally at other times. Participants could also receive lower electricity bills or payments for supporting the grid.

bring your own capacity BYOC model
Source: Brancucci, C. et al., Flexible Data Centers: A Faster, More Affordable Path to Power, 2025.

Qcells plans to prioritize income-qualified households in the VPP program. The companies say this could help spread some of the economic benefits of AI infrastructure to the communities where data centers are built.

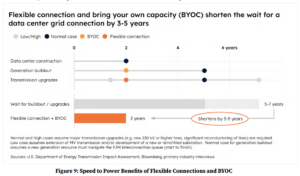
Qcells says the approach could include new generation and flexible energy resources that support Microsoft’s growing data center network across the United States. Moreover, paired with flexible connection, the BYOC model could significantly help reduce the time needed for power generation.

BYOC and flexible connection model
Source: Brancucci, C. et al., Flexible Data Centers: A Faster, More Affordable Path to Power, 2025.

The companies have not announced a specific amount of new generation capacity under the expanded agreement. This is an important point. The partnership is currently an effort to develop and test a new approach. It is not yet a commitment to build a specific number of gigawatts of new power plants.

AI Is Creating a New Power Challenge

The need for new energy is growing with AI. The IEA estimates that data centers consumed about 415 TWh of electricity in 2024. Under its base case, that figure could reach around 945 TWh by 2030. Data center electricity use would then account for just under 3% of global electricity consumption.

The United States faces an even larger challenge. The IEA expects U.S. data centers to account for nearly half of the country’s electricity demand growth through 2030.

US data centers electricity use 2030

AI data centers can also have very high power needs at individual sites. This can put pressure on transmission networks, local distribution systems and available generation.

That makes Microsoft’s new approach important. The companies want to see data center growth as a chance to add energy resources, not just a demand for the existing grid to handle.

Microsoft Has Already Expanded Renewable Energy

The Qcells deal builds on Microsoft’s broader renewable energy strategy. Microsoft says it matched 100% of its global electricity consumption with renewable energy in 2025. The company uses power purchase agreements and other long-term contracts to support renewable projects.

A power purchase agreement, or PPA, is a long-term contract to buy electricity from an energy project. Microsoft says these agreements can help developers secure financing for new wind, solar, and other carbon-free energy projects.

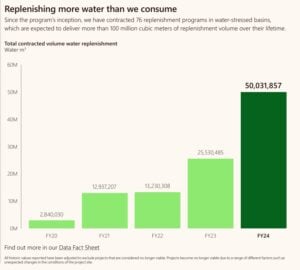
The company has also set a goal of becoming carbon negative by 2030. That means Microsoft aims to remove more carbon from the atmosphere than it emits. Its other 2030 goals include becoming water positive, reaching zero waste, and protecting ecosystems.

water replenishment
Source: Microsoft

These targets are becoming harder to achieve as Microsoft builds more AI infrastructure.

AI Growth Is Making Microsoft’s Emissions Challenge Harder

Microsoft’s sustainability data show the challenge. The company’s latest Environmental Sustainability Report covers fiscal year 2025 and measures progress against its 2020 baseline. Microsoft says the rapid growth of AI is changing the environmental impact of its infrastructure.

The company’s supply chain is also a major source of emissions. Microsoft says about 70% of its emissions come from purchased goods, services, and capital goods, according to its 2026 sustainability report. That includes the materials and equipment needed to build data centers and AI infrastructure.

This creates a difficult balance.

Microsoft needs to build more data centers to meet demand for AI services. At the same time, the company must reduce the emissions linked to construction, electricity use, equipment, and its wider supply chain.

Adding new renewable energy alongside that infrastructure could help address part of the problem.

Qcells Builds the Solar Supply Chain Behind the Deal

Qcells also brings a growing U.S. manufacturing base to the partnership. The company has been building a vertically integrated solar supply chain in Georgia. Its Cartersville facility is designed to bring Qcells’ annual module production capacity to 8.4 GW. The company says that it is enough to produce nearly 46,000 panels per day and power about 1.3 million homes annually.

The expansion supports a broader effort to build more solar manufacturing capacity in the United States. For Microsoft, working with a domestic solar manufacturer could help connect its data center growth with new U.S. energy supply.

Still, the partnership’s new phase is broader than solar panels alone. The companies are looking at how generation and flexible resources can work together with AI infrastructure.

Microsoft Qcells partnership

Could Microsoft’s Model Help Build Power as Fast as AI?

Microsoft and Qcells are testing a model that could build new energy supply alongside AI data centers, rather than placing all new demand on existing grids. The approach could combine solar generation, batteries and other flexible resources to support grid reliability as data center demand grows.

The need is significant. The IEA expects electricity for data centers to grow from 460 TWh in 2024 to over 1,000 TWh by 2030. It might even hit 1,300 TWh by 2035. That growth will require closer coordination between data center developers, utilities and energy companies.

Microsoft has already matched 100% of its electricity consumption with renewable energy and aims to become carbon negative by 2030. The Qcells partnership could take that strategy further by linking new clean energy capacity directly with new AI demand.

The companies have not disclosed how much generation or storage the partnership could ultimately add. Its success will depend on whether the model can scale while supporting communities, strengthening local grids and meeting the growing power needs of AI.

Lithium Prices Up 92% Year Over Year as PLS Group Posts A$526M Profit

Lithium’s recovery is giving Australia’s largest independent lithium producer a reason to become more aggressive about growth. PLS Group, formerly Pilbara Minerals, expects the lithium market to tighten in the coming years and is preparing to expand its flagship Pilgangoora operation in Western Australia.

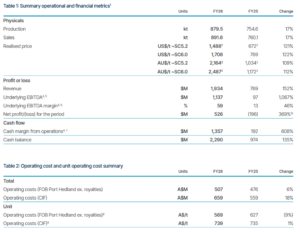
The company also returned cash to shareholders for the first time since 2023 after higher lithium prices helped drive a sharp recovery in FY2026 earnings. PLS reported an A$526 million net profit for the year ended June 30, compared with an A$196 million net loss a year earlier.

Revenue reached A$1.934 billion, while underlying EBITDA, a measure of operating earnings, climbed to A$1.137 billion.

The stronger results reflect both higher lithium prices and record production. They also show how quickly lithium miners can recover when prices turn after a prolonged downturn.

Lithium Price Rebound Puts PLS Back on the Front Foot

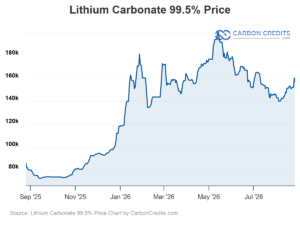
Lithium prices have staged a major recovery in 2026 after several years of weak conditions. It reached about CNY 157,000 per tonne on August 26, down 2.18% from the previous day but still 92% higher than a year earlier. The price had also gained about 7.2% over the previous month.

Lithium Carbonate 99.5% Price - CarbonCredits (7)

The recovery has changed the outlook for producers such as PLS.

The company’s FY2026 results clearly show the effect. PLS increased spodumene production by 17% to 879,500 tonnes and sales by 17% to 891,600 tonnes. Higher realized prices and tighter cost control helped push revenue to almost A$1.93 billion.

The company also ended FY2026 with A$2.29 billion in cash, giving it more room to invest in new capacity.

PLS financial results June 2026
Source: PLS Group

PLS Sees a Stronger Lithium Cycle Ahead

PLS CEO Dale Henderson has taken a bullish view of the market. He said the company believes lithium has entered a new part of its cycle, supported by strong demand and limited supply growth. He specifically noted:

โ€œLithium is a volatile market, and our strategy is designed to use that cycle to our advantage rather than as a limitation.โ€

PLS expects a supply shortfall to develop in the coming years, according to Bloomberg’s report on the company’s results. That view contrasts with the oversupply that weighed on lithium prices through much of 2024 and 2025.

The recent improvement has come as battery demand strengthens, while some producers remain cautious about bringing capacity back online after the price downturn.

PLS has already responded by restarting idled capacity and moving growth projects forward. The company said it entered FY2027 “larger, lower-cost, and financially stronger” than a year earlier.

Still, lithium remains a highly cyclical commodity. A new wave of supply could again pressure prices if production grows faster than battery demand.ย 

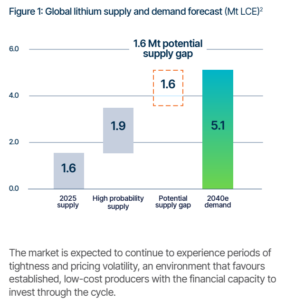
The Australian miner estimates that there would be around 1.6 Mt potential supply gap to meet the 2040 demand, growing from 1.5 million tonnes of lithium in 2025 to 5.1 million tonnes by 2040.

PLS global lithium demand and supply market outlook
Source: PLS Group

PLS Plans to Double Pilgangoora Capacity

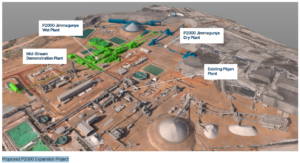
The biggest growth opportunity is P2000, a proposed expansion of the Pilgangoora operation. PLS is studying a brownfield expansion that could lift spodumene concentrate capacity to about 2 million tonnes per year. The company expects to complete its feasibility study in the December quarter of 2026.

PLS has already approved about A$175 million in pre-final investment decision spending to keep the project moving. The spending covers engineering, long-lead equipment, early site work, and infrastructure.

A final investment decision could follow the feasibility study, subject to the results, funding capacity, and market conditions. If approved, P2000 could produce its first ore in mid-2029.

The lithium miner estimates the project may need over A$1.2 billion in investment. It could create more than 1,000 construction jobs and support around 500 ongoing operational roles. The expansion would give PLS substantially more exposure to a stronger lithium market.

Pilbara Proposed P2000 Expansion Project
Source: PLS Group

The Company Is Bringing Capacity Back Online

PLS is not relying only on P2000. During FY2026, the company restarted the Ngungaju processing plant, which had been placed on care and maintenance during the lithium downturn. It is also progressing the Colina lithium project in Brazil and other growth initiatives.

This marks a clear change from the defensive strategy PLS used when lithium prices were weak.

During the downturn, producers focused on reducing costs, preserving cash, and cutting production where needed. As prices recovered, PLS began bringing capacity back and preparing for longer-term growth.

The company’s financial position now gives it more flexibility to do so. Its FY2026 cash balance reached A$2.29 billion, while it also completed its first US$600 million bond offering during the year.

That combination of stronger prices, higher production, and a larger cash position puts PLS in a stronger position to fund expansion.

First Dividend Since 2023

The lithium recovery is also flowing back to shareholders. PLS declared a fully franked final dividend of 5 Australian cents per share, representing a distribution of about A$161 million. It is the company’s first dividend since 2023.

The full-year dividend suggests the board now has greater confidence in cash generation. However, PLS still needs to balance shareholder returns against the large capital requirements of P2,000 and its other growth projects.

EVs, Batteries and the Next Wave of Lithium Demand

The long-term case for lithium rests heavily on demand from electric vehicles and energy storage. PLS has also pointed to growing demand from stationary batteries and emerging electric mobility markets, including electric trucks.

In April, CEO Henderson said customer discussions in China showed a broader recovery in lithium demand.

Energy storage is becoming particularly important. As grids add more solar and wind power, batteries can store electricity and supply it when renewable generation falls. That creates another source of lithium demand beyond electric cars.

The market, however, remains exposed to changes in battery chemistry, technology, and regional EV demand.

China’s growing use of sodium-ion batteries also creates a longer-term competitive risk for lithium in some applications, particularly lower-cost energy storage.

The Supply Crunch That Could Keep Lithium Prices Rising

PLS’s bullish outlook depends on supply failing to keep pace with demand. That is possible, but it is not guaranteed.

The lithium market has shown how quickly new supply can change prices. When prices surged in 2022 and 2023, producers and developers rushed to expand. The resulting supply growth helped push prices sharply lower.

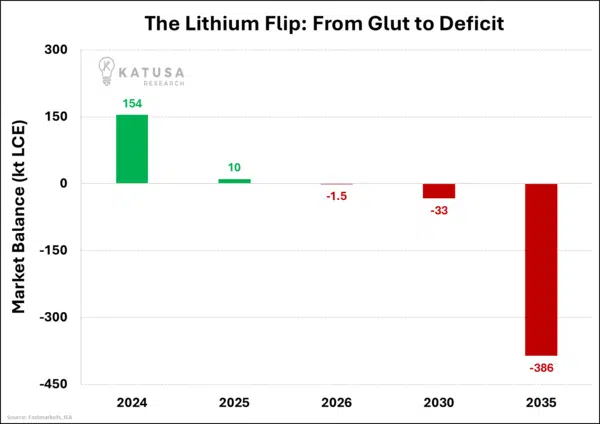
Now, years of weak prices have forced some projects to slow, suspend, or delay development. That creates the potential for a tighter market if demand rises faster than producers can respond.

lithium supply deficit KR

PLS is positioning itself for that possibility. Its P2000 project could eventually double Pilgangoora’s capacity to about 2 million tonnes a year, but the company will make the final investment decision only after completing its feasibility work.

This gives PLS some flexibility if market conditions weaken again.

PLS Shares Ride the New Lithium Bull Case

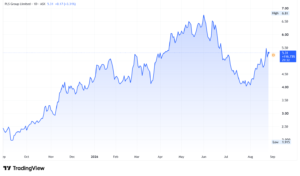
Investors have also responded to the stronger lithium outlook. PLS shares rose as much as 8.1% in Sydney on August 24 after the company released its FY2026 results, reversing an early decline.

The move reflects renewed confidence in lithium prices, PLS’s stronger earnings and its expansion plans. The stock’s performance also shows how closely PLS remains tied to the lithium cycle.

PLS stock price

Stronger prices can quickly lift revenue and margins, while another supply-driven downturn could have the opposite effect.

The Hard Part: Can Lithium Stay Tight?

PLS’s FY2026 results show how much the lithium market has changed in a year. Production reached a record 879,500 tonnes, revenue climbed to A$1.934 billion, net profit reached A$526 million, and the company restored its dividend.

At the same time, PLS is preparing for a potential supply shortage and considering a major expansion that could take Pilgangoora to about 2 million tonnes of annual capacity.

The key question now is whether lithium demand can stay ahead of new supply.

If it does, PLS could enter a stronger growth phase with the balance sheet and production base to benefit. If new supply returns faster than expected, the company could again face the price pressure that defined the previous downturn.

For the broader lithium market, PLS’s decision to expand is itself a sign of how quickly sentiment has shifted from oversupply and cost-cutting toward tighter supply and renewed investment.

US Biofuel Credit Market Faces Major Shake-Up From EPA Exemptions

Reuters reported that prices for U.S. ethanol blending credits plunged on Monday after the Environmental Protection Agency (EPA) extended a key compliance deadline and said it would rule on long-pending small refinery exemption requests by the end of August.

The move sent a shock through the U.S. biofuel credit market. Conventional ethanol Renewable Identification Numbers (D6 RINs) fell to $1.75 each, down 34 cents from Friday and their lowest level since April 15, according to Argus Media. The credits had traded as high as $2.50 on July 7.

Prices for 2026 biomass-based diesel RINs also weakened. They were last assessed at around $1.92 each, their lowest level since late April.

The sharp decline shows how closely the U.S. biofuel market depends on federal blending rules and the supply of compliance credits.

us biofuel market

What Are RINs and Why Do They Matter?

Renewable Identification Numbers, or RINs, are tradable credits created under the U.S. Renewable Fuel Standard (RFS).

The RFS requires obligated fuel companies, mainly refiners and importers, to demonstrate that they have met federal renewable fuel blending requirements. Companies can generate RINs by blending eligible biofuels into the fuel supply or buy credits from other market participants.

RINs therefore create a financial value around renewable fuel use.

When refiners need more credits than they can generate through their own blending activities, they must buy RINs. Higher compliance obligations or tighter credit supplies can push prices higher.

The opposite can also happen.

If the EPA grants exemptions that reduce the number of RINs refiners need, the market can suddenly have more credits available. That is what traders are now anticipating.

US Biofuel Market Remains Large

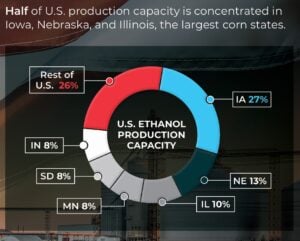
The United States is the world’s largest producer and consumer of fuel ethanol and one of the biggest markets for biodiesel and renewable diesel.

us ethanol
Source: ethanolrfa.org

Corn-based ethanol dominates the U.S. biofuel market. Most gasoline sold in the country contains some ethanol, with E10, a blend containing about 10% ethanol, forming the backbone of the market.

Higher ethanol blends such as E15 and E85 also contribute to demand, although their use remains much smaller.

The U.S. ethanol industry produces billions of gallons of fuel each year. That creates a large and established market for corn, ethanol production, transportation, blending and RIN generation.

The diesel side of the market has also expanded. Biodiesel and renewable diesel provide another major source of renewable fuel and compliance credits.

Renewable diesel is particularly important because it can be used in existing diesel infrastructure and is increasingly produced from feedstocks such as vegetable oils, animal fats and used cooking oil.

Demand for Biofuel Credits Is Driven by Federal Rules

The biggest source of demand for RINs is not simply fuel consumption. It is the federal compliance system.

Each year, the EPA establishes Renewable Volume Obligations (RVOs) that determine how much renewable fuel the market must account for.

Refiners and fuel importers receive obligations based on their share of the U.S. transportation fuel market. They then need enough RINs to demonstrate compliance.

That makes RIN demand closely tied to EPA policy.

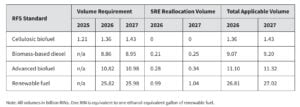
The EPA recently finalized record-high renewable fuel blending requirements for 2026 and 2027. Those requirements have increased compliance pressure on refiners and helped support RIN prices.

But the market is now facing a potential reversal.

biofuel renewable fuel EPA
Source: EPA

EPA Exemptions Could Add Billions of Credits

The EPA is reviewing 34 small refinery exemption petitions, with some dating back to July 2024.

Small refinery exemptions allow qualifying facilities to receive relief from their renewable fuel obligations when they can demonstrate that compliance would impose disproportionate economic hardship.

The market expects the EPA’s decisions to free up a significant number of RINs.

Representatives from the refining and ethanol industries, along with an analyst, estimate that the exemptions could free between 1.2 billion and 1.8 billion RINs for small refiners to use toward their 2025 compliance obligations.

The EPA had previously indicated that it could reallocate about 990 million RINs associated with exemptions. This potential supply is large enough to materially change the balance between RIN supply and demand.

Why RIN Prices Fell So Quickly

The selloff is largely about expectations.

Jessica Dell, head of U.S. biofuel pricing at Argus Media, said RIN prices lost substantial value during Monday’s session as the market reacted to the pending exemption decisions.

RIN prices had already fallen 5% on Friday. The EPA’s decision to extend the September 1 compliance deadline has added another layer of uncertainty.

Under the RFS, refiners must show that they met their 2025 biofuel blending obligations by September 1. They can do this by generating RINs through renewable fuel blending or purchasing credits from other market participants.

Giving refiners more time to comply could reduce immediate buying pressure.

More importantly, the deadline extension has been interpreted by some market participants as a possible signal that refiners could receive broader relief from their 2026 and 2027 obligations.

Agricultural economist Scott Irwin of the University of Illinois described the move as potentially signaling some form of “RIN relief” for future obligations.

Ethanol Producers Face a Different Equation

Lower RIN prices are not necessarily positive for the ethanol industry. Ethanol producers can generate RINs when they blend their fuel into the transportation system. Those credits provide an additional source of revenue.

When RIN prices fall, the value of that revenue stream also declines.

That can put pressure on producer margins, particularly when corn prices, energy costs, transportation expenses or other operating costs are high. Furthermore, the impact can vary across producers because ethanol economics depend on several factors, including corn prices, ethanol selling prices, distillers grains revenue and energy costs.

Still, the RIN market remains an important part of the broader economics of U.S. ethanol production.

Supply Could Become the Market’s Biggest Concern

The immediate question is how many credits will become available if the EPA grants the pending exemptions.

  • A release of 1.2 billion to 1.8 billion RINs would represent a significant addition to the pool of credits available for compliance. This could create a supply overhang and keep prices under pressure.

It could also reduce the incentive for some refiners to purchase additional credits in the spot market.

For the ethanol industry, this creates a difficult environment. Demand for renewable fuel may remain strong, but the value of the compliance credits attached to that fuel can fall when regulatory relief increases RIN availability.

What Happens Next?

The EPA’s decisions on the 34 exemption petitions will be the next major catalyst for the market. If the agency grants a large number of exemptions, RIN prices could face additional pressure as more credits become available or obligations are reduced.

On the other hand, if fewer exemptions are granted, the market could tighten again, particularly given the record renewable fuel requirements for 2026 and 2027.

The outcome will also influence the economics of U.S. refiners and biofuel producers.

For refiners, lower RIN prices can reduce the cost of meeting federal obligations. For ethanol and renewable diesel producers, however, weaker credit prices can reduce the value of an important revenue stream.

The episode highlights a central feature of the U.S. biofuel market: fuel demand, government mandates and carbon-related compliance markets are closely connected.

The U.S. can continue consuming large volumes of ethanol, biodiesel and renewable diesel while RIN prices fall sharply if regulatory changes increase credit supply.

For carbon and clean energy investors, the RIN market is therefore worth watching alongside traditional biofuel production data. Changes in EPA policy can quickly reshape the economics of renewable fuels, alter demand for compliance credits and influence investment decisions across the U.S. bioenergy sector.

Alberta Carbon Price Barely Raises Oil Sands Costs, Study Finds

Alberta’s industrial carbon price has had only a small effect on the cost of producing oil sands crude, according to a new study from the C.D. Howe Institute.

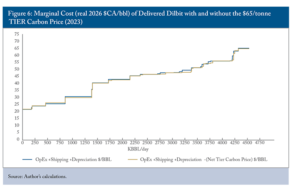
The report, published by economist G. Kent Fellows, finds that Alberta’s Technology Innovation and Emissions Reduction (TIER) system added an average of just C$0.70 per barrel to oil sands marginal production costs in 2023. On a production-weighted basis, the increase was even smaller at C$0.34 per barrel.

The findings come as Canada and Alberta prepare to raise the industrial carbon price over the next decade. Under their May 2026 agreement, Alberta’s headline TIER price will rise from C$95 per tonne in 2026 to C$115 in 2030, C$130 in 2035 and C$140 in 2040.

Despite those higher headline prices, the study finds that most oil sands projects should continue to face relatively modest carbon costs.

Carbon Price, Small Cost: Oil Sands Barely Feel the Heat

The C.D. Howe analysis uses project-level production and emissions data to estimate how TIER affects the marginal cost of producing oil sands crude.

In 2023, the system’s impact ranged from an effective C$1.09-per-barrel reduction in marginal costs at the low end to an additional C$4.05 per barrel at the high end. The negative figures represent an effective benefit under TIER because some facilities performed better than their emissions benchmarks and received more credits than they needed.

The average facility saw a C$0.70-per-barrel increase. But larger facilities generally performed better against their emissions targets, bringing the production-weighted average down to C$0.34 per barrel.

Alberta TIER carbon price oil sands 2023
Source: G. Kent Fellows. 2026. Buckets of Oil and Barrels of Steam: Quantifying Carbon Pricingโ€™s Impact in Albertaโ€™s Oil Sands. Toronto: C.D. Howe Institute.

That is small compared with oil sands operating costs. The study says 99% of operators have operating costs between C$21 and C$65 per barrel.

Some major projects, including Horizon Mine, Jackpine Mine, Muskeg River Mine, Kearl and Peace River, actually received a net benefit from TIER on a per-barrel basis.

Why the Headline Carbon Price Is Misleading

The study highlights an important difference between Alberta’s headline carbon price and the actual cost many oil sands facilities face. Under TIER, large industrial emitters do not simply pay the full carbon price on every tonne of emissions. The system uses emissions benchmarks and performance credits.

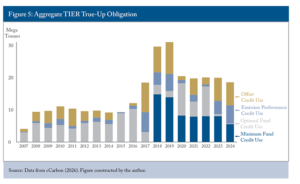
Facilities must also use fund contributions to meet a minimum portion of their true-up obligation, reducing from 40% in 2023 to 10% in 2026 and beyond. Data from 2023 and 2024 show facilities met only the minimum requirement, opting for cheaper market credits over higher-cost TIER fund contributions.

Alberta TIER true up obligations
Source: G. Kent Fellows. 2026. Buckets of Oil and Barrels of Steam: Quantifying Carbon Pricingโ€™s Impact in Albertaโ€™s Oil Sands. Toronto: C.D. Howe Institute.

Moreover, facilities that perform better than their benchmark can generate credits. Facilities that perform worse must acquire credits or otherwise meet their compliance obligations.

This means the headline price can rise substantially without creating the same increase in average production costs. That distinction becomes even more important under the new Canada-Alberta agreement.

The headline TIER price will reach C$140 per tonne by 2040, but Canada and Alberta have agreed to target an effective carbon price of C$130 per tonne. Alberta will also introduce a minimum transfer price for TIER credits beginning in 2030. That floor starts at C$60 per tonne in 2030 and rises to C$110 by 2040.

The government says the changes are designed to make Alberta’s industrial carbon market more stable and predictable.

Costs Stay Below C$5 Per Barrel Through 2050

The most important finding for the oil sands is that higher future carbon prices do not translate into extremely high per-barrel costs under the new system.

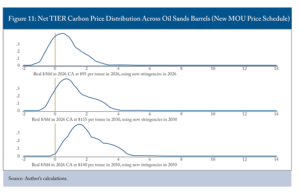
Fellows projects that no oil sands facility analyzed would face carbon pricing costs above C$5 per barrel through 2050 under the updated Canada-Alberta pricing and emissions-intensity schedules.

The study also says the estimates intentionally use assumptions that overstate carbon pricing costs. The results should therefore be viewed as an upper bound rather than a forecast of what companies will actually pay.

  • Under the new policy, most projects are expected to remain well below the C$5-per-barrel level.
TIER carbon price under new MOU
Source: G. Kent Fellows. 2026. Buckets of Oil and Barrels of Steam: Quantifying Carbon Pricingโ€™s Impact in Albertaโ€™s Oil Sands. Toronto: C.D. Howe Institute.

That matters because oil sands producers sell into global markets. Their carbon costs may affect profitability, but individual producers generally cannot set the global price of crude.

Cheap to Pay, Harder to Decarbonize

The relatively small cost does not mean the oil sands have a small climate impact.

Canadaโ€™s oil and gas sector produced 208 million tonnes of pollution in 2024. This was the country’s top source of greenhouse gases, making up 30% of national emissions. These sector emissions were 1.8% higher than the year before and 76% higher than in 1990.

However, newer data shows that the industry is starting to break the link between rising oil production and rising pollution. According to a June 2026 report from S&P Global Energy, absolute greenhouse gas emissions from Canadian oil sands rose by only 2% between 2024 and 2025, reaching an estimated 89 million tonnes.

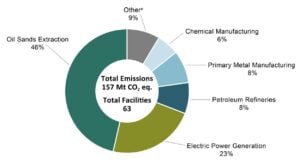
Despite these efficiency gains, oil sands operations still account for a huge chunk of Canada’s heaviest industrial footprints. In the latest federal registry, 63 individual facilities reported over 1 million tonnes of emissions each. Together, they accounted for 157 million tonnes (or 54%) of all emissions tracked under Canadaโ€™s federal reporting framework.

oil sands emissions share in Canada 2024
Source: Environment and Climate Change Canada (ECCC)

If carbon pricing adds only a small amount to production costs, will it be strong enough to push companies toward major emissions cuts? The answer depends partly on how companies respond to the financial signal.

Carbon Price Is Designed to Drive Investment

Carbon pricing is not intended only to increase operating costs. TIER also creates incentives for companies to invest in lower-emissions technologies and earn credits by improving their performance.

The new Canada-Alberta agreement reinforces that approach. The two governments plan to jointly support 75 million tonnes of emissions reductions through Carbon Contracts for Difference (CCfD), with costs shared equally. These contracts are designed to give companies more certainty about the future value of emissions reductions.

The agreement also sets annual tightening rates for oil sands emissions benchmarks. For large oil sands facilities, the rate is 2% annually from 2027 through 2040. Small oil sands facilities face a 1.5% rate from 2027 to 2030 and 1% from 2031 to 2040.

Those tightening rules could become more important than the headline carbon price itself. As benchmarks become stricter, companies may need to invest more in emissions reduction projects to avoid higher compliance costs.

Carbon Capture Could Change the Equation

The oil sands industry’s biggest proposed emissions reduction project is the Pathways Project, a carbon capture, utilization and storage network backed by major producers.

The May 2026 Canada-Alberta agreement sets a goal of 16 million tonnes per year of emissions reductions from Pathways projects. That includes at least 6 million tonnes per year of CCUS reductions by 2035, another 5 million tonnes by 2040 and a further 5 million tonnes by 2045.

The project is important because carbon capture could allow oil sands producers to reduce emissions without cutting production. Recent industry plans, however, remain under development.

Oil sands companies are targeting a final investment decision in late 2027 or early 2028 for the proposed first phase, according to the Oil Sands Alliance. The project’s cost and the structure of government support remain key issues.

The Real Test: Can a Small Cost Deliver Big Emissions Cuts?

Alberta’s experience shows why the headline carbon price alone does not tell the full story. The province will raise its TIER headline price from C$95 per tonne in 2026 to C$140 in 2040, yet the C.D. Howe study estimates that most oil sands facilities will continue to face carbon costs below C$5 per barrel.

That could make the system easier for producers to absorb. However, it also raises questions about whether the financial signal is strong enough to drive major emissions cuts. The answer will depend on what companies do with the policy incentives.

If producers use TIER credits and carbon contracts to fund carbon capture, efficiency improvements, and other lower-emissions technologies, the system could support both oil production and emissions reductions.

For Alberta, the bigger test is therefore not whether carbon pricing hurts oil sands profits. It is whether the system can turn a relatively modest cost into meaningful emissions cuts.

Oman Turns Landfill Methane Into Carbon Credits and Clean Energy

Oman is turning a major waste problem into a potential carbon market opportunity. Oman Environmental Services Holding Company (beโ€™ah) is expanding its work to capture landfill gas and develop carbon credits from the resulting emissions reductions. The state-owned waste-management company is also moving beyond simply burning the gas and plans to use recovered methane to generate electricity.

The effort focuses on the Al Multaqa and Barka landfills, where beโ€™ah has already registered landfill gas recovery projects under Verra’s Verified Carbon Standard (VCS). The strategy could give Oman another way to cut methane emissions while creating potential revenue from carbon markets.

Landfill Methane Is Oman’s Major Emissions Source

Landfills are central to beโ€™ah’s climate strategy because they produce large amounts of methane as organic waste breaks down.

Methane is a powerful greenhouse gas. Capturing it before it reaches the atmosphere can therefore create significant emissions reductions.

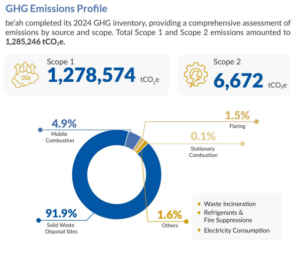
beโ€™ah’s 2024 GHG inventory shows how important this issue is. The company reported 1.285 million tonnes of CO2e in combined Scope 1 and Scope 2 emissions. Scope 1 accounted for 1.279 million tonnes, while Scope 2 emissions stood at 6,672 tonnes.

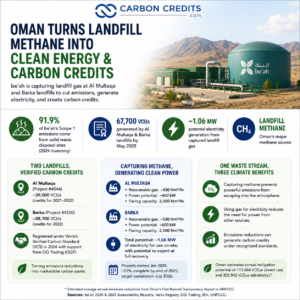
Solid waste disposal sites produced 91.9% of beโ€™ah’s Scope 1 emissions. Mobile combustion, mainly from the municipal waste-collection fleet, contributed another 4.9%, while flaring accounted for 1.5%. That makes landfill methane the clearest target for emissions reductions.

be'ah 2024 ghg emissions profile
Source: be’ah 2025 Sustainability Report

Two Landfills Already Generate Carbon Credits

beโ€™ah’s carbon credit program centers on the Al Multaqa and Barka landfill gas recovery projects. Moosa Al Aamri,
Landfill Operations Engineer at be’ah, remarked:

“The certification of carbon credits for Barka and Al Multaqa landfills marks a significant milestone in Omanโ€™s waste management journey. Through landfill gas capture and greenhouse gas reduction, beโ€™ah has transformed these sites into benchmarks of environmental responsibility and innovation. This achievement aligns with Oman Vision 2040โ€™s goals of sustainability and economic diversification, underscoring the critical role of modern waste management in tackling global climate challenges.”

The projects were registered under Verra’s VCS in 2024 as Project #4544 for Al Multaqa and Project #4550 for Barka. Al Multaqa received credits for 2021 and 2022, while Barka received credits for 2022.

By May 2025, beโ€™ah reported that the two projects had generated a combined 67,700 VCUs. Al Multaqa accounted for about 39,000 credits, while Barka generated about 28,700. One VCU represents one metric tonne of CO2e reduced or removed under the VCS.

The projects were developed with support from OQ Trading (OQT), which helps identify carbon credit opportunities and supports project development, certification, verification, and marketing.

This gives beโ€™ah a potential new source of revenue while supporting its emissions reduction work.

Oman Wants to Turn Methane Into Power, Not Just Flare It

The next stage goes beyond carbon credits. beโ€™ah is developing projects to capture landfill gas and turn it into electricity. The projects began in January 2025 and were scheduled for completion in July 2026. By the end of 2025, overall progress had reached about 55%, according to beโ€™ah’s 2025 Annual Report.

At Al Multaqa, the existing flaring system has a capacity of 2,000 normal cubic meters per hour (Nmยณ/hr). The site has estimated recoverable landfill gas of about 430 Nmยณ/hr and potential electricity generation of around 460 kilowatts (kW).

At Barka, the flaring system has a capacity of 2,500 Nmยณ/hr. Estimated recoverable gas is about 530 Nmยณ/hr, with potential electricity generation of around 600 kW. Together, the two sites could therefore produce about 1.06 MW of electricity at the estimated recovery levels.

beโ€™ah plans to use the electricity at the landfill sites. At full recovery capacity, it could also potentially export power.

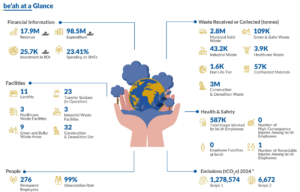
be'ah at a glance carbon emissions
Source: be’ah 2025 Sustainability Report

One Waste Stream, Three Climate Benefits

Using landfill gas for electricity can create more than one environmental benefit.

  • First, capturing methane prevents some of it from escaping into the atmosphere.
  • Second, using the gas for power can reduce the need for electricity from other sources.
  • Third, the emissions reductions can support carbon credit generation when projects meet the required standards.

Oman’s own climate reporting also identifies landfill gas recovery as an important mitigation measure.

In its first Biennial Transparency Report submitted to the UN Framework Convention on Climate Change, Oman listed landfill methane recovery for direct use and electricity generation among its waste-sector mitigation initiatives. The report estimated average annual emissions reductions of 113,864 tonnes of CO2e for direct methane use at Al Multaqa and 303,542 tonnes of CO2e for electricity generation at Barka and Al Multaqa.

These are estimated mitigation potentials, not verified carbon credits. That distinction is important. Actual credits depend on project monitoring, verification, methodology requirements, and issuance under the relevant carbon standard.

beโ€™ah Builds a Wider Carbon Management System

The landfill projects form part of a broader carbon management plan. beโ€™ah has created a Carbon Management Framework covering five stages:

  • Carbon accounting,
  • Identifying emissions-reduction projects,
  • Carbon credit registration and verification,
  • Issuing and selling or retiring credits, and
  • Integrating carbon activity into financial management.

This approach could help beโ€™ah identify more carbon projects across its waste operations. The company has already said it is exploring other opportunities in waste management and waste-to-energy. Its earlier sustainability reporting also identified possible projects involving other landfill cells and the use of captured gas.

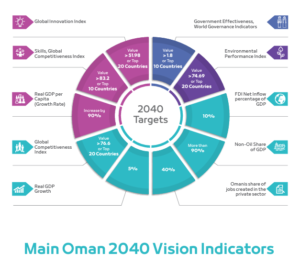
The strategy fits Oman’s wider Vision 2040 goals, which include economic diversification, environmental protection and more sustainable resource use.

Oman 2040 vision goals
Source: Climate Change Laws of the World

More Waste Could Mean More Methane and More Carbon Projects

The need for better landfill management is also increasing as waste volumes rise. beโ€™ah reported that Oman received 2.88 million tonnes of municipal solid waste in 2025, up from 2.57 million tonnes in 2024. Industrial waste intake also increased sharply to 43,216 tonnes, from 12,649 tonnes a year earlier.

  • beโ€™ah commissioned about 2.2 million tonnes of new engineered landfill capacity during 2025 and is developing another 3.4 million tonnes at Thumrait.

More waste means more landfill gas over time. That makes methane capture increasingly important if Oman wants to limit emissions from its waste sector. It also creates a larger potential base for future carbon projects.

Carbon Credits Could Turn Methane Cuts Into Revenue

The carbon credit opportunity is important because landfill gas projects can turn an emissions problem into a marketable environmental asset. beโ€™ah’s partnership with OQ Trading gives the company support in developing, verifying, and marketing credits.

The projects’ registration under Verra also provides a recognized framework for measuring and issuing credits. But carbon credits are not guaranteed revenue.

Project developers must prove that emissions reductions occurred and meet monitoring and verification requirements. Credit volumes can also vary depending on how much gas a landfill produces and how much the project captures.

That means beโ€™ah’s future carbon revenue will depend on actual gas recovery, project performance, and demand from carbon credit buyers.

Oman landfill waste to carbon credits be'ah

Oman Tests a Waste-to-Carbon Model

Oman’s landfill strategy shows how carbon markets can support practical waste management projects. beโ€™ah is targeting methane, which accounts for the vast majority of its measured emissions. It is also moving from simple gas flaring toward electricity generation at two major landfills.

The generated VCUs already provide an early example of how landfill emissions reductions can create tradable carbon assets. The next step will be scaling gas recovery and electricity generation while maintaining strong measurement and verification.

If beโ€™ah can expand these projects across more landfills, Oman could develop a larger waste-based carbon market while reducing methane emissions and producing useful energy.

ExxonMobil Hit as Germany Revokes 2.1 Million Carbon Credits From Chinese Projects

Germany has revoked carbon credits linked to 30 projects in China after authorities found serious concerns about the emissions reductions they claimed to deliver. The action has also affected ExxonMobil, which bought credits from one of the projects now under scrutiny.

The projects claimed a combined 2.1 million tonnes of CO2 reductions. One project backed by an ExxonMobil unit claimed nearly 96,000 tonnes of reductions, with the credits priced at about โ‚ฌ44 per tonne. That puts the reported value at roughly โ‚ฌ4.2 million.

The case highlights a wider problem for carbon credit markets. Even credits used in a government-backed compliance system can face questions over whether the promised emissions cuts actually happened.

Germany Finds Problems With Chinese Carbon Projects

The revoked credits came from upstream emissions reduction (UER) projects. These projects aim to cut emissions before crude oil reaches a refinery, such as by capturing gas that would otherwise be flared during oil production.

Germany allowed companies to use UER certificates to help meet their fuel emissions obligations. The system attracted interest because it offered a relatively low-cost way to reduce reported emissions.

However, German authorities began finding serious problems in several projects.

In September 2024, the German Environment Agency (UBA) announced it blocked certificates for 215,000 tonnes of CO2 from eight projects. Seven project applications were withdrawn after UBA identified serious legal and technical inconsistencies. In another Chinese project, UBA rejected certificates after finding that the project had started too early.

The agency also said it was investigating additional projects and had asked project operators to allow on-site inspections. The latest action goes much further, with authorities withdrawing credits from 30 Chinese projects.

ExxonMobil’s 96,000 Tonnes of Credits Under the Microscope

A Belgian ExxonMobil entity supported one of the projects, as stated in a German Environment Agency report, per a Bloomberg report. The project claimed to reduce nearly 96,000 tonnes of CO2. The credits sold for about โ‚ฌ44 per tonne, putting their reported value at approximately โ‚ฌ4.2 million.

ExxonMobil told Bloomberg that it operates in line with legal requirements and generally does not comment on ongoing investigations. The company’s involvement does not mean the oil giant has been accused of creating false emissions reductions itself.

The German investigation focuses on the projects and the claims behind the credits. This distinction is crucial. Companies can purchase credits in good faith and still face losses if authorities later invalidate them.

30 Projects, 2.1M Tonnes and Growing Questions

The 30 projects together claimed about 2.1 million tonnes of emissions reductions. That is roughly equivalent to the annual emissions from 500,000 cars, according to reporting on the German findings.

The investigation originally identified 45 projects as suspicious. Authorities have now withdrawn credits from 30 of them. However, the full picture is still developing.

Germany’s report names only six projects, while information on 24 projects remains redacted because investigations are still underway. The revocation decisions for the six named projects are final, according to Bloomberg’s reporting. This means it would be too early to describe every project in the wider investigation as fraudulent.

German authorities found enough issues to revoke credits from 30 projects. They are still investigating other cases.

Germany carbon credits Exxonmobil

Beijing Karbon Faces Scrutiny

The investigation also points to Beijing Karbon, a Chinese consultancy involved in many of the projects. According to the German report, Beijing Karbon was the main developer behind the 45 projects under investigation.

The report alleges that the company created the appearance of legitimate UER projects through deception. The case also raises questions about third-party verification.

Bloomberg reported that European auditing firms, like TรœV Rheinland, Mรผller-BBM Cert, and Verico SCE, checked some of the projects. This creates a bigger concern for carbon markets. Verification should offer an independent check that a project has achieved its claimed emissions reductions.

  • If questionable projects get through many layers of development and checks, buyers may struggle to assess credit quality.

Germany Tightens the Rules After the Credit Scandal

The scandal has already changed Germany’s approach to these credits. In 2024, UBA found that remote checks, satellite images, and document reviews often didnโ€™t fully catch misuse. The agency brought in an international law firm to support its investigations in China.

The agency also said it would continue reviewing other critical UER projects worldwide.

The German government has since moved to end the use of UER certificates for the country’s fuel emissions quota. Under the updated rules, recognition of these certificates was allowed only through 2025. That makes the current revocations part of a broader shift away from the system.

For carbon market participants, the episode shows how quickly regulatory decisions can change the value of credits that once qualified for compliance.

When a Carbon Credit Loses Its Climate Value

Carbon credits only have environmental value if they represent real emissions reductions. A company can use a credit to claim that one tonne of emissions was reduced, avoided or removed elsewhere. But if the underlying project did not deliver that reduction, the climate benefit disappears.

That creates a serious problem for buyers.

A credit may pass project reviews, receive third-party verification and enter a regulated market. Years later, a regulator can still discover problems and withdraw it.

Germany’s action shows that regulatory approval is not necessarily a permanent guarantee of credit quality. It shows why strong monitoring and on-site checks are important. This is especially true for projects in countries or sectors with limited oversight from authorities.

Invalid Credits Can Leave Buyers With a Bigger Bill

The financial impact extends beyond the original purchase price. When authorities revoke credits used for compliance, companies may need to obtain replacement units to meet their emissions obligations.

That can create an additional cost if valid credits are more expensive than the original ones.

For ExxonMobil, the reported โ‚ฌ4.2 million value of the affected project provides a measure of the potential exposure tied to that one project. The overall financial impact depends on how many credits the company bought, used, or held. It also depends on the replacement obligations that apply.

The issue is therefore larger than the value of one transaction. Credit quality risk can turn into a financial risk for companies relying on carbon markets to meet regulations.

A Warning for the Wider Carbon Market

Germany’s move tests carbon market integrity. This comes as governments boost carbon pricing and international emissions trading.

The EU’s Emissions Trading System (ETS) covers more than 10,000 installations across the power, industrial and aviation sectors. Since 2005, it has helped reduce emissions from covered installations by about 50%, says the European Environment Agency.

That progress depends partly on confidence in the rules and measurement systems behind carbon markets. The ExxonMobil case shows what can happen when that confidence breaks down.

For project developers, stronger monitoring and verification will become increasingly important. For buyers, the episode is a reminder to look beyond the price and label attached to a credit.

And for regulators, it shows that removing questionable credits after they enter the market is not enough. Stronger checks are needed before credits reach buyers in the first place.

Germany’s investigation is still developing, with 24 of the 30 projects remaining under investigation. Still, the revocations already send a clear message: carbon credits must represent real emissions reductions, or their market value can disappear.